What might be Robert Barro’s argument?
Paul Krugman, Brad DeLong, Justin Wolfers and others are not sure what is Robert Barro’s argument or model in his recent Op-Ed. I am puzzled by these responses, because, while I do not pretend to speak for Barro, I see at least one simple answer to these puzzlements.
Consider the following model. Sometimes growth slows down and afterwards it speeds up again. Temporary losses tend to be undone in future periods. For one thing the Solow model implies catch-up growth, furthermore cyclical losses may exhibit mean-reversion. There is in the meantime some depreciation of labor skills, from unemployment, but long-run output and welfare really does for the most part depend on the forces which govern economic growth. (Increases in the variance of consumption are not enough to overturn that emphasis.) That implies lower government spending in most areas of the economy, and it also implies lower taxation of capital, as supported by many empirical papers on growth including some by Barro himself.
That view may not be true (in my TGS book you will find some dissent from it but from another direction), but it’s hardly bizarre or economically illiterate. If some writers aren’t totally explicit, it could be they don’t have enough words and feel that a large enough part of their audience takes the emphasis on growth and its preconditions for granted.
We are once again witnessing the renaissance of old Keynesian economics as a theory of the long run not just the short run. The “New Old Keynesians” are of course entitled to their opinions, but given their minority status, it is strange when they find others difficult to comprehend.
Cities as hotels
Earlier this year I posted about India’s private city, Gurgaon. Gurgaon has grown from nothing to a city of 1.5 million people in just 30 years and it has done so based almost entirely on the private provision of public goods, including transportation, utilities, and security. Gurgaon is a desirable place to live in India but it has grown haphazardly as a city of private oases, rather than as an integrated city. As a result, Gurgaon has not enjoyed all the benefits of economies of scale in infrastructure provision or the benefits that come from internalizing externalities–the types of benefits that are possible with a single owner or integrated political system. As Matt Yglesias explained at the time:
Imagine if someone owned all of San Francisco and leased the land and structures out. Well obviously he’d want to have some kind of fire department and building standards to protect his investment. And he’d want to have a security force, since crime would reduce the value of the rent. And he’d want there to be some parks, because people like parks and their presence will increase the rent he can charge. (Indeed, my building includes a small private park). And obviously he’d need schools and really all the rest. …But in order to internalize the benefits of privately provided infrastructure, parks, public safety, etc. the scale of the enterprise would have to be really big. Like the size of a whole city.
Gurgaon, however, is not unique. Private cities are growing throughout the developing world and some of them are quite large.
Renaissance Partners, the investment unit of Moscow-based Renaissance Group, plans to build a 6,400- acre city in the Democratic Republic of Congo as it seeks to benefit from Africa’s urbanization.
The Russian firm is working on a master plan for the new urban center after securing the land outside Lubumbashi, the country’s second-largest city… Renaissance is considering similar projects in Ghana, Nigeria, Senegal and Rwanda, he said.
“The West has peaked in terms of economic growth and the new markets are in Africa,” Meyer, 39, said. “And the main drivers of this growth in Africa are going to be cities.”
Renaissance’s Lubumbashi project will be more than double the size of Tatu City, the $5 billion center that the Russian firm is building from scratch outside the Kenyan capital of Nairobi. The Moscow firm, headed by Stephen Jennings, plans to take advantage of Africa’s economic growth and emergence of a growing urban middle class demanding better infrastructure.
6,400 acres is a small city, about the size of Apple’s home of Cupertino CA (pop: 58,000), but it is big enough that Renaissance partners will have an incentive to build public goods such as city-wide sewage, parks, roads (congestion pricing!), an electric plant and grid and so forth, exactly as Matt argued (see also The Voluntary City).
Private cities are happening now for a reason. Africa, India, and China are urbanizing more rapidly than has ever occurred in human history. In Africa, the number of urban dwellers is projected to increase by nearly 400 million, in India at least 250 million will move to cities and in China more than 400 million will move to cities in just the next 20 years. Not all of these people will move to older cities, which are not always in the right places and which rarely possess anything like the right material let alone the right political infrastructure. The rising middle-class want to live in first-world cities and in many of these countries only the private sector can deliver those cities.
The rapid urbanization of the developing world is an opportunity to remake cities anew. Private cities as hotels on a grand scale.
The consumer hourglass theory?
P&G isn’t the only company adjusting its business. A wide swath of American companies is convinced that the consumer market is bifurcating into high and low ends and eroding in the middle. They have begun to alter the way they research, develop and market their products.
Food giant H.J. Heinz Co., for example, is developing more products at lower price ranges. Luxury retailer Saks Inc. is bolstering its high-end apparel and accessories because its wealthiest customers—not those drawn to entry-level items—are driving the chain’s growth.
Citigroup calls the phenomenon the “Consumer Hourglass Theory” and since 2009 has urged investors to focus on companies best positioned to cater to the highest-income and lowest-income consumers. It created an index of 25 companies, including Estée Lauder Cos. and Saks at the top of the hourglass and Family Dollar Stores Inc. and Kellogg Co. at the bottom. The index posted a 56.5% return for investors from its inception on Dec. 10, 2009, through Sept. 1, 2011. Over the same period, the Dow Jones Industrial Average returned 11%.
“Companies have thought that if you’re in the middle, you’re safe,” says Citigroup analyst Deborah Weinswig. “But that’s not where the consumer is any more—the consumer hourglass is more pronounced now than ever.”
…Firms catering to low-income consumers, such as Dollar General Corp., also are posting gains, boosted by formerly middle-class families facing shrunken budgets. Dollar stores garnered steady sales increases in recent years, easily outpacing mainstream counterparts like Target Corp. and Wal-Mart Stores Inc., which typically are more expensive.
Here is more, no need to click on their silly links.
Bond markets in everything
But there is a backdoor onto Centre Court. About 2,500 seats are reserved for investors in the club’s so-called debentures, or bonds.
The club has issued these since the 1920s to finance development. But instead of paying cash coupons, like regular bonds, Wimbledon debentures pay interest in something much more valuable: tickets.
Holders get one ticket for each day of the Wimbledon tournaments during the five-year life of the bond. And here is the kicker: If you don’t feel like going on any given day, you can sell it—legally.
Such mini-bonds are a new trend in the UK, in part because the banking system is skittish about allocating credit to many small firms.
Assorted links
1. Business investment as a key to recovery, from Greg Mankiw. Lots of important truth in this piece.
2. Dalit classical liberalism, and here (pdf).
3. Robert Barro’s recipe for change.
4. Good analysis of how the second Greek bailout relates to the first, cynical piece. Here is an intelligent piece on doing the unthinkable for Europe.
5. Raghuram Rajan argues against a dose of inflation. And surprise as a reason to drink cheap wine, via The Browser.
Douglas Irwin on the 1937-38 contraction
If we are to avoid the mistakes of the past, it is important to have an accurate assessment of what those past mistakes were. The severity of the Recession of 1937-38 was not due to contractionary fiscal policy or higher reserve requirements. By contrast, the policy tightening associated with gold sterilisation was not modest – it did not simply reduce the growth of the monetary base by a few percentage points, it stopped its growth altogether. While the Federal Reserve is often blamed for its poor policy choices during the Great Depression, the Treasury Department was responsible for this particular policy error.
Here is more, and the paper is here. This should be considered the new default view.
Sentences to ponder
“China is a poor country with only $4,000 per capita income,” Yu Yongding, a Chinese top economist and former member of the central bank’s monetary policy committee said in an interview in China. “To talk and think about China to rescue countries with $40,000 per capita incomes is ridiculous.”
The article (mostly on Europe) is here. I can imagine a minimum of three theories of geopolitical influence:
1. You get it by having a nice country and it is then more or less automatic, possibly proportional to size as well.
2. It is hard to get in any case, as most countries do what they want anyway and are not much susceptible to outside influence.
3. Geopolitical influence is proportional to how much a government invests in it.
To the extent #3 is true, it does not bode well for the future of the welfare state.
Predictions on Greece and Germany
From Yanis Varoufakis:
Greece will not be allowed to default before Germany first puts in place a decent plan for splitting Greece’s monetary system from that of the surplus countries. But if I am right that such a plan cannot involve the mere expulsion of Greece from the euro, as it will kick off a chain reaction that will eventually knock France out for a sixer before returning to Frankfurt and Berlin to haunt the ‘planners’, the only logical conclusion that I can come to is that, behind all the talk of a German plan to contain a Greek default or to push Greece out of the euro, lies the groundwork for a pragmatic plan that sees Germany bailing itself out; a plan according to which Germany will round up countries it truly deems worthy of sharing its new currency with (the other three surplus countries of the existing eurozone plus perhaps Poland, the Czech Republic and even Estonia) and exiting in the most orderly manner possible; offering, for example, to the eurozone countries that will be left behind (fretting France in particular) a few gifts (e.g. Germany may choose to foot the bill for existing bailouts), an illusion of unity (e.g. suggesting that the new Germanic currency is also minted and administered by the ECB – which will now be responsible for more than one currency at once), and some vague promises (of possible fusion of these currencies, once the ‘right’ discipline has been knocked into the hearts and minds of the undisciplined).
Here is more, interesting throughout. Maybe the Germans who resigned from the ECB basically see something like this coming, and wish to husband their political capital with the hard money factions of German politics.

Here is Yanis on Twitter, he covers Greece.
From the comments, on local employment of teachers
The scaling in the chart makes a big difference. Here’s the data behind the chart, which can by found by following a link on the site that Tyler links to: http://1.usa.gov/oOQXeO. For the local government column only and April figures. (May would be better but the series runs out at April 2011.) April 2011 was at 8.3 million, about 160K less than the peak two Aprils earlier. That’s about 1.5% difference.
That is from RZO, the link and context is here. In the same comment thread, Frank Howland notes that:
K-12 enrollments fell by 0.85% from 2007 to 2009
That’s not exactly the same years and the data go only to 2009 but could it be a general trend across 2009-2011? Given that context, there is still some decline in per capita local teacher employment. Note this is a sector where there is a growing realization that quite a few of the workers should, for non-cyclical reasons, be fired anyway.
Addendum: Karl Smith has a useful graph with seasonal adjustment, coming up with somewhat different numbers.
Is Social Security a Ponzi Scheme?
Matt Yglesias says anyone who thinks social security is a Ponzi scheme is nuts. So let’s take a look at some of these nuts. First up is Nobel prize winner Paul Samuelson who wrote:
The beauty of social insurance is that it is actuarially unsound. Everyone who reaches retirement age is given benefit privileges that far exceed anything he has paid in — exceed his payments by more than ten times (or five times counting employer payments)!
How is it possible? It stems from the fact that the national product is growing at a compound interest rate and can be expected to do so for as far ahead as the eye cannot see. Always there are more youths than old folks in a growing population. More important, with real income going up at 3% per year, the taxable base on which benefits rest is always much greater than the taxes paid historically by the generation now retired.
…A growing nation is the greatest Ponzi game ever contrived.
Samuelson wrote that in 1967 riffing off his classic paper of 1958. By “as far as the eye cannot see” he apparently meant not very far because it soon became clear that the system could not count on waves of youths or rapid productivity growth to generate the actuarially unsound returns that made the program so popular in the early years.
Milton Friedman and Paul Samuelson rarely agreed on much but Friedman also called social security a Ponzi scheme. In fact, he called it The Biggest Ponzi Scheme on Earth but perhaps Yglesias puts Friedman in the nut category so let’s go for a third Nobel prize winner who recognizes the Ponzi like nature of social security, none other than…..Paul Krugman (writing in 1996):
Social Security is structured from the point of view of the recipients as if it were an ordinary retirement plan: what you get out depends on what you put in. So it does not look like a redistributionist scheme. In practice it has turned out to be strongly redistributionist, but only because of its Ponzi game aspect, in which each generation takes more out than it put in. Well, the Ponzi game will soon be over, thanks to changing demographics, so that the typical recipient henceforth will get only about as much as he or she put in (and today’s young may well get less than they put in). (ital added, AT)
Of these, I agree the most with Krugman. Social Security is not necessarily a Ponzi scheme but it only generated massive returns in the past because of its Ponzi-like aspects. The Ponzi-like aspects are now over and social security is turning into what is essentially a forced savings/welfare program with, as Krugman recognizes, crummy returns for average workers. Social security is thus a Ponzi scheme which has not gone bust but it has gone flat.
How many unemployed teachers are there?
This bit from Bruce Yandle challenges the conventional wisdom:
As to hiring teachers, total employment in local government education is already up by one million workers since August 2010. Teacher employment in state government nationwide is up 300,000 workers. The unemployment rate in education and health services at 6.3% is one of the nation’s lowest unemployment rates. While the president implied that teachers were being cut from payrolls at a heavy pace, the data say otherwise. The president’s efforts are seen as misguided if the goal is to ease some of the pain in high unemployment sectors.
Here is another source:
As Figure 1 shows, state government education employment is up by 2.1 percent since the start of the recession while all other state government employment is down 1.9 percent — a substantially larger decline than in other parts of the state-local sector. State government non-education employment began falling less than a year into the recession, and fell below its pre-recession level about a year and a half after the start of the recession.
Do you wish to see more, including on local government education employment?
This BLS graph (look under “And which industries show declining employment over the summer?”) shows a strong seasonal trend which may confound some month-specific citations, but still the number seems to be back to where it had been in earlier years (admittedly the scaling and visuals are not what I would wish for) and more importantly it is hard to spot much effect of the recession at all:
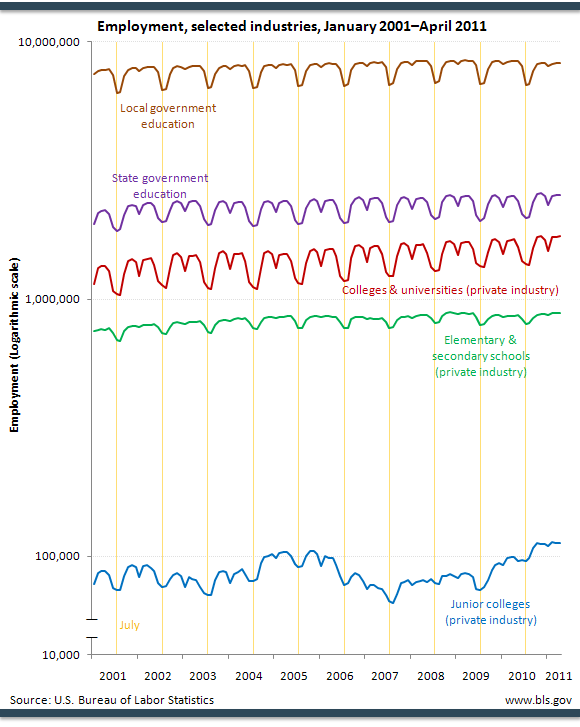
So what exactly is the case here for stimulus of this sector? Is this really a sector to target? I would gladly see and consider alternate numbers and interpretations, but so far I file this under: “Yet another example of something the press should have reported about a President’s speech but didn’t.” Once again, it is the disaggregated demand which matters.
Assorted links
1. Property value calculator for the board game Monopoly.
3. Excellent piece by Stephen King on our current economic predicament, highly recommended.
4. In defense of Georgia Work$.
5. How to get out of our mess, by Jim Manzi. Notice the emphasis on wealth creation. And are scientists well-suited to be entrepreneurs?
New edition of Econ Journal Watch
The link is here, and there is a symposium of articles on property as a “bundle of rights,” including a contribution from Richard Epstein. There is also a podcast on whether papers with lemmas give rise to propositions which are tested in subsequent research.
When did the U.S. labor market slow down?
Scott Winship, at his new Brookings gig, reports:
The bleak outlook for jobseekers has three immediate sources. The sharp deterioration beginning in early 2007 is the most dramatic feature of the above chart (the rise in job scarcity after point C in the chart, the steepness of which depends on the data source used). But two less obvious factors predated the recession. The first is the steepness of the rise in job scarcity during the previous recession in 2001 (from point A to point B), which rivaled that during the deep downturn of the early 1980s. The second is the failure between 2003 and 2007 of jobs per jobseeker to recover from the 2001 recession (the failure of point C to fall back to point A).
Unemployment increased during the 2001 recession, but it subsequently fell almost to its previous low (from point A to B and then back to C). In contrast, job openings plummeted—much more sharply than unemployment rose—and then failed to recover. In previous recoveries, openings eventually outnumbered job seekers (where a rising blue line crosses a falling green line), but during the last recovery a labor shortage never emerged.
…Whatever the causes, the evidence is clear that the health of labor markets were compromised well before the recession.
There is much more at the link, including some very good graphs.
The economics of bombs
As the bombs get more difficult to construct or operate, the costs rise. Bombs activated with a remote detonator like a cellphone cost a mere $345 and accounted for a surprisingly small — 12.6 percent — of attacks, perhaps owing to the U.S.’ hard-won ability to jam the detonator signal. (One would imagine the major cost component is the cellphone.) For insurgents to turn a car into a bomb or convince someone to kill himself during a detonation — or both — the cost shoots up into the thousands: $10,032 for a suicide bomber; $15,320 for a car bomb; nearly 19 grand to drive a car bomb. All together, those relatively expensive attack methods accounted for fewer than six percent of bomb attacks in 2009.
Most of those bombs have gotten cheaper to produce. In 2006, victim-operated IEDs cost an average of $1,125. Command-wire bombs were $1,266. Remote detonation bombs? The same. And as the costs dropped, victim-operated and command-wire detonated bombs skyrocketed. Back in 2006, they accounted for merely 21.3 percent and a piddling 1.9 percent of all bomb attacks, respectively.
But the sophisticated bombs have gotten more expensive. Car bombs cost $1,675 on average in 2006 — which seems absurdly low, given the cost of one involves acquiring and then tricking out a car. And the going rate on suicide bombers appears to have risen, from $5,966 in 2006 to nearly double that in 2009. Accordingly, both accounted for over 16 percent of IED attacks in ‘06. And JIEDDO says it has preliminary reporting indicating that suicide bombers cost $30,000 as of January.
Here is more and for the pointer I thank David Curran.