Monday assorted links
1. Claims about semaglutide. Not to be taken as endorsement of the claims, one way or the other, but worth further investigation.
3. Claims that lab-grown meat are worse for the environment.
Two Podcasts
Two podcasts I have enjoyed recently, First, The Social Radars, headed by Jessica Livingston and Carolynn Levy, co-founder and managing director of Y Combinator respectively. Jessica and Carolynn bring a lot of experience and trust with them so the entrepreneurs they interview open up about the realities of startups. Here is a great interview with David Lieb, creator of Google Photos and before that the highly successful failure, Bump.
I’ve also enjoyed the physician brothers Daniel and Mitch Belkin at The External Medicine Podcast. Here’s a superb primer on drug development from the great Derek Lowe.
Pristina, Kosovo bleg
Violence permitting, I will be there soon. So what should I see and what should I do? I thank you all in advance for your wise counsel.
The strange recession that is Czechia (from my email)
From the very perceptive Kamil Kovar, these are his words I will not double indent:
“Seeing your recent brief post on recession I was wondering whether you are thinking about writing a longer post on the topic of recessions in general? I find the recent macroeconomic developments very intriguing, as they challenge my previous notions of what is a recession and what pushes us into recession, and would be very interested in hearing what you think.
To be more specific, let me use European developments, which I think are even more thought-provoking from this perspective than US developments. Take an extreme example of Czechia, which combines following facts:
- GDP has contracted for two quarters in a row, each time around 0.3% non-annualized. It is still below its pre-pandemic peak.
- Consumption has contracted for 5 quarters in a row, cumulatively 7.6%.
- Fixed investment has decreased in last quarter as well, albeit after strong recovery throughout the previous year and a half.
- The reason why GDP did not drop more is because net exports surged from their extremely low values reached during the pandemic period. In last quarter government consumption also helped a lot.
- Despite all the weakness, labor market is tight, with unemployment rate close to its pre-pandemic historical lows (in case you don’t know, it is ridiculously-sounding low at 2.1%), and employment continuing to grow.
(This as of March; more recent data continued in these trends, albeit GDP overall increased a tad bit. Also, Germany is going through something similar, albeit at much smaller scale).
It feels like this combination just does not fit in together in terms of standard macroeconomics – if you would tell me only about consumption (2) I would say the country has to be in recession, but investment (3) and labor market (5) are clearly saying no recession. If it would be just labor market, then I could accept that it is case of labor hoarding distorting the picture, but investment also remaining robust is just hard to reconcile with recession.
So I was wondering in what way, if any, did the last update your beliefs about “what is a recession and what pushes us into recession” in the light of the puzzling macroeconomic data of last year or so…
P.S.: In case you want to read more on the case of Czechia, or my take on what it all means, I had a blog post few months back:
https://kamilkovar.substack.com/p/it-or-isnt-it-recession-on-regular
My way of reconciling the data with my mental models is that got real shocks pushing us into RBC-style recession, but for whatever reason we did not get the typical demand shocks that lead to a more standard recession.”
TC again: Worth a ponder!
Acemoglu on the Turkish polity and economy
Preliminary but fairly clear results from the runoff of the Turkish elections show that President Erdogan will have a historic third term. This has implications for democracy and the economy.
— Daron Acemoglu (@DAcemogluMIT) May 28, 2023
Sunday assorted links
The debt ceiling deal
Ho hum. Political bargaining, so what else is new? Kicking fiscal problems down the road, so what else is new? True permitting reform? We’ll see how much they end up doing away with judicial review.
As I stated long ago, I don’t favor either having a debt ceiling or using such a debt ceiling for strategic purposes. But this deal is not very different from what would have resulted from the normal appropriations process, is it? All in all, not worth monkeying with the Constitution for, with such dubious elements as minting the coin, invoking the amendment, and so on. The influence of Donald Trump really is spreading, isn’t it? There may yet be a final round of drama, but the people who treated this event as the nothing burger it is were on the right track the whole way through.
Identify a Market Failure and Win Prizes!
The University of Chicago’s Market Shaping Accelerator, led by Rachel Glennerster, Michael Kremer, and Chris Snyder (Dartmouth), is offering up to two million dollars in prizes for new pull mechanisms and applications.
Our inaugural MSA Innovation Challenge 2023 will award up to $2,000,000 in total prizes for ideas that identify areas where a pull mechanism would help spur innovation in biosecurity, pandemic preparedness, and climate change, and for teams to design that incentive mechanism from ideation to contract signing.
Participating teams will have access to the world’s leading experts in market shaping and technical support from domain specialists to compete for their part of up to $2 million prize during multiple phases. Top ideas will also gain the MSA’s support in fundraising for the multi-millions or billions of dollars needed to back their pull mechanism.
…Pull mechanisms are policy tools that create incentives for private sector entities to invest in research and development (R&D) and bring solutions to market. Whereas “push” funding pays for inputs (e.g. research grants), “pull” funding pays for outputs and outcomes (i.e. prizes and milestone contracts). These mechanisms “pull” innovation by creating a demand for a specific product or service, which drives private sector investment and efforts towards developing and delivering that product or technological solution.
One example of a pull mechanism is an Advance Market Commitment (AMC), which is a type of contract where a buyer, such as a government or philanthropic organization, commits to purchasing (or subsidizing) a product or service at a certain price and quantity once it becomes available. This commitment creates a market for the product or service, providing a financial incentive for innovators to invest in R&D and develop solutions to meet that demand.
The first round of prizes are $4,000 for an idea!
The submission template asks applicants to identify a market failure where the social value exceeds private incentives and where we know the measurable outcome we want to encourage (e.g. the development of a vaccine, capturing carbon out of the air, etc.). Submissions are accepted from individuals 18 years and older and organizations around the globe whose participation and receipt of funding will not violate applicable law.
See here for more.
Do tax increases tame inflation?
Here is a new AER article by James Cloyne, Joseba Martinez, Haroon Mumtax, and Paolo Surico. After an extensive data analysis, they arrive at this conclusion:
Based on US federal tax changes post–World War II, our answer is “yes” if personal income taxes are increased but “no” if corporate income taxes are increased.
Of course this is consistent with the view — no longer so commonly admitted — that higher corporate tax rates do have negative supply side effects. There is an ungated version of the paper here.
Selective reporting of placebo tests in top economics journals
Placebo tests, where a null result is used to support the validity of the research design, is common in economics. Such tests provide an incentive to underreport statistically significant tests, a form of reversed p-hacking. Based on a pre-registered analysis plan, we test for such underreporting in all papers meeting our inclusion criteria (n=377) published in 11 top economics journals between 2009-2021. If the null hypothesis is true in all tests, 2.5% of them should be statistically significant at the 5% level with an effect in the same direction as the main test (and 5% in total). The actual fraction of statistically significant placebo tests with an effect in the same direction is 1.29% (95% CI [0.83, 1.63]), and the overall fraction of statistically significant placebo tests is 3.10% (95% CI [2.2, 4.0]). Our results provide strong evidence of selective underreporting of statistically significant placebo tests in top economics journals.
That is from a new paper by Anna Dreber, Magnus Johannesson, and Yifan Yang.
That was then, this is now
Florida Gov. Ron DeSantis will subject passengers on flights from New York, New Jersey and Connecticut to to mandatory isolation for two weeks after efforts to curb gatherings in those states prompted residents to leave and head to Florida.
DeSantis made the announcement Monday during a hastily called news conference a day after Florida’s number of confirmed coronavirus cases surged past 1,000…
“We wish our friends in New York well, they have a tough fight,” he said, “but we also have to protect our folks here in the state of Florida.”
The order, beginning Tuesday, requires people arriving by air from any location with “substantial community spread” to isolate themselves for 14 days or the duration of their stay, whichever is shorter. Airline employees and professionals responding to the coronavirus emergency are exempt, including military and health officials.
A violation of the mandatory quarantine will be a criminal misdemeanor punishable by up to 60 days in jail and a $500 fine.
Here is the Politico article from March 23, 2020. Via Matt Y.
Saturday assorted links
Can the Shingles Vaccine Prevent Dementia?
A new paper provides good evidence that the shingles vaccine can prevent dementia, which strongly suggests that some forms of dementia are caused by the varicella zoster virus (VZV), the virus that on initial infection causes chickenpox. The data come from Wales where the herpes zoster vaccine (Zostavax) first became available on September 1 2013 and was rolled out by age. At that time, however, it was decided that the vaccine would only be available to people born on or after September 2 1933. In other words, the vaccine was not made available to 80 year olds but it was made available to 79 year and 364-day olds. (I gather the reasoning was that the benefits of the vaccine decline with age and an arbitrary cut point was chosen.)
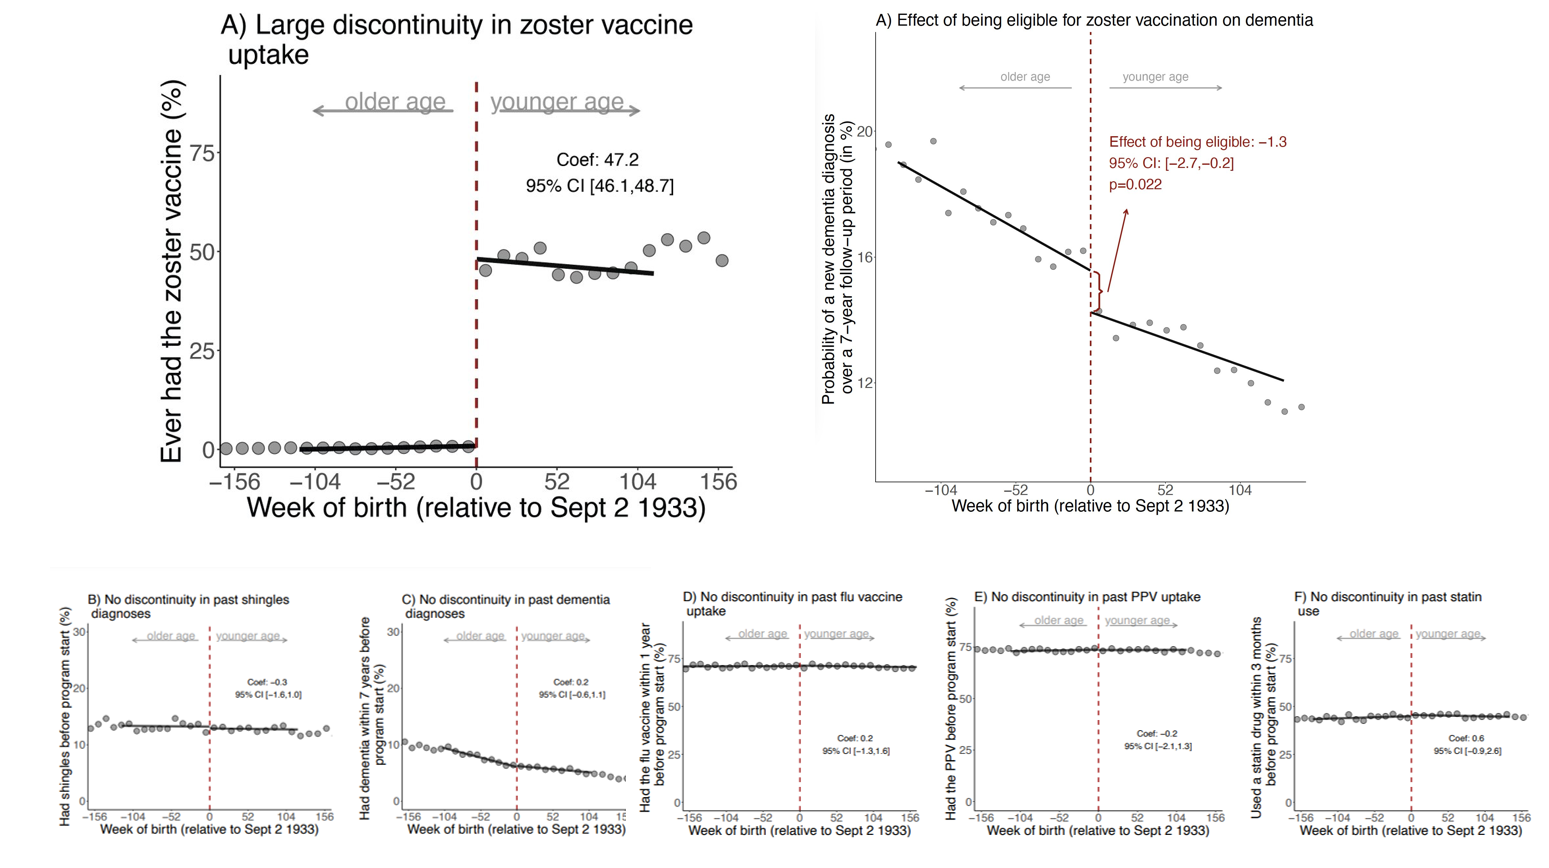
The cutoff date for vaccine eligibility means that people born within a week of one another have very different vaccine uptakes. Indeed, the authors show that only 0.01% of patients who were just one week too old to be eligible were vaccinated compared to 47.2% among those who were just one week younger. The two groups of otherwise similar individuals who were born around September 2 1933 are then tracked for up to seven years, 2013-2020. The individuals who were just “young” enough to be vaccinated are less likely to get shingles compared to the individuals who were slightly too old to be vaccinated (as one would expect if the vaccine is doing it’s job). But, the authors also show that the individuals who were just young enough to be vaccinated are less likely to get dementia compared to the individuals who were slightly too old to be vaccinated, especially among women. A number of robustness tests finds no other sharp discontinuities in treatments or outcomes around the Sept 2, 1933 cut point.
The following graph summarizes. The top left panel shows that the cutoff led to big differences in vaccine uptake, the top right panel shows that there was a smaller but sharp decline in dementia in the vaccinated group. The bottom panel shows that was no discontinuity in a variety of other factors.
Read the whole thing.
I have had my shingles vaccine. As I have said before, vaccination is the gift of a superpower.
Are we evolving toward narrow banking?
That is the topic of my latest Bloomberg column, here is one excerpt:
…the narrow banking model has long been plagued by two major problems. First, there have never been enough safe assets to satisfy the demands of depositors. Second, excessive investment in government securities tends to crowd out private investment. The rise of narrow banking can in part be explained by the mitigation of both these issues.
Alas government debt has gone up! But those new safe assets do have some advantages. And:
The shifting of private funds into Treasury bills could be problematic if that meant credit to the private sector was shrinking. But the rise of private equity and other forms of non-bank finance has made that less of a concern. While private equity growth has slowed since the second half of 2022, it has been on a steady rise since the financial crisis.
Private equity allows many new ventures to be financed, and a run on private equity firms is difficult to pull off, since they are not funding themselves by issuing liquid demand deposits. A private equity venture has a much greater ability to withstand swings in the market. By one metric, private equity measures at almost $12 trillion in value as of mid-2022 — another sign of the US economy advancing in its tools of financial intermediation.
These are not pure market developments, as they are partly a response to the growing regulatory burden on banks, most of all capital requirements. Again, the current regulatory dynamic is not entirely stable. Unstable banks do create trouble, and in return higher legal and regulatory burdens are placed on them, thereby diminishing their profitability. The cycle continues, and implementing tougher regulations hastens the changes rather than halting them.
New York state fact of the day
Federal individual income tax revenue is down a lot since last summer but is still 15% higher in real terms than before the pandemic. New York’s personal income tax revenue is almost 17% lower.
Here is more from Justin Fox at Bloomberg.