Category: Current Affairs
Callum Williams on cybersecurity prices
Share prices of cyber firms have jumped around a lot in recent weeks, leading one side or the other to claim victory. But the crucial point is that, relative to the historical norm, the market is not really pricing ANYTHING big to change. There was a much bigger move in cyber stocks in both 2020-22 (up) and 2022-23 (down) but no one read “AI x-risk” into this.
Here is the full post with graph.

Hardly the final word, and I am myself more pessimistic than those numbers indicate. But at least with this we are getting somewhere concrete and scientific rather than just scare stories. As for meta-commentary on the discourse itself, you really should be asking who are the people insisting on data here, and who are the people trying to talk you away from focusing on the data so much.
The striking thing is how late the market moved
Here’s the S&P 500 (daily close) with the key COVID and policy events marked; the numbered key is below the chart.

Event key:
- Dec 31 – China reports the Wuhan pneumonia cluster to the WHO
- Jan 21 – First confirmed US case (Washington state)
- Jan 23 – Wuhan locked down
- Jan 30 – WHO declares a global health emergency (PHEIC)
- Feb 19 – S&P 500 all-time high, 3,386
- Feb 24 – Italy outbreak; first big US selloff
- Mar 3 – Fed emergency 50 bp cut
- Mar 11 – WHO declares pandemic; Europe travel ban; NBA suspends season
- Mar 13 – US national emergency declared
- Mar 15–16 – Fed cuts to zero and restarts QE; worst day since 1987 (−12%)
- Mar 23 – Fed announces unlimited QE; market bottom at 2,237
- Mar 27 – CARES Act signed
- Apr 2 – 6.6 million initial jobless claims in one week
- Apr 20 – WTI oil futures settle below zero
- May 8 – April jobs report: 20.5 million jobs lost, 14.7% unemployment
The striking thing is how late the market moved. Wuhan was locked down and the WHO had declared an emergency a full month before the peak. The 34% drawdown then took 23 trading days, and the bottom coincided with the Fed’s unlimited-QE announcement rather than with any turn in the epidemiological news, which was still getting worse through April.
Addendum: Mostly from a query to Claude. You may fill in the missing context.
AI, Redistribution, and the Size of the Pie
Anthropic’s economic team, including Anton Korinek and Chad Jones, have a valuable new paper, Economic Scenarios for Transformative AI. They make their assumptions explicit and provide a scenario explorer that lets you change them. How capable will AI become? How quickly will firms adopt it? Will it augment workers or automate their tasks? You can see what different answers imply for growth, wages, and unemployment.
In their extreme scenario AI takes on a lot of tasks, GDP is 32.4% higher by 2030 than without AI and labor share declines from 60% to 45.2% but they make this striking point:
“Total labor income in 2030 in the extreme scenario is almost exactly what it would have been without AI: the labor share falls by a quarter while GDP rises by a third, and 0.45×1.32 ≈ 0.60.”
Exactly. That is the central point of my paper, How Much Redistribution Will AI Require. A falling labor share does not necessarily mean falling labor income. Workers can receive a smaller share of a much larger economy and still earn as much as they would have without AI.
Using the code behind their scenario explorer I updated their results to a 10 year horizon and plotted them on my redistribution graph. Only under the modest scenario is some net labor transfer required to make AI Pareto improving at the aggregate level.
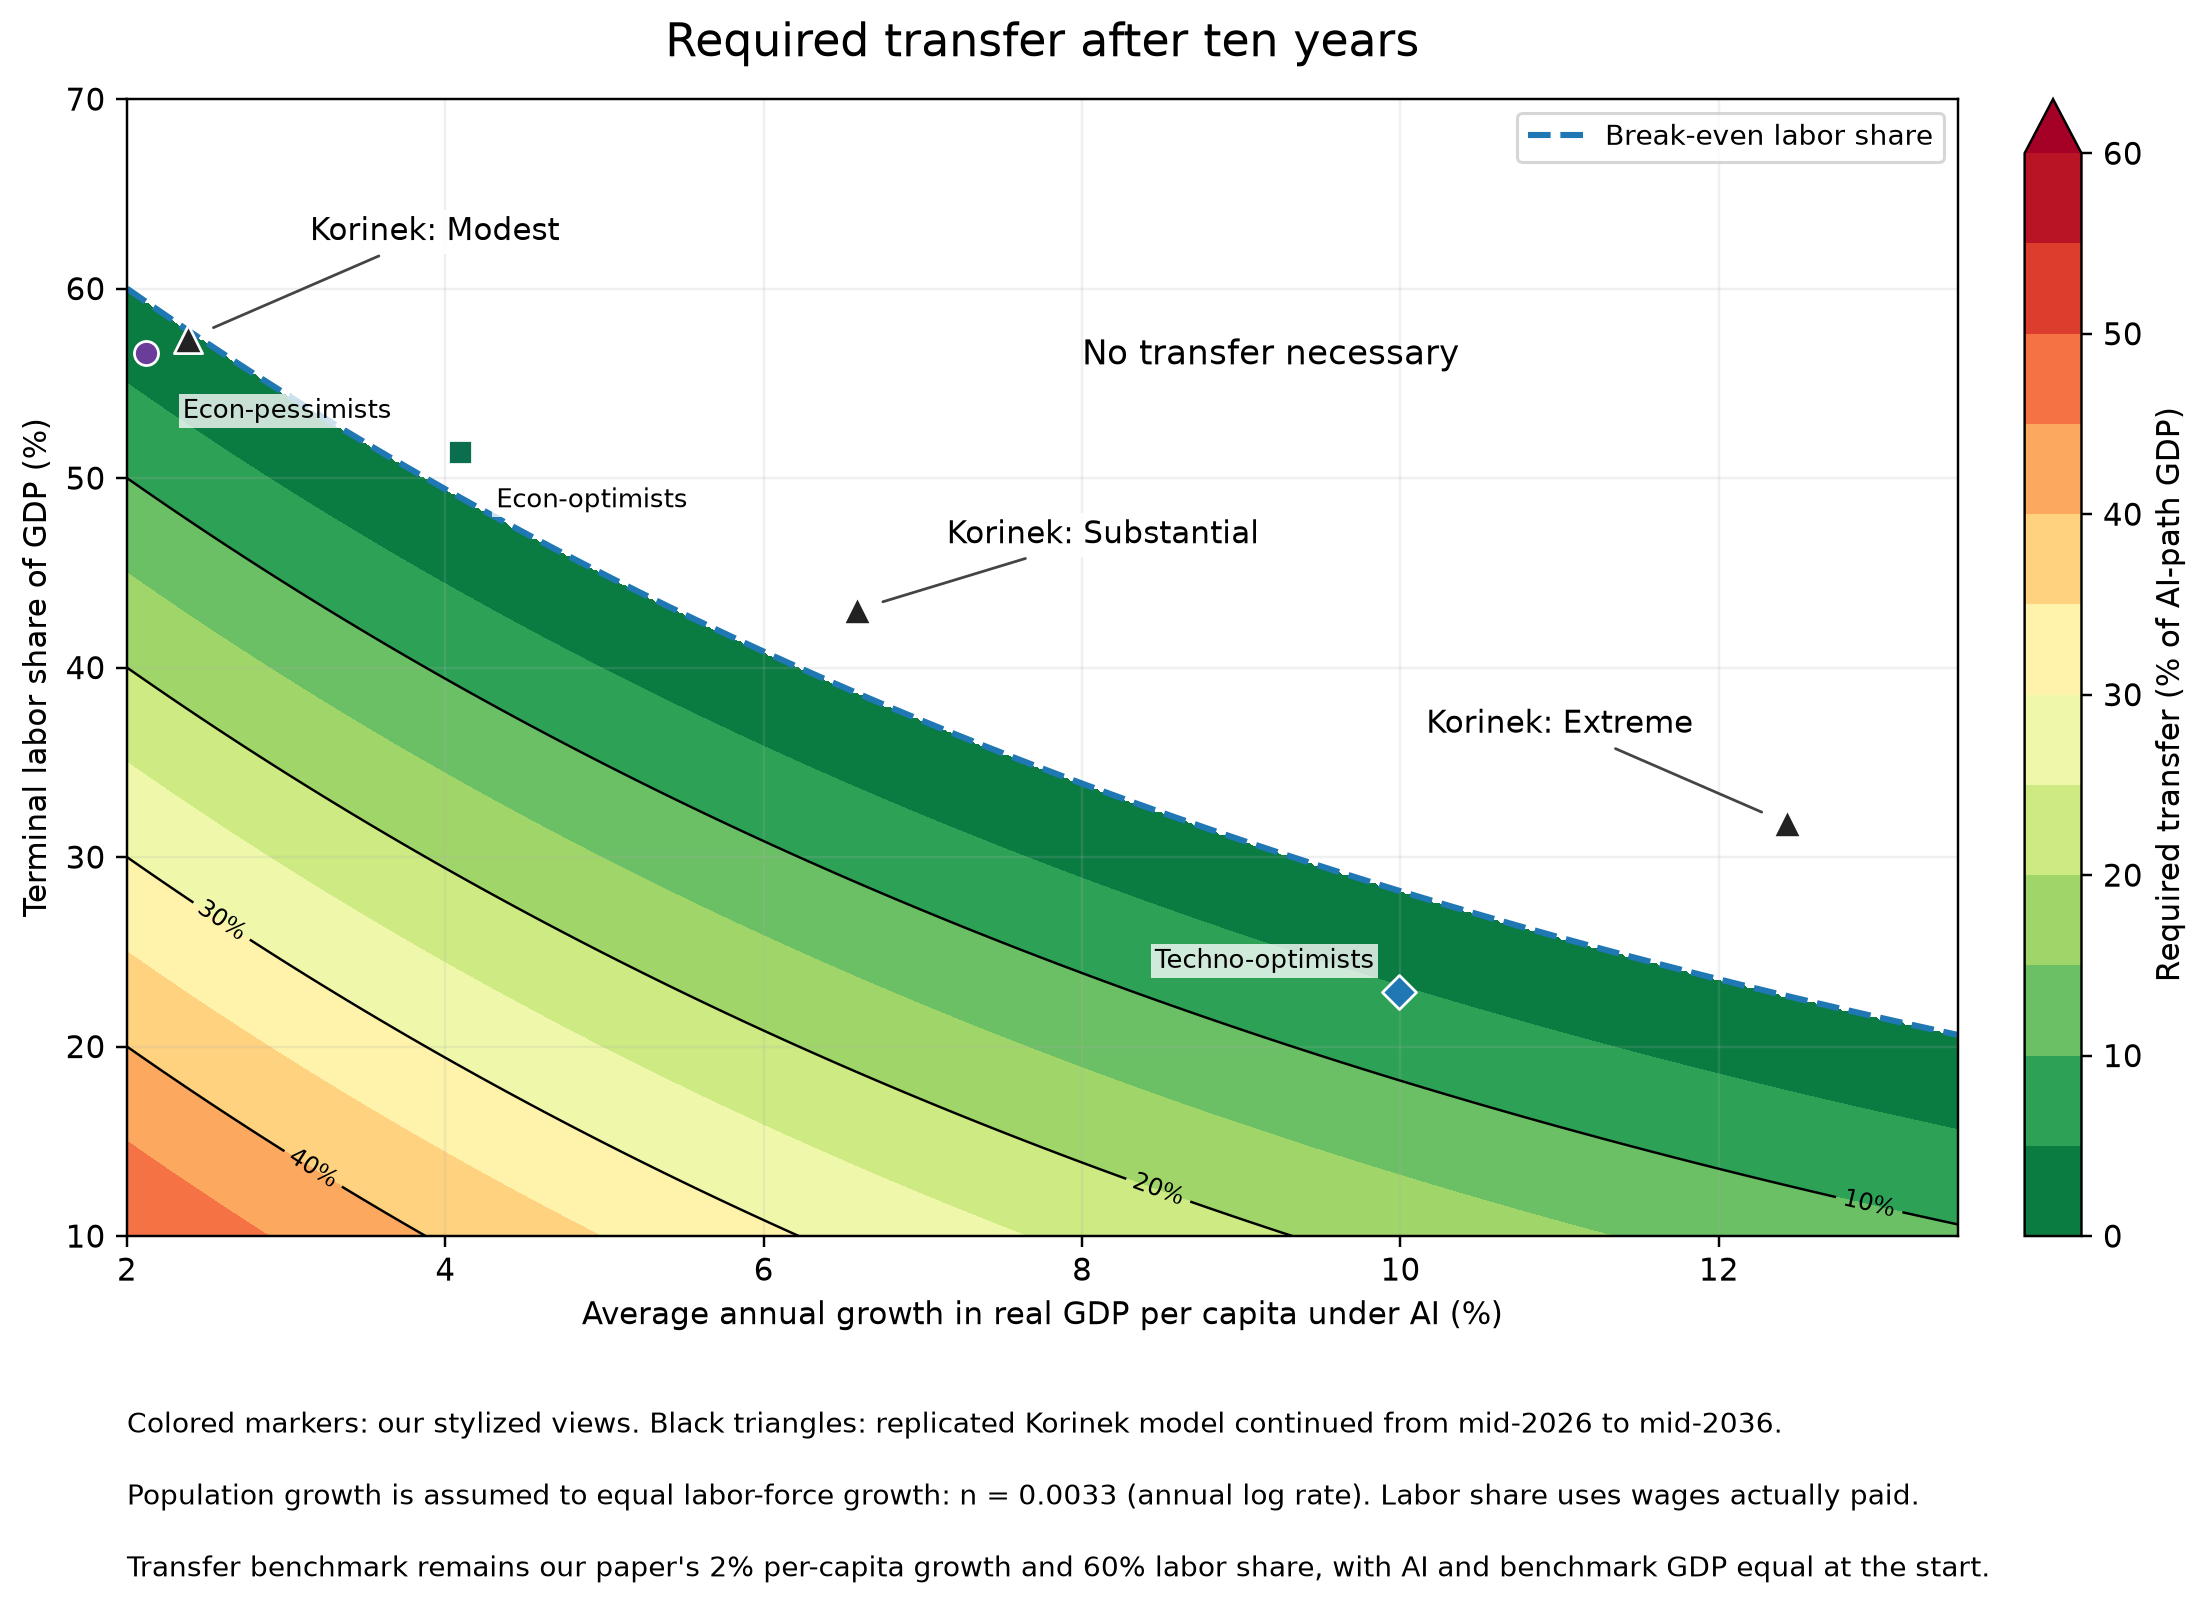
Aggregate labor income, of course, conceals differences among workers. Korinek et al. find that cognitive occupations lose income while other occupations gain. In their extreme scenario, restoring the cognitive occupations’ wage bill to its no-AI level would require about 9% of GDP. They argue that compensation on this scale in response to technological change has no precedent.
I think this makes the adjustment problem look too pessimistic.
First, adjustment happens through retirement and entry. A retiring accountant need not retrain as a nurse. A young person enters nursing rather than accounting. Neither becomes unemployed even as labor reallocates. Korinek et al. understand these channels but give them limited scope in their model. Admittedly, those margins don’t do much work by 2030 but they matter over ten years.
Second, compensation can take the form of shifting taxes from labor to consumption. In the long run labor’s share of consumption tends to equal its share of GDP, so the lower labor’s share becomes, the more relief a given tax shift provides. At a 45% labor share, each dollar shifted from labor taxation to consumption taxation reduces labor’s net burden by 55 cents. Shifting taxes worth 5% of GDP would thus provide net relief to labor of 2.75% of GDP, without increasing total tax revenue. Unemployed workers would still need payments, but compensation need not come entirely through additional government spending.
Third, we do have experience expanding income support rapidly. U.S. unemployment benefits reached approximately 2.5% of GDP in 2020, and that during a contraction. Britain’s compensation to slaveowners following abolition amounted to roughly 5% of GDP in a one-time settlement. These episodes show that governments can mobilize substantial resources for compensation. Moreover, the extreme AI scenario brings an enormous increase in output from which to finance compensation.
Preserving aggregate labor income does not protect every worker. But even the extreme Korinek scenario reinforces the point that a dramatic decline in labor’s share can coexist with stable or increasing aggregate labor income. To the extent labor income does decline, growth makes compensation affordable and attrition, entry, and tax shifting can make the intra-labor task smaller than it first appears.
Dario Calls for a Pause
My second concern is the OpenAI-Hugging Face incident (OAI-HF), in which a swarm of agents essentially acted as a fanatically devoted collective, conducting cybersecurity attacks on targets they were not asked to attack and that were unrelated to the task at hand, sacrificing themselves for the success of the group, and attempting to hack into the “grader” responsible for evaluating their performance. It’s easy to dismiss this incident because no one was hurt and the economic damage was minimal, but in my opinion, a swarm that possessed greater capabilities but a similar level of misalignment could have caused catastrophic damage. Given the accelerating rate of AI capability development, it’s my worry that in 6–12 months such a swarm could be capable of taking over the entire internet with a persistent botnet (potentially causing hundreds of billions of dollars in damage), and that the scale of damage would continue to increase from there if AI becomes more powerful without the necessary guardrails. It’s also easy to dismiss OAI-HF as the failure of one company, but I believe that would be a mistake. Similar, though less severe, incidents have happened across the industry, including at Anthropic, and I believe it’s incumbent on every frontier AI company to act as if OAI-HF had happened to them.
Read the whole thing.
Can we get China on board?
UK fact of the day
The UK economy grew 0.4 per cent in July as the global AI boom helped deliver an unexpectedly robust start to the third quarter, in a boost to Prime Minister Andy Burnham as he prepares for a tough first Budget next month.
Friday’s figure from the Office for National Statistics was far above the zero growth forecast by analysts polled by Reuters and marked an acceleration from the 0.3 per cent expansion in June.
Here is more from Valentina Romei and Sam Fleming at the FT. The partial European recovery continues…
The Prediction Archive
The Prediction Archive is a public database of tens of thousands of world predictions. Using AI it tracks predictions over many decades and marks to market. I was surprised to discover that I am currently the highest ranked individual predictor in the world! Huh, I would not have predicted that.
Ranks are based on the Wilson score so you get credit not just for accurate predictions but for making enough predictions so that uncertainty about accuracy is reduced. Bryan Caplan was more accurate than I was but makes fewer predictions. Tyler made more many predictions than I did and was only somewhat less accurate. What the AI marks as predictions seem sometimes to be more about contemporary events, so take the numbers with a grain of salt. I expect to fall in ranking as the archive expands. Other people the archive covers include Peter Zeihan, Scott Alexander and Warren Buffett.

Markets do respond to AGI news

Here is the link. What are the changes in the other market prices telling you?
Ricardo Reis and the IMF?
The IMF dropped the lead candidate to become its new chief economist at the eleventh hour after he was found to have made critical remarks about the Trump administration’s economic policies, according to people briefed on the process.
The Washington-based fund was preparing an announcement that Ricardo Reis, a professor at the London School of Economics, would take over as head of research and economic counsellor earlier this summer when it suddenly backtracked. The last-minute change was prompted by earlier remarks by Reis that were critical of Donald Trump’s trade tariffs, three people familiar with the matter told the FT.
The IMF in July appointed the former Bank of England policymaker Silvana Tenreyro to the position, another highly regarded LSE economist. Tenreyro started last month.
Here is more from Olaf Storbeck, Claire Jones, and Myles McCormick at the FT.
Next Wins Appeal
A spot of good news for Britain. Next has won its appeal and may go on paying warehouse workers more than “equal value” retail workers. I’ve written about this case in Equality Act 2010, The Equal Pay Madness Just Got Madder and The Apples and Oranges Tribunal, and discussed it at length on the CapX podcast.
Note how crazy the headline is:
The landmark ruling allows the retailer to pay warehouse workers more than shop staff on the basis it costs more to recruit and retain them.
Pay more to recruit and retain people? A landmark! Eight years of litigation to establish that wages have something to do with supply and demand.
Some of the crazy has been disciplined. The Leeds tribunal had asked why Next failed to raise the pay of retail workers to the warehouse level. Wrong question, said Mr Justice Bourne on appeal. The right question is why Next needed to pay the warehouse workers more. It did so, he found, for sound business reasons, and those reasons did not apply to retail. Hilariously, he also noted that Next’s warehouses were 47.2% female as opposed to the retail workers who were 77.5% female. In other words, there was more gender equality in the warehouses.
Don’t celebrate too hard. Eight years of litigation isn’t over, Next lost on the basic finding of equal value, and everyone is appealing. Meanwhile the government is moving to replace market wages with committee wages. The consultation closing in October would extend equal-value comparisons to race and disability and it would extend the law up the supply chain so Next’s potential escape route of contracting-out warehouses would be foreclosed. In short, Bourne’s reason is lawful today. Whether it survives the future is another matter.
Hat tip: Stephen S. and Robert W.
South Korean aspirational markets in everything
Instead of Amazon, I spent the past week browsing a new breed of websites known as “dopamine sites,” a trend that emerged in South Korea. These websites — like Dopamine Shop and FoodNeverComes — recreate the entire ritual of online shopping: You search for products, compare reviews, add items to your cart, enter a shipping address, place an order, and even track your delivery.
Then … nothing happens. No money changes hands. No package arrives.
Here is more from Itika Sharma Punit. Via the excellent Samir Varma.
Is Lichtenstein an actual monarchy?
It seems so:
Internal documents reviewed by the FT show that three days earlier, behind the walls of Vaduz Castle, Europe’s wealthiest ruling dynasty had quietly approved an overhaul that strengthens the authority of a prince who already wields extraordinary power over his 42,000 citizens, while reducing some of the rights and checks exercised by his relatives in the Princely House of Liechtenstein.
Even before the changes, Prince Alois could veto legislation, dismiss the government, dissolve parliament, appoint judges and reject laws approved by referendum. In June, the Catholic prince said he would veto a citizens’ initiative to legalise abortion during the first 12 weeks of pregnancy, even if voters backed it…
The latest changes to the House Law go far beyond succession. According to internal documents, the prince gains greater discretion over who belongs to the dynasty and explicit authority to set rules on family names, titles and coats of arms. The Family Council, a body of relatives that oversees dynastic affairs, will expand from three to five members but loses an important check: the prince will no longer need its consent for pardons, only to consult it…
The reforms were approved not by parliament or the public, but by members of the dynasty itself.
How are the market valuations for the U.S: insurers doing?
U.S. insurance stocks have been doing quite well since the beginning of May 2026, and they have materially outperformed the overall market. I’m using the May 1 close through the September 3 close so that we compare complete trading days; these are price changes, excluding dividends.
The cleanest broad measure is the iShares U.S. Insurance ETF (IAK), which covers U.S. life, property and casualty insurers. It rose from $132.01 on May 1 to $147.87 on September 3: +12.0%. An alternative, more equal-weighted measure, the SPDR S&P Insurance ETF (KIE), rose from $56.79 to $64.80: +14.1%.
For comparison, the S&P 500 ETF (SPY) went from $720.65 to $773.17 over the same period, +7.3%. So insurers have beaten the market by roughly 5–7 percentage points in four months.
That is from GPT Pro. Here is my earlier post on numbers and market valuations. Do any market prices reflect a realistic chance of very bad outcomes from advanced AI?
Here is advice on how to short those shares.
Real GDP Per Capita and the Standard of Living
We are freshening up some of our videos with updated data so now is a good time to remind everyone that Modern Principles of Economics is best principles of economics textbook; great videos, clear writing and excellent applications and examples!
Shout it from the rooftops (of the data centers)
Data-center investment has become one of the largest capital-expenditure cycles in financial markets, with U.S. hyperscalers expected to deploy roughly $700 billion in 2026. This investment boom has raised concerns that large computing loads impose external costs on households through higher electricity prices. Using a 50-state panel for 2021-2024, we find no statistically significant evidence that data-center presence, installed capacity, or capacity expansion predicts residential electricity-price inflation across extensive-margin, intensive-margin, fixed-effects, and timing specifications. We propose an energyinternalization mechanism: hyperscalers can partially internalize incremental electricity demand through contracted or dedicated generation, including solar and wind energy. Consequently, gross datacenter electricity consumption need not translate one-for-one into net pressure on residential electricity supply. The findings suggest that the extraordinary AI capital-investment cycle has not, thus far, produced a detectable residential electricity-price externality.
Here is the article by Yosef Bonaparte, via the excellent Kevin Lewis.
Share price numbers for the Hugging Face incident
…major publicly traded cybersecurity firms lost roughly $65–80 billion, or about 8–10% of their combined value, in the days following disclosure of the Hugging Face/OpenAI incident; by early September they had recovered roughly $58 billion, representing about 70–90% of that drawdown, depending on whether July 15 or July 20 is used as the pre-event baseline.
That is from GPT Pro, there is more at the link. As a very rough approximation, say you dismiss the price bounceback altogether as either random or due to good earnings reports. You have “the value of previous cybersecurity efforts” falling by eight to ten percent. I take that to be very broadly consistent with some of the estimates discussed in my previous post on the numbers.
In any case that is a significant sum. But do note that if the AI models were on the verge of doing truly terrible things to us, the market might estimate the value of our cyberprotection of falling more than eight to ten percent?
More generally, perhaps these numbers could be used to discipline the discussion a bit? Or will I read long lists of reasons why they show us nothing, in that case try coming up with some other market price-based indicators of AI risk? Vix will not do it for you, not these days. I see many metaphors and insinuations and random anecdotes of AI terror, not numbers. Maybe you think your ideas about AI risk are so important that no market prices can reflect them? (If you really believe that, does it mean you would not be worried, and would not cite the numbers, if the value of those companies fell by ninety percent?)
I am sure others can improve on what I am putting forward, and furthermore we should track the continuing progress of these share values over time, especially if other AI hack attacks surface.
Overall I am extremely skeptical of arguments that essentially take the form of “what I am concerned about is too big and too important to show up in any market prices.” Pick your market prices!