Wealth Shock
It’s surprising how often I agree with Dean Baker. In It’s the Housing Bubble, Not the ***** Credit Crunch he writes:
No one will lend me $1 billion, that’s how bad the credit crunch has gotten. There are probably reporters at major news outlets who would print that.
…they are still badly misinforming the public, first and foremost by attributing the economic downturn to a credit crunch.
This is truly incredible. Homeowners have lost more than $5 trillion in housing wealth. There is a very well established wealth effect whereby $1 of housing wealth is estimated as leading to 5 to 6 cents of annual consumption. This implies that the loss of wealth to date would cause consumption to fall by $250 billion to $300 billion annually (1.7 percent to 2.0 percent of GDP). If you add in the loss of around $6 trillion in stock wealth, with an estimated wealth effect of 3-4 cents on the dollar, then you get an additional decline of $180 billion to $240 billion in annual consumption (1.2 percent to 1.6 percent of GDP).
These are huge falls in consumption that would lead to a very serious recession, like the one we are seeing. This would be predicted even if all our banks were fully solvent and in top flight financial shape. Even the soundest bank does not make loans to borrowers who it does not think can pay the loans back (except during times of irrational exuberance).
Mankiw to the President-Elect
Greg Mankiw’s memo to the president-elect is excellent.
Unemployment During the Great Depression
Regarding unemployment during the Great Depression, Andrew Wilson writing at the WSJ recently said:
As late as 1938, after almost a decade of governmental “pump priming,” almost one out of five workers remained unemployed.
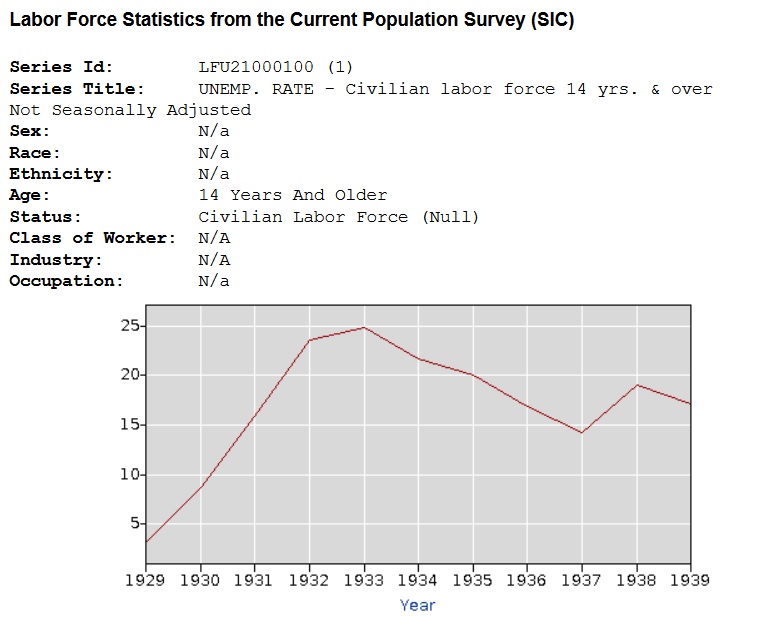 Historian Eric Rauchway says this is a lie, a lie spread by conservatives to besmirch the sainted FDR. Nonsense. In 1938 the unemployment rate was 19.1%, i.e. almost one out of five workers was unemployed, this is from the official Bureau of Census/Bureau of Labor Statistics data series for the 1930s. You can find the series in Historical Statistics of the United States here (big PDF) or here. The graph is at right. Rauchway knows this but wants to measure unemployment using an alternative series which shows a lower unemployment rate in 1938 (12.5%). Nothing wrong with that but there’s no reason to call people who use the official series liars.
So why are there multiple series on unemployment for the 1930s? The reason is that the current sampling method of estimation was not developed until 1940, thus unemployment rates prior to this time have to be estimated and this leads to some judgment calls. The primary judgment call is what do about people on work relief. The official series counts these people as unemployed.
Rauchway thinks that counting people on work-relief as unemployed is a right-wing plot. If so, it is a right-wing plot that exists to this day because people who are on workfare, the modern version of work relief, are also counted as unemployed. Now if Rauchway wants to lower all estimates of unemployment, including those under say George W. Bush, then at least that would be even-handed but lowering unemployment rates just under the Presidents you like hardly seems like fair play.
Moreover, it’s quite reasonable to count people on work-relief as unemployed. Notice that if we counted people on work-relief as employed then eliminating unemployment would be very easy – just require everyone on any kind of unemployment relief to lick stamps. Of course if we made this change, politicians would immediately conspire to hide as much unemployment as possible behind the fig leaf of workfare/work-relief.
There is a second reason we may not want to count people on work-relief as employed and that is if we are interested in the effect of the New Deal on the private economy. In other words, did the fiscal stimulus work to restore the economy and get people back to work? Well, we can’t answer that question using unemployment statistics if we count people on work-relief as employed. Notice that this was precisely the context of the WSJ quote.
One final thing that one could do is count people on work-relief as neither employed nor unemployed, i.e. not part of the labor force which is what we do for people in the military. Rauchway has data on this and it shows almost the same thing, nearly one in five unemployed, as the original series. (In this case, however, Rauchway counts nearly one in five unemployed as a win for the New Deal because the same series also shows higher unemployment earlier in the Great Depression.)
Any way you slice it there is no right-wing plot to raise unemployment rates during the New Deal and a historian should not go around calling people liars just because their judgment offends his wish-conclusions.
Hat tip to Mark Thoma.
I voted
First time, ever.
Addendum: By the way, it took me less than 3 minutes (I was surprised) and I got a free coffee at Starbucks. Not bad on instrumental or expressive grounds.
China Worry of the Day
China’s economic difficulties are very worrying because in China an economic slowdown is not just an economic problem but a political problem. Will the Chinese leadership turn to nationalism to divert attention from problems at home? Interesting times. and this time that is a curse.
China needs to encourage domestic consumption and with a trillion dollars in reserves they have the funds. Spending the rainy day fund would benefit the U.S. as well, stimulating our exports. It may already be too late, however, to shift smoothly from export to domestic consumption which means that mass capital depreciation will occur as capital investments in export industries turn out to be worth less than first appeared.
Voting Videos
Here’s a great little video from PBS (!) featuring Gordon Tullock on why he doesn’t vote and why you shouldn’t either. (Andrew Gelman and Noah Kaplan beg to differ in this article, but their theory applies only to altruists – not to Gordon!).
And from The Teaching Company here is a free video on voting theory, i.e. Arrow’s theorem, the Borda count and all that other good stuff.
Not from the Onion
From the Onion in 1993. Hat tip to Boing Boing. 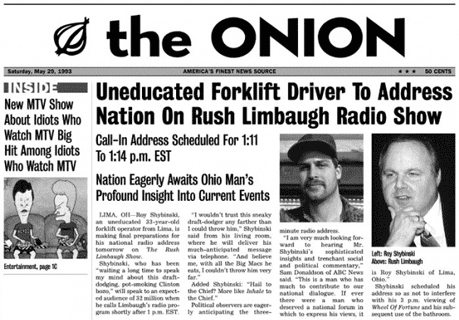
Pr(Sarah Palin=President)>Pr(John McCain=President)?
Here’s a frightening thought, today Sarah Palin may have a greater probability of becoming president than John McCain. The betting markets are currently giving McCain about a 16% chance of winning. If McCain wins then let’s assume that all things considered Palin has a 40% chance of becoming president (either if McCain dies in office or as his successor). If McCain loses many people suggest Palin could be a future Republican leader so let’s put her chances of becoming president in that scenario at 12%. Thus:
Pr(Sarah Palin=President) = .16*.4 + .84*.12 = 16.48 > 16% = Pr(John McCain = President).
Roubini on Structural Problems in the World Economy
In an interesting piece, Roubini points to structural problems in the world economy:
There is a huge excess capacity for the production
of manufactured goods in the global economy, as the massive, and
excessive, capital expenditure in China and Asia (Chinese real
investment is now close to 50% of gross domestic product) has created
an excess supply of goods that will remain unsold as global aggregate
demand falls.
Odd company or not, note that to the extent that Roubini is correct that past credit excesses have resulted in over-capacity (ala ABC) then our present problems go considerably beyond credit supply. Tyler is more optimistic than me on these matters.
Economics Videos from Marketplace
Paddy Hirsch the senior editor at American Public Media’s Marketplace radio program has produced a number of delightful videos on economic matters. The videos are witty, accessible but also well-informed – ideal for a senior high school or undergrad class and also a great place to crib notes if you want to explain to people what is going on when they ask you at parties (Yes, this does happen to me but admittedly I may go to different parties than you.) Here are a few of my favorites.
- The credit crisis as Antarctic expedition
- Getting naked in short selling
- Untangling credit default swaps
Thanks to Robby Thompson for the link.
MacGyver Science
Scientists have used a roll of Scotch tape to take X-rays – moreover, the effect may be the key to nuclear fusion. Seriously.
Addendum: This short slide show is better than the article at giving you the scoop on this finding.
Botox makes us happy
It’s long been known that simply smiling makes people feel better and making an angry face can make people feel more angry. Thus some cosmetic surgeons speculated:
People with Botox may be less vulnerable to the angry emotions of other people
because they themselves can’t make angry or unhappy faces as easily. And because
people with Botox can’t spread bad feelings to others via their expressions,
people without Botox may be happier too.
Amazingly, a recent experiment in the journal Cerebral Cortex supports this theory, although the abstract is a mouthful. You can read a summary here.
We show that, during imitation of angry facial expressions, reduced
feedback due to BTX treatment attenuates activation of the left
amygdala and its functional coupling with brain stem regions
implicated in autonomic manifestations of emotional states. These
findings demonstrate that facial feedback modulates neural activity
within central circuitries of emotion during intentional imitation of
facial expressions. Given that people tend to mimic the emotional
expressions of others, this could provide a potential physiological
basis for the social transfer of emotion.
Comment Delay
Comments seem to be showing up with a few minutes delay. Once you hit post, however, they should show up soon so just post once to avoid repeats.
Credit Demand and Credit Supply
We all now seem to agree that credit in the United States is actually growing during this "credit crunch," albeit at a slower rate than a year ago. Tyler and others argue that growing credit is actually a sign of the credit crunch. A credit crunch may show up "counterintuitively as a spike in borrowing" as firms draw on lines of credit. Contra Tyler this view is certainly "convenient" but I do agree with him that this view is not unfalsifiable.
To wit, let’s falsify it. The last time we had talk of a big credit crunch in the United States was during the 1990-1991 recession. Was credit growing during this time as firms drew on lines of credit? No. Most of the credit measures that today are growing were in 1990-1991 flat or shrinking. You can look at the pictures here or look at Table 1 of Ben Bernanke and Cara Lown’s well known paper (Google preview, JSTOR here). In 1990-1991, for example business loan growth was zero while today it is well above 10% (the same thing was true in 2001).
Peculiarly, Tyler argues that lack of credit is a leading cause of the crisis but a lagging indicator! As a result, he needs to resort to non-verified conjectures about credit options to support the credit crunch story. I have a simpler story, credit is a lagging indicator because it’s credit demand not supply that is the problem. My story also makes sense of the fact that credit usually lags on the upturn as well – a fact which option value has difficulty explaining.
One error that I believe Tyler is making is to assume that skepticism about the credit crunch implies that one must be downplaying the seriousness of current economic conditions. Not true. First, it’s quite possible to have a very serious recession with growing credit – we had this in 82, for example. Second, if Tyler is correct that the credit crunch is the primary cause of our current conditions then bank recapitalization should restore the economy to good working order. In contrast, I think the Paulson/Bernanke plan is in trouble because credit demand is shrinking faster than credit supply.
Addendum: In response to Tyler (below) and several people in the comments. Interest rates are not unusually high, certainly nowhere near as high as you would expect given a "credit crunch." In fact, interest rates on say 30 year mortgages are falling and are lower now than at the height of the boom and no higher than in 2002 near the beginning of the boom. I suspect that real interest rates are even lower than nominal rates suggest – inflation expectations anyone? I wish that more people would present their arguments with data and not with anecdotes.

Why vote?
Economists often argue that voting is a waste of time, since the chance that your vote will influence the election outcome is virtually nil. Maybe, but after watching this fear impels me to the polls.
Thanks for the Scrooge treatment go to loyal reader and GMU student Adam. If anyone knows of something similar for other candidates I will post an addendum.