The Long Term Perspective on the TED Spread
Here is the usual picture of the TED spread from Bloomberg.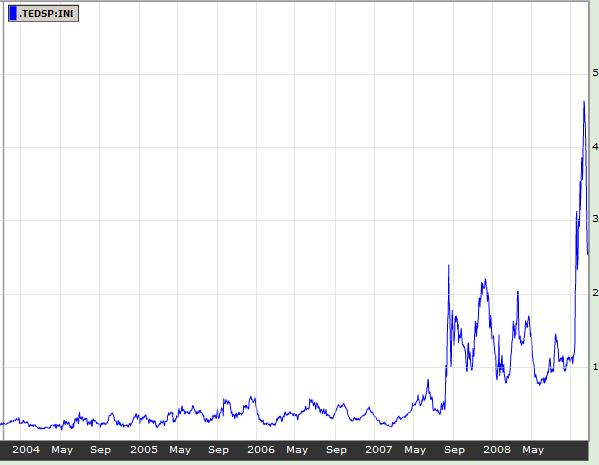
I was curious to see a longer-term picture so I collected data on the 3 month Treasury bill rate (TB3MS from the St. Louis Fed.) and the 3-month Eurodollar rate (EDM3 from the Fed.) Note that this is current up to September. Also this is slightly different from calculations elsewhere because it’s on a monthly basis, so some daily jumps are smoothed out, and sometimes a different LIBOR rate seems to be used for the ED rate but the different versions appear to correlate well. The advantage of using these measures is that you can get a much longer time series. Here it is (click to expand if unclear).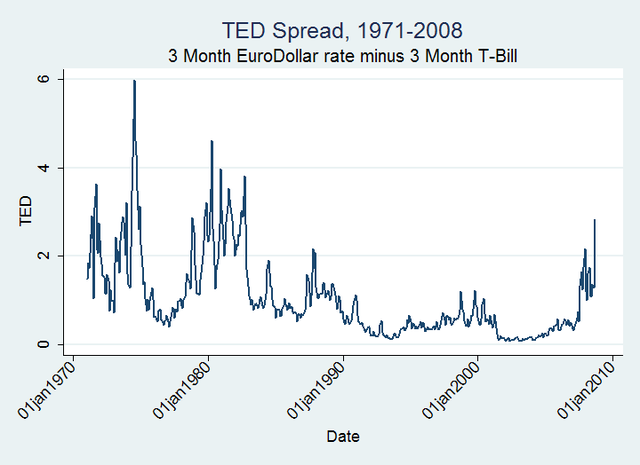
Some consensus
Mark Thoma gives us eight credit series from the St. Louis Fed. He is somewhat surprised to discover that all show positive growth over last year. I think most people who have heard talk of the credit crunch would also find this surprising. Let’s be clear, however, almost all the series also show declining growth. Let’s also be clear that the financial sector is a huge mess. Furthermore, we are in a recession that is likely to get worse especially because growth is declining around the world.
Four Myths of the Credit Crisis, Again
Contra Tyler (see below) neither the post from Free Exchange nor Mark Thoma’s comments "rebutting" the Minn. Fed study, Four Myths About the Financial Crisis of 2008, are compelling or well thought out. The Minn. Fed. presented data demonstrating that four widely reported claims about the credit crisis panic are myths – do either of the cited links claim that any of these myths are in fact true? No. Do either of the cited links present any data at all on the quantity of credit? No. Many people cite prices/rates/spreads as evidence for the crisis but what we ultimately care about is quantity not price. The Fed. piece had lots of data on the quantity of credit. Where is the rebuttal? Does Tyler cite any data at all or lay out his counter-claims? No.
Consider the major item that these links suggest as evidence of the crisis. Amazingly, it’s "an unusual spike in bank lending during the
crisis period." That’s right, an increase in bank lending is evidence of the crisis. The argument is that lack of credit elsewhere means that firms are drawing on their line of credit at banks. One problem with this is that Paul Krugman made this argument way back in February when I said that the lack of credit was being overblown. Thus the "crisis period" keeps changing. In February, the crisis was in February, now Thoma is saying it’s just the last few weeks. More fundamentally, the whole point of a line of credit is to keep credit flowing when one source dries up. A commentator at Thoma’s site nails this one:
Saying that credit availability is so ‘severely’ endangered that
borrowers are forced to utilize credit from banks isn’t the most
persuasive argument. What next?"Gasoline supplies had withered to the point that I was forced to fill up at Texaco instead of Chevron!"
Finally, Tyler and both of the cited pieces attack a stupid claim that obviously neither I nor the Minn. Fed. piece made, namely that the interventions by the Fed. have had no effect. Obviously, they have. But the story the media and the commentariat are reporting is that there is a credit crunch, credit is frozen, firms are starved for credit, we are on the verge of a Great Depression etc. The story has not been, ‘despite some problems in the banking sector quick action by the Federal Reserve and plenty of alternative non-bank credit has insured that credit continues to flow to nonfinancial firms.’
Sentence Fragment of the Day
…stochastic calculus porn…
That’s Arnold Kling on the state of modern macroeconomics.
Where is the Credit Crunch? III
Back in February I pointed out that despite all the talk of a credit crunch commercial and industrial loans were at an all-time high and increasing. In September I once again pointed to data showing that bank credit continued to be high (even if growth was slowing.) At that time I also discussed how bank loans were not the only source of funds for business investment and that many substitute bridges exist which transform and transmit savings into investment. I suggested that despite the panic the problems which exist in the financial industry may be relatively confined to that industry.
Three economists at the Federal Reserve Bank of Minneapolis, Chari, Christiano and Kehoe, now further support my analysis pointing to Four Myths about the Financial Crisis of 2008.
The myths
- Bank lending to nonfinancial corporations and individuals has declined sharply.
- Interbank lending is essentially nonexistent.
- Commercial paper issuance by nonfinancial corporations has declined sharply and rates have risen to unprecedented levels.
- Banks play a large role in channeling funds from savers to borrowers.
Each of these myths is refuted by widely available financial data from the Federal Reserve. It’s a short paper, read the whole thing.
None of this means that everything is cheery. Like most people I think that we are in a recession which is likely to get worse but we need to remind ourselves that recessions are normal. What is not normal is the current level of panic. The panic feels to me like an availability cascade.
Hat tip to Mike Moffatt.
Addendum: By the way, I wouldn’t be surprised if credit does start to go down but it will do so because of a fall in the demand for credit not primarily because of a fall in the supply, again an entirely normal aspect of all recessions.
Let me guess, The Heckman Institute?
More trouble at Chicago, this time among the econ faculty, regarding the Milton Friedman Institute. Sad.
Hat tip to Steve Levitt.
Brokers with Hands on Their Faces

Manipulation of Prediction Markets
As many people suspected someone was manipulating Intrade to boost John McCain’s stock price:
An internal investigation by the popular online market Intrade has revealed that an investor’s purchases prompted “unusual” price swings that boosted the prediction that Sen. John McCain will become president.
Over the past several weeks, the investor has pushed hundreds of thousands of dollars into one of Intrade’s predictive markets for the presidential election, the company said.
This is big news but not for the reasons that most people think. Although some manipulation is clearly possible in the short run, the manipulation was already suspected due to differences between Intrade and other prediction markets. As a result,
According to Intrade bulletin boards and market histories, smaller investors swept in to take advantage of what they saw as price discrepancies caused by the market shifts – quickly returning the Obama and McCain futures prices to their previous value.
This resulted in losses for the investor and profits for the small investors who followed the patterns to take maximum advantage.
This supports Robin Hanson’s and Ryan Oprea’s finding that manipulation can improve (!) prediction markets – the reason is that manipulation offers informed investors a free lunch. In a stock market, for example, when you buy (thinking the price will rise) someone else is selling (presumably thinking the price will fall) so if you do not have inside information you should not expect an above normal profit from your trade. But a manipulator sells and buys based on reasons other than expectations and so offers other investors a greater than normal return. The more manipulation, therefore, the greater the expected profit from betting according to rational expectations.
An even more important lesson is that prediction markets have truly arrived when people think they are worth manipulating. Notice that the manipulator probably doesn’t care about changing the market prediction per se. Instead, a manipulator willing to bet hundreds of thousands to change the prediction of a McCain win must think that the prediction will actually affect the outcome. And if people think prediction markets are this important then can decision markets be far behind?
Hat tip to Paul Krugman.
Best Sentence I Read Today
The Bush administration, having entered office as social conservatives, leaves
office as conservative socialists, proprietors of the most sudden large
expansion of the state’s role in the US economy since mobilisation for the
second world war.
Brad DeLong here.
The Playmate Indicator
The Environmental Security Hypothesis says that in tough times men will prefer women who are good at production, generally older, taller, heavier, less curvaceous women with less body fat. In good times, they will prefer women who are good at reproduction, generally younger, shorter, lighter, more curvaceous women. Pettijohn and and Jungeberg look at the characteristics of playboy playmates from 1960 to 2000 and find:
Consistent with Environmental Security Hypothesis predictions, when social and economic conditions were difficult, older, heavier, taller Playboy Playmates of the Year with larger waists, smaller eyes, larger waist-to-hip ratios, smaller bust-to-waist ratios, and smaller body mass index values were selected. These results suggest that environmental security may influence perceptions and preferences for women with certain body and facial features.
Econometricians who wish to investigate further may download the data here (yes really). The 2008 Playmate of the year, Jayde Nicole. does not seem to fit the hypothesis however.
The Singularity is Near
Telepathy has always been a sign of kookiness but synthetic telepathy heh that’s just around the corner.
The U.S. Army is developing a technology known as synthetic telepathy that would
allow someone to create email or voice mail and send it by thought alone. The
concept is based on reading electrical activity in the brain using an
electroencephalograph, or EEG…The idea of communicating by thought alone is not a new
one. In the 1960s, a researcher strapped an EEG to his head and, with some
training, could stop and start his brain’s alpha waves to compose Morse code
messages.
Here is a previous post in the series.
What is New Trade Theory?
Congratulations to Paul Krugman on his Nobel. Here is a primer on one of Krugman’s key contributions, New Trade Theory. Tyler has more links below.
Ricardo showed that every country (and every person) has a comparative advantage, a good or service that they can produce at a lower (opportunity) cost than any other country (or person). As a result, production is maximized when each country specializes in the good or service that they produce at lowest cost, that is in the good in which they have a comparative advantage. Since specialization in comparative advantage maximizes production, trade can make every country better off.
But what determines comparative advantage? In Ricardo it is the natural products of the soil, Portugal is good at producing wine and so England has a comparative advantage in cloth. Heckscher, Ohlin and Samuelson among others extended the model to show how factor proportions can determine comparative advantage – countries with a lot of labor relative to capital, for example, will tend to have a comparative advantage in labor intensive goods production.
Notice, however, that in the Ricardian model and its extensions the determinants of comparative advantage like geography and factor proportions lie outside of the model. New Trade Theory of which Paul Krugman can be said to be the founder, brings the determinants of comparative advantage into the model.
Consider the simplest model (based on Krugman 1979). In this model there are two countries. In each country, consumers have a preference for variety but there is a tradeoff between variety and cost, consumers want variety but since there are economies of scale – a firm’s unit costs fall as it produces more – more variety means higher prices. Preferences for variety push in the direction of more variety, economies of scale push in the direction of less. So suppose that without trade country 1 produces varieties A,B,C and country two produces varieties X,Y,Z. In every other respect the countries are identical so there are no traditional comparative advantage reasons for trade.
Nevertheless, if trade is possible it is welfare enhancing. With trade the scale of production can increase which reduces costs and prices. Notice, however, that something interesting happens. The number of world varieties will decrease even as the number of varieties available to each consumer increases. That is, with trade production will concentrate in say A,B,X,Y so each consumer has increased choice even as world variety declines.
Increasing variety for individuals even as world variety declines is a fundamental fact of globalization. In the context of culture, Tyler explains this very well in his book, Creative Destruction; when people in Beijing can eat at McDonald’s and people in American can eat at great Chinese restaurants the world looks increasingly similar even as each world resident experiences an increase in variety.
Thus, Krugman (1979) can be thought of as providing another reason why trade can be beneficial and a fundamental insight into globalization.
Moreover, Krugman (1979) began the task of bringing the reasons for comparative advantage within the model. In that paper, Krugman also hypothesizes briefly about what happens when we allow migration within the model. Recall, that in Heckscher-Ohlin-Samuelson factor proportions explain trade patterns but are themselves determined outside of the model. When people and capital can move, however, factor proportions are themselves something to be explained.
Krugman (1991) (JSTOR and here) brings increasing returns together with capital and labor migration and transport costs into one model. Krugman’s (1991) model has become a workhorse of economic geography and international trade. The model is too complex to explain here but the reasons for that complexity are clear to see – when everything becomes "endogenous" small initial differences can make for big effects. To minimize transport costs, for example, firms want to locate near consumers but consumers want to locate near work! Thus, there are multiple equilibria and at a tipping point the location decisions of a single firm or consumer can snowball into big effects. So Krugman has been a leader in introducing tipping points, network effects and thus the importance of history into international trade as well as into economics more generally.
A little good news
The DOT will begin to auction off landing slots at airports…well at LaGuardia, Newark and JFK anyway…and "up to 10%" of the slots…and with "mounting opposition." I did say this was a little good news didn’t I?
Houses for Sale! Houses for Sale!
Tyler and I have both suggested that increased immigration would help to increase the demand for housing and relieve some of the financial crisis. Writing in the WSJ Lee Ohanian concurs:
We should encourage the immigration of prime-age individuals. Beginning in 2007, net immigration fell to half of its level over the previous five years. Increasing immigration would increase the demand for housing and raise home prices. And note that the benefit would be immediate. Home prices — and the value of subprime obligations — would rise in anticipation of a higher population base. The U.S. particularly needs highly skilled workers. These workers not only would purchase homes, but would generate higher living standards for all Americans.
More generally, Ohanian warns that what made the Great Depression great was the misguided policies that Hoover and Roosevelt adopted to fight the depression. Ohanian has an ill-considered swipe at Obama on this score but the general point is valid and worth remembering as we rush onwards.
Caplan: 10/10 at 10 on 20/20
That’s Bryan Caplan appearing on 20/20 this Friday (10 pm EST). Who better to put this election in perspective?