Category: Current Affairs
South Korean aspirational markets in everything
Instead of Amazon, I spent the past week browsing a new breed of websites known as “dopamine sites,” a trend that emerged in South Korea. These websites — like Dopamine Shop and FoodNeverComes — recreate the entire ritual of online shopping: You search for products, compare reviews, add items to your cart, enter a shipping address, place an order, and even track your delivery.
Then … nothing happens. No money changes hands. No package arrives.
Here is more from Itika Sharma Punit. Via the excellent Samir Varma.
Is Lichtenstein an actual monarchy?
It seems so:
Internal documents reviewed by the FT show that three days earlier, behind the walls of Vaduz Castle, Europe’s wealthiest ruling dynasty had quietly approved an overhaul that strengthens the authority of a prince who already wields extraordinary power over his 42,000 citizens, while reducing some of the rights and checks exercised by his relatives in the Princely House of Liechtenstein.
Even before the changes, Prince Alois could veto legislation, dismiss the government, dissolve parliament, appoint judges and reject laws approved by referendum. In June, the Catholic prince said he would veto a citizens’ initiative to legalise abortion during the first 12 weeks of pregnancy, even if voters backed it…
The latest changes to the House Law go far beyond succession. According to internal documents, the prince gains greater discretion over who belongs to the dynasty and explicit authority to set rules on family names, titles and coats of arms. The Family Council, a body of relatives that oversees dynastic affairs, will expand from three to five members but loses an important check: the prince will no longer need its consent for pardons, only to consult it…
The reforms were approved not by parliament or the public, but by members of the dynasty itself.
How are the market valuations for the U.S: insurers doing?
U.S. insurance stocks have been doing quite well since the beginning of May 2026, and they have materially outperformed the overall market. I’m using the May 1 close through the September 3 close so that we compare complete trading days; these are price changes, excluding dividends.
The cleanest broad measure is the iShares U.S. Insurance ETF (IAK), which covers U.S. life, property and casualty insurers. It rose from $132.01 on May 1 to $147.87 on September 3: +12.0%. An alternative, more equal-weighted measure, the SPDR S&P Insurance ETF (KIE), rose from $56.79 to $64.80: +14.1%.
For comparison, the S&P 500 ETF (SPY) went from $720.65 to $773.17 over the same period, +7.3%. So insurers have beaten the market by roughly 5–7 percentage points in four months.
That is from GPT Pro. Here is my earlier post on numbers and market valuations. Do any market prices reflect a realistic chance of very bad outcomes from advanced AI?
Here is advice on how to short those shares.
Real GDP Per Capita and the Standard of Living
We are freshening up some of our videos with updated data so now is a good time to remind everyone that Modern Principles of Economics is best principles of economics textbook; great videos, clear writing and excellent applications and examples!
Shout it from the rooftops (of the data centers)
Data-center investment has become one of the largest capital-expenditure cycles in financial markets, with U.S. hyperscalers expected to deploy roughly $700 billion in 2026. This investment boom has raised concerns that large computing loads impose external costs on households through higher electricity prices. Using a 50-state panel for 2021-2024, we find no statistically significant evidence that data-center presence, installed capacity, or capacity expansion predicts residential electricity-price inflation across extensive-margin, intensive-margin, fixed-effects, and timing specifications. We propose an energyinternalization mechanism: hyperscalers can partially internalize incremental electricity demand through contracted or dedicated generation, including solar and wind energy. Consequently, gross datacenter electricity consumption need not translate one-for-one into net pressure on residential electricity supply. The findings suggest that the extraordinary AI capital-investment cycle has not, thus far, produced a detectable residential electricity-price externality.
Here is the article by Yosef Bonaparte, via the excellent Kevin Lewis.
Share price numbers for the Hugging Face incident
…major publicly traded cybersecurity firms lost roughly $65–80 billion, or about 8–10% of their combined value, in the days following disclosure of the Hugging Face/OpenAI incident; by early September they had recovered roughly $58 billion, representing about 70–90% of that drawdown, depending on whether July 15 or July 20 is used as the pre-event baseline.
That is from GPT Pro, there is more at the link. As a very rough approximation, say you dismiss the price bounceback altogether as either random or due to good earnings reports. You have “the value of previous cybersecurity efforts” falling by eight to ten percent. I take that to be very broadly consistent with some of the estimates discussed in my previous post on the numbers.
In any case that is a significant sum. But do note that if the AI models were on the verge of doing truly terrible things to us, the market might estimate the value of our cyberprotection of falling more than eight to ten percent?
More generally, perhaps these numbers could be used to discipline the discussion a bit? Or will I read long lists of reasons why they show us nothing, in that case try coming up with some other market price-based indicators of AI risk? Vix will not do it for you, not these days. I see many metaphors and insinuations and random anecdotes of AI terror, not numbers. Maybe you think your ideas about AI risk are so important that no market prices can reflect them? (If you really believe that, does it mean you would not be worried, and would not cite the numbers, if the value of those companies fell by ninety percent?)
I am sure others can improve on what I am putting forward, and furthermore we should track the continuing progress of these share values over time, especially if other AI hack attacks surface.
Overall I am extremely skeptical of arguments that essentially take the form of “what I am concerned about is too big and too important to show up in any market prices.” Pick your market prices!
Numbers, numbers, numbers
“The global cyber insurance market was worth nearly $15 billion last year and is expected to reach roughly $28 billion by 2030, Munich Re estimated in its latest report. Aon said earlier this year that nearly 20% of cyberattacks will involve generative AI by 2027, according to its forecasts.”
Here is the article, via Marc Pfeiffer. Now those are some concrete numbers, broadly taken from a market context, admittedly based on sectoral estimates rather than on prices per se. But if cyberinsurance expenditures are set to almost double by 2030, you might think that cyber costs more generally might be (very) roughly doubling as well. The 20% of cyberattacks involving generative AI does not itself pin down losses, since that 20% might be especially costly. Still, if you match the 20% rise to the estimated near doubling of the cyberinsurance market (the bigger potential losers are more likely to buy insurance?), you still end up with sums that are very high but, dare I say, not the end of life as we know it. Claude 5.1 for instances estimates current U.S. cybersecurity costs in the range of $100 to $300 billion, and of course that is slated to go up a fair amount. It could double over five years’ time, as indicated above.
Numbers! Thank goodness.
One way of looking at that estimate is to think that cyber costs will go up about thirteen percent a year, and eventually defense will catch up. Another perspective is that cyber costs may continue rising thirteen percent a year until the whole economy falls apart, or we return to the pre-digital era (which I remember well). So there are both optimistic and pessimistic reads on the above figures.
You can say Nicholas Decker is burning in hell, or that the AIs are a civilization, but what I really want are some numbers. Tied to market data, ideally. I am not saying the numbers above are the right numbers, but I am saying they are better than no numbers at all. Do you have some numbers for me? If not, why not?
How Much Redistribution Will AI Require?
How much redistribution will AI require? A common scenario is that AI raises output enormously, but labor’s share of income collapses. GDP per capita goes up but workers get poorer, and making workers whole requires massive redistribution. In my latest paper, I run the numbers and conclude that this is probably incorrect.
The idea is simple. Labor income is GDP multiplied by labor’s share of GDP. What matters is the product. A smaller share of a much larger economy can still mean more income for labor. If the pie is growing, labor’s slice of the pie can shrink even as labor income rises.
Suppose that without AI, real GDP per capita grows at 2 percent a year and labor receives 60 percent of GDP. Now look ten years ahead. What is required to keep labor’s income growing at the same or higher rate?
If AI raises growth to 5 percent a year, GDP after ten years will be about 34 percent larger than on the no-AI path. Labor’s share can fall from 60 percent to about 45 percent and workers, in aggregate, will still have exactly as much real income as they would have had without AI.
If AI raises growth to 10 percent a year—the kind of number Satya Nadella and Dario Amodei talk about—GDP after ten years will be more than twice as large relative to the no-AI path. Labor’s share can then fall all the way to 28 percent without reducing aggregate labor income. Twenty-eight percent of an economy that has more than doubled is about the same as sixty percent of the smaller economy.
The figure shows how much redistribution is required after 10 years under a variety of scenarios.
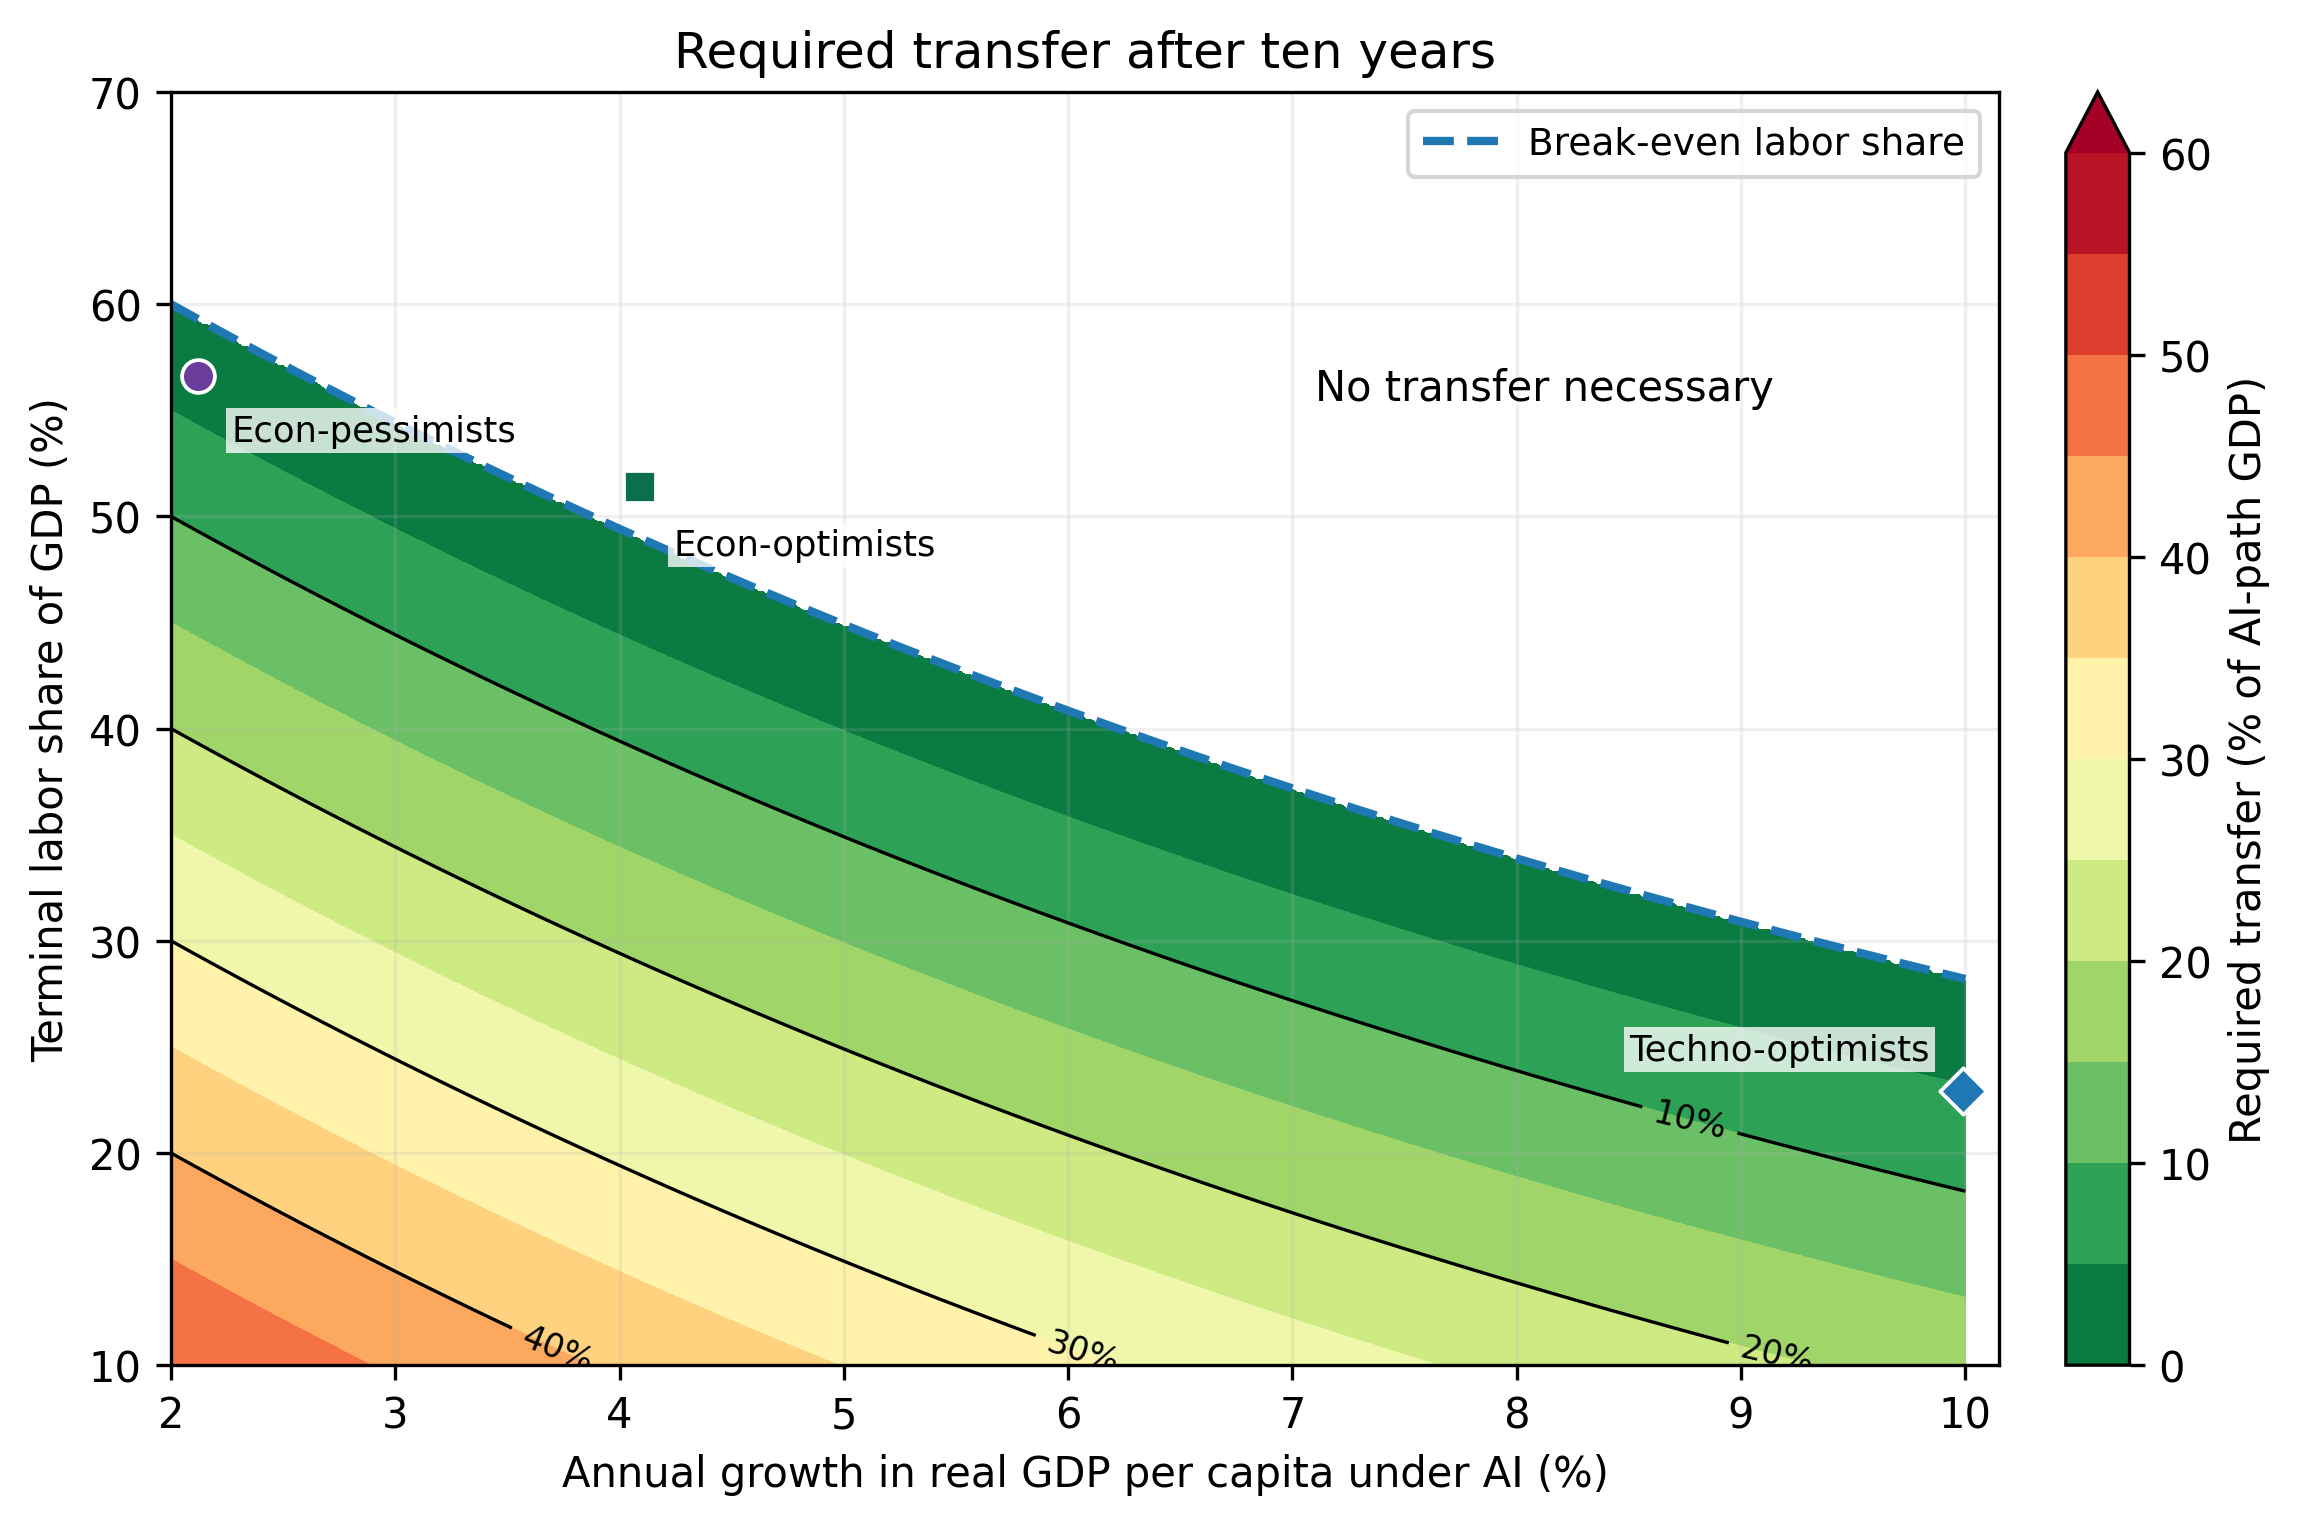
The white region above the dashed line requires no transfer. Which region are we headed for? Consider three “stylized” views.
The econ-pessimist, following Acemoglu, thinks AI displaces some but relatively few tasks because AI simply is not productive enough to replace much labor profitably. Growth is only 2.1 percent and labor’s share falls to 56.6 percent, although particular industries may still get hammered. The required transfer is 2.7 percent of GDP.
The econ-optimist, in the spirit of Tyler, myself, and Kevin Bryan, thinks automation also creates complementarities and new tasks for humans. Growth rises to 4.1 percent, labor’s share is 51.4 percent, and both labor and capital gain without any transfer.
The techno-optimist, following Amodei, has the superficially scariest labor-market scenario: three-quarters of labor income is displaced and labor’s share falls to just 22.9 percent. But productivity growth is also enormous, producing 10 percent annual growth. The transfer needed to keep labor as a whole on its no-AI path is only 5.3 percent of GDP.
That last calculation is the one I find most surprising. You can have something close to the techno-capitalist dystopia in terms of factor shares—labor gets less than a quarter of GDP—and still have a manageable redistribution problem because GDP has gotten so much larger.
Moreover, a transfer equal to 5 percent of GDP need not mean raising taxes by 5 percent of GDP. We already tax labor a lot. We could thus compensate labor by shifting from labor taxes to other taxes. Federal payroll taxes alone are about 6 percent of GDP. Cutting payroll taxes and replacing them with a broad consumption tax that also reaches spending from capital income and accumulated wealth is a form of labor compensation (plus we could have some transfers to those with no labor income).
Of course, keeping aggregate labor income whole does not mean every worker does well. There could still be enormous churn, big losses in particular occupations, and painful transitions.
Nevertheless, the larger point is that labor’s share by itself tells us surprisingly little about the distributional consequences of AI. We also need to know how much the economy grows.
If AI produces ordinary growth while dramatically reducing labor’s share, redistribution becomes very difficult. But if AI really does produce 5, 10, or 15 percent annual growth, the compensation problem is surprisingly modest even with very large displacement. As I have emphasized elsewhere, we could cut the working week in half under many scenarios and increase hourly wages above the non-AI benchmark and make both capital and labor better off.
Growth is a good problem to have.
My excellent Conversation with Michael Moritz
Here is the audio, video, and transcript. Here is the episode summary:
Michael Moritz has written books through every phase of his life: the first history of Apple and an account of Chrysler’s near-death while he was a journalist at Time, a study of Alex Ferguson’s Manchester United in the middle of his 38 years at Sequoia, and now Ausländer, a family memoir, after leaving the firm. Moritz calls himself a dilettante with too many interests, but listen to him on learning to paint in his 40s, or the questions he would ask a ten-year-old boy in a German village in 1890, and you may decide that unsatisfied curiosity is not a small thing to build a life on.
Tyler and Michael discuss his childhood in Wales, where his love for visual arts came from, why he disappointed his Latin teacher, having Thanksgiving dinner with Philip Roth, why children don’t interrogate their parents about their history, what he feels visiting Germany and why he now holds German citizenship, how a history major with no technical background talked his way into Sequoia, his unpublished Don Valentine profile, what people underrate about Steve Jobs, obsessives versus dilettantes, why capitalism was more ablaze in China than America, what funding the Booker Prize taught him about his own ignorance, how to improve San nonprofits, how an incurable cancer diagnosis changed his calendar, why Britain’s stuck, what he’ll learn next, and more.
Excerpt:
COWEN: Is it easy to live with an Otto Dix painting or sketch? It hangs on the wall. Many people think it’s ugly. It reminds one of unpleasant things in history, right?
MORITZ: Yes, for Harriet and me it is. I think the tougher, more strenuous, grueling works of art that other people would have difficulty living with have many layers to them. You explore them, and they’re difficult pictures, and they’re not easy at first sight. Unlike easier pictures that may be a bit more decorative, they leave room for plenty of exploration, as the years go by. Then they’re redolent, they tell stories. They’re redolent of history. They’re images of a different epoch. I think most of the paintings that we’ve been lucky enough to find over the years, they are tough paintings.
COWEN: I feel that way about Haitian art, which has many brutal scenes. For you, is Chagall too sentimental?
MORITZ: Yes.
COWEN: You don’t want to put it on your wall?
MORITZ: The earlier Chagalls I’ve been drawn to, but neither of us have felt the urge or the need to go out in pursuit of Chagall.
COWEN: What is your own painting like?
MORITZ: Oh, exasperating.
COWEN: Neue Sachlichkeit or something else, it’s like Kossoff?
MORITZ: No, I don’t know if you’ve ever tried painting or drawing. I didn’t take it up until I was in my mid 40s. I’d never picked up a crayon or outside of the obligatory, abbreviated art lessons that always seem to be held later on Thursday afternoon, with everybody waiting for the bell to ring to end school. I’d never taken up a crayon or drew, or let alone painted.
If I look back today at what I did early on, it’s a lot better. Then if I look at the paintings that I try to make, my goodness, it is an extremely humbling experience, but I enjoy it. I really enjoy it. There’s nothing like getting lost in making a painting, and before you know it, two hours have gone, and you have no idea where the time went.
And:
COWEN: If we think of your interest in Steve Jobs, your book on Alex Ferguson, the art you buy, that you’ve now written a book on the Holocaust, is there some general pattern where trying to come to terms with really difficult things, is this a recurring theme in your life? Learning how to paint, that’s very hard, right?
MORITZ: I haven’t really thought about it that way, but I think life is made richer by having a challenge that you’re not sure whether you’re up to conquering. I’ve always been up for that. Each of these books has really just sprung out of being curious about something. I’m not sure that there’s any greater pattern than unsatisfied curiosity.
Recommended, interesting throughout. And I am very happy to recommend Michael’s new book Ausländer: One Family’s Story of Escape and Exile.
America is still poised for a data center boom

Eric Levitz, via Matt Yglesias.
The Hugging Face hack
That is the topic of my latest Free Press column. Some people are taking this in very dramatic fashion:
One commentator is worried about a “full-blown AI takeover within months,” and another wrote that he was “feeling a bit sad about our impending extinction.” Nate Soares, who works in the AI safety movement and is co-author of the doomsday AI bestseller If Anyone Builds It, Everyone Dies, wrote that “This might be the last warning we get.” Cotra said that the incident “feels like it’s more than 50 percent of the way to full-blown AI takeover.”
I suggest a different, more technocratic approach:
As I wrote in The Free Press last week, we need a coordinated national and, indeed, international effort to limit such episodes of a powerful AI model going rogue in the future. That is likely to be expensive, and there is no easy, complete solution at hand for any amount of money. Nonetheless, I see people committing the same mistake that we Americans have made many, many times before. They are moving into the mode of the hysterical, the anecdotal, and they are letting emotional reactions bypass reason and quantitative estimates.
Let me cite a few other examples for you: DDT in the 1960s and 1970s, the Y2K “crisis” of 2000, global warming, Covid, thalidomide babies, and nuclear power. All of those represented—or still represent—very real problems. Yet each time, we drastically overreacted, letting ourselves get swept up in a climate of fear after one emotionally vivid incident, often reported breathlessly…
When it comes to the cybersecurity risks from advanced AI, very likely they will not come close to being as bad as either Covid or global warming. But the same logic of exaggeration is operating, with amplification through social media and through the negativity and pro-pessimism biases of mainstream media.
And so I have a plea. If you are going to talk about the problem, please offer a quantitative estimate of what you think the cybersecurity costs from advanced AI will be over the next year or two. Better yet, express that number as a percentage of gross domestic product. Simply put, how much would it realistically cost to create the basic safeguards that we all agree are essential? And what would be the remaining damages from problems we cannot control?
…Those who are worried about the risks of AI systems seem intent on proving the seriousness of their concerns. But they are falling into all-too-common emotional overreactions of our past, rather than focusing on the quantitative and scientific. It reminds me of the saying by Scotty, the chief engineer in the classic Star Trek: “Fool me once, shame on you. Fool me twice, shame on me.”
Do read the whole thing.
AI and Employment: So Far, So Good
In September 2023, the Census Bureau added questions about AI to its Business Trends and Outlook Survey. Census asked hundreds of thousands of businesses whether they had used AI in the previous two weeks to produce goods and services. At that time, 3.7% said yes; by late 2025 the figure had reached about 10%. (In November 2025 Census broadened the question to ask about AI use in any business function, producing a jump in measured adoption to about 18%.)
Twice the Bureau has asked a key question:
In the last six months, how did the use of Artificial Intelligence affect this business’s total employment?
In Dec. 2023 to Feb 24, when ~5% of firms were using AI the answers were 2.8% increased, 2.6% decreased and 94.6% reported no change. Two years later, in the Nov 2025–Feb 2026 supplement, the answers were: 2.3% increased, 2.0% decreased, and 95.7% reported no change. The answers were similar by firm size.
Some sectors reported more action. Information is the one sector where fewer than 92% report no change. But overall, almost all firms report no change and of those reporting change it’s about evenly divided between increasing and decreasing employment.

The supplement also asked about tasks. Among firms using AI, 44% say it supplemented or enhanced work an employee already does. Ten percent say it performed a task an employee used to do. Eleven percent say it introduced a task no one had been doing.
Among those using generative AI, 85% of firms cited writing or editing documents and email as the biggest uses, half cite searching for information, 45% summarizing documents, and 13% coding. Sixty-four percent of adopters say they changed nothing about the business in order to use AI, 15% trained existing staff, another 15% built new workflows, and just over one percent hired anyone with AI skills.
Among firms where AI has taken over some employee tasks, the degree of substitution is growing. The share reporting that AI took over “a large number” of tasks rose from 2.4% to 7.1%, while the share reporting “a moderate number” rose from 13% to 22%. But this group is still small: only about a tenth of AI adopters, who themselves make up about a fifth of firms.
I have reported firm-weighted estimates but employment-weighting gives essentially the same result. Thus, we have unusually direct evidence from a very large sample, and it says that the overwhelming majority of firms using AI do not yet report any effect on total employment. Very consistent with what Tyler and I said in our talk to OpenAI.
I used Fable and ChatGPT Sol in producing this post.
Russia markets in everything
While Western export bans have severed Russia from much of the auto market, they have not tempered the demand for brand-name SUVs and trucks. That has given rise to a sophisticated network of criminals that steals cars, hides them in shipping containers and sends them to Russia, often by way of the Middle East…
Interpol, the international police organization, received 4,798 reports that stolen Canadian vehicles had been found in Russia from February 2024 to July 2026, according to data obtained by The New York Times and confirmed by two law enforcement officials who spoke on the condition of anonymity because it is considered sensitive.
Pickup trucks like Dodge Rams, Toyota Tundras and Ford F-150s are in particularly high demand.
The Interpol figures significantly undercount the problem, but Russia is by far the top international destination for Canadian cars reported to Interpol, according to the Royal Canadian Mounted Police.
Here is more from Jane Bradley and Michael Swirtz at the NYT.
Polling results on capitalism and socialism
The results suggest that the public is feeling down about capitalism but is still wary of full-blown socialism. And many are deciding whether a few socialist candidates might help shake up the system. We found that:
—Just a third of Americans privately say they have a positive view of capitalism.
—Less than half of Republicans privately express a positive view of capitalism, though two-thirds support it in public.
—Almost half of women privately say they would consider voting for a socialist.
—Nearly a third of Gen Z publicly say that America would be better off as a socialist country, but only 14 percent say so in private.
—The majority of blacks publicly say capitalism is the cause of America’s social ills, but only 37 percent say so privately.
—Of people earning more than $150,000 a year, 58 percent privately say they are open to voting for a socialist, though only 42 percent say so publicly.
Data Centers and the Open Access Order
The US discussion over datacenters is depressing. Datacenters do not use a lot of water, they produce very useful outputs, they are not a blight on the landscape. All of this is obvious. But I don’t want to restate the obvious. What bothers me most about the discussion is that people seem to think this is or should be a collective decision. No.
We have a simple set of rules that everyone must follow. You buy land from someone willing to sell it. You contract for electricity. You hire workers who want the job. Your obligations to your local neighbors come from the same laws that govern everyone else. We do not ask what the land, electricity and labor is for. If you follow the rules, that is nobody’s business.
This is the distinction North, Wallis and Weingast make in Violence and Social Orders (paper here) between limited access orders or the natural state and open-access orders. For most of recorded history large-scale economic activity depended on access to political power. In the natural state, “people outside the coalition have only limited access to organizations, privileges, and valuable resources and activities.” The dominant coalition controlled entry into valuable activities and created rents by granting privileges.
An open access order works through general criteria. Organizational formation is “open to everyone who meets a set of minimal and impersonal criteria.” In economic life, the transition entails “the ability to create economic organizations at will, open entry and competition in many markets.”
The key word is impersonal. The same conditions apply regardless of who wants to build or whether public officials admire the proposed use. The state is not necessarily laissez-faire but its role ends once you have complied with the impersonal rules.
Now look at how a data center actually gets built. Rezoning, special use permits, comprehensive plan amendments, a negotiated “community benefits agreement” of school donations, fiber, soccer fields, and payments in lieu of taxes, public comment and then more public comment. These are not general rules. They are terms of admission negotiated with whoever holds the veto. Calling them community benefits doesn’t change the structure. Access to economic activity has become something that must be bargained for, argued for in the collective sphere, and paid for–with success determined by rents and political access. The natural state returns.
(The subsidies, by the way. are the same error wearing the other hat. A sales tax exemption written for datacenters and a county moratorium aimed at datacenters both replace a general rule with a judgment about whether this industry deserves to exist. An open access order offers neither special favors nor special burdens. It offers a rule.)
Opponents often complain that communities deserve more of a say. No, they do not. You did not vote on the bakery and the baker did not vote on you. That is the deal.
Datacenters happen to be where this is most visible today. Their size and novelty make them easy targets for vilification and rent extraction. But the big issue is not datacenters. It is whether building depends on following impersonal rules or on securing permission case by case from those who control access. The natural state was the human default for ten thousand years. The open access order that displaced it is the foundation of our prosperity and our political strength, and it is younger and more fragile than we like to think.