Category: Economics
Capital Gains Can Be Labor Income
Zwick and Zidar argue that a substantial share of the decline in labor share can be accounted for by changing forms of pay, including pass-throughs and equtiy compensation. In particular, if an employee is paid in stock and that stock increases in value then the tax rules tend to count some of that as capital income (depending on when the capital gains occur) rather than as labor income. Zwick and Zidar point us to Human Capitalists for the details:
Human capitalists are corporate employees who receive significant equity-based compensation such as equity grants and stock options. These employees are partial owners of US firms, and in return for their human capital input, human capitalists accrue a share of firm profits through firm dividends and capital gains in addition to earning wages. We document the stylized facts describing the evolution of human capitalists’ income over time and across industries within the US manufacturing sector.1 Human capitalists have become an increasingly important class of corporate income earners. Due to measurement challenges, prior work has underestimated the importance of equity pay below the C-suite. Correctly measuring the total income of human capitalists substantially alters conclusions about changes in factor shares and technological complementarity.
Equity-based compensation represents 36% of compensation to human capitalists from 2010 to 2019 and constitutes a 7% share of value added in the manufacturing sector in 2019. Correctly accounting for the total income earned by high-skilled workers has a substantial effect on measured changes in labor shares over the modern era. The addition of equity pay to cash wages reduces the decline implied by the wage-only income share of value added in manufacturing since the 1980s by 32%. Without including equity pay, high-skilled labor’s share decreased from 17% in the 1980s to 11% in the most recent decade. The inclusion of equity-based compensation almost eliminates this decline. The high-skilled share of total labor income increases from one-third at the beginning of the 1960s to two-thirds in the 2010s when equity-based compensation is included.
See also my previous post The Labor Share Fell. So What?
Do falling birth rates boost per capita income?
The secular decline in birth rates across the globe over the past seven decades has slowed population growth, raised average ages, and reshaped labor markets and the macroeconomy. Contrary to the widespread expectation that these trends hamper economic growth, we find lower birth rates are associated with higher growth in GDP per working-age adult across countries and higher wage growth across US commuting zones, with no negative impact on aggregate GDP or earnings. These patterns are not explained by educational upgrading, rising female labor force participation, the declining importance of agriculture, or neoclassical-Solow mechanisms. We argue that they reflect the endogenous, labor-saving response of technology to the scarcity of younger workers. Consistent with this interpretation, countries and regions with lower birth rates exhibit more labor-saving patents and growing high-tech activity. There is also higher TFP growth across countries and industries. Exploiting cross-country variation in WWII military and civilian deaths, we find that declines in younger population, rather than population size per se, drive our results.
Here is the full paper by Acemoglu, Autor, Beirne, and Scott. Via Philip Heimburger.
How Britain Became as Poor as Mississippi
How Britain Became as Poor as Mississippi is a good piece in the Atlantic by Idrees Kahloon filled with colorful anecdotes of a nation in decline:
The health service now has to spend more money settling maternity-malpractice claims than it does on actually providing maternity care. Many Brits can neither obtain an appointment with a publicly funded dentist nor afford a private one; in a 2023 survey, one in 10 reported doing DIY dental work, in extreme cases extracting their own teeth or gluing broken crowns back together.
Incomes can be shockingly low: Junior doctors recently went on strike for the 15th time in three years over their salaries, which start at just £38,800; the median salary for British civil servants is £35,680. In April, amid the Iran conflict, the Daily Mail pounced on Prime Minister Keir Starmer for vacationing in Valencia, Spain, at what the tabloid described as a luxury hotel, costing £200 a night.
Americans are likely to come away a bit smug, especially as Independence Day approaches and Europeans are enjoying our giant stadiums and central air conditioning. Look deeper, however, and Britain’s story becomes more uncomfortable. Does this sound familiar?
Recent plans to transform the country have rested in no small part on High Speed 2, a superfast rail line intended to connect London with Birmingham, Leeds, and Manchester. But since HS2 was proposed, in 2009, its costs have tripled, to more than £100 billion. It is the most expensive rail line in the world. (A special structure to protect a rare bat species near the rail line in Buckinghamshire required 8,000 permits and was built at a cost of £216 million.) The most important sections of the proposed route have been lopped off. The rump line—going from Birmingham, Britain’s second-largest city, to not-quite-central London—may be finished by 2040…. HS2 has been delayed for so long that two swiftly built towers near the terminus now themselves look derelict and in need of demolition.
…Building infrastructure, or much of anything else, has become all but impossible in the United Kingdom. In addition to having the world’s most expensive (not yet built) train line, Britain also hosts the world’s most expensive (not yet built) nuclear-power plant, Hinkley Point C. Its environmental-impact assessment ran 31,401 pages; the plant will feature a £700 million “fish disco,” which will pulse sounds underwater to deter animals from its intake pipes.
Upon closer inspection, the United States looks a lot less like a shining city on a hill and a lot more like a declining Great Britain, appendaged with one or two dynamic sectors, most notably AI. The similarities are especially obvious in the retrograde solutions Britain has lumbered into, namely attacking immigrants and trade—Brexit being the equivalent of a high tariff regime. Nations in decline, like people, tend to lash out at others rather than deal with their real problems. Needless to say, neither immigrants nor trade explain Britain’s—or California’s—inability to build high-speed rail or other infrastructure.
It is discomforting to watch the birthplace of the Industrial Revolution, individual rights, and free speech—the nation that once built the railways, the steam engines, the factories that remade the world—lose the capacity to build much of anything, or even to tolerate people speaking their minds. In parallel, instead of dealing with our real problems—almost all of our creation—the right gets literally hysterical over symbolic culture-war questions like birthright citizenship, while the left nominates candidates with Marxist-Leninist sympathies. The abundance and progress movements are some of the few shining lights. It’s not too late. But Great Britain is a warning.
James Mirrlees auction markets in everything
To mark what would have been Jim Mirrlees’ 90th birthday on 4 July, Nuffield College (Oxford University) is auctioning off some signed books from Jim’s personal collection and other special items of Jim’s generously donated by the Mirrlees family and the artist Yu Ji. The proceeds will support a fund for scholarships in Jim’ s memory.
The auction is conducted entirely online and is open to all.
Our auction is a simplification of the Product-Mix Auction that Paul Klemperer (Jim’s successor as Oxford’s Edgeworth Professor) designed for the Bank of England in 2007-8 at the beginning of the financial crisis. The Bank still runs its version regularly, and has now sold almost £400 billion of repos using it. (We expect to raise a little less!) This version has been programmed by Edwin Lock (Nuffield Research Fellow, 2021-24) who, along with Elizabeth Baldwin (Nuffield Research Fellow 2016-2017), has been involved with Paul in the further development of the Product-Mix Auction. (For more on this auction, see this paper, or this 5-minute film published by the Guardian newspaper.)
…The auction is focused on “social welfare”, not expected revenue…
Here is the link, via Tim Harford and Paul Klemperer..
Rent Control: The Ceiling Trap
Rent control is in the news again. Check out my new website, Rent Control: The Ceiling Trap. Here is just one bit:
Norway abolished its rent control in 1982, and the economist Are Oust realized the newspapers had been quietly recording the whole experiment. He collected housing classifieds from Oslo’s Aftenposten from 1970 to 2008 and watched the market turn inside out.
Under rent control, Oslo’s listings pages looked nothing like a housing market. It was tenants who advertised, pleading their qualities to landlords — “housing wanted” ads outnumbered “housing for rent.” Ten to fifteen percent of those ads were placed by the tenant’s employer, vouching for them the way a bank vouches for a borrower. Tenants offered babysitting, gardening, snow-shoveling, and janitorial work on the side to sweeten the deal. Landlords, for their part, could demand a tenant of a particular gender, age, occupation, region of origin — some ads specified “strong Christian beliefs.” Deposits commonly ran to 50 or 60 months’ rent, occasionally 100 or more: tenants effectively lent the landlord the equity of the flat, interest free. And only about 20 percent of “for rent” ads dared print the rent, much of which would have been illegal.
Then the ceiling lifted. Within a few years the page flipped: landlords advertised to tenants, roughly 80 percent of listings printed an asking rent, the mega-deposits vanished, and the demands for snow-shoveling Christians of specified gender dwindled to nothing. The price went back to doing the rationing — so nothing else had to.
Check out the whole thing–it’s fabulous.
What should I ask Daron Acemoglu?
Yes, I will be doing a Conversation with him. Obviously Acemoglu has published plenty, but likely this chat will focus on his recent writings and pronouncements on AI, and most of all his forthcoming book What Happened to Liberal Democracy? Remaking a Politics of Shared Prosperity. So what should I ask him?
Politically Incorrect Paper of the Day: The US Racial Wealth Gap
Writing in the QJE, Derenoncourt, Kim, Kuhn, & Schularick argue that today’s black-white wealth gap can be explained by differences in initial conditions from over a hundred and fifty years ago, i.e. slavery. But there is an important, and glaring objection: in the age of immigration (1850–1924) millions of whites immigrated to the United States with essentially no wealth and yet they caught up to the “heritage” whites quite quickly and indeed today are richer than heritage whites.
Brian Marein collects and carefully analyzes the data:
Persistent racial wealth inequality in the United States is often attributed to the intergenerational transmission of historical wealth disparities. However, inferring the determinants of long-run inequality from group-level data is complicated by the arrival of 30 million Europeans during the Age of Mass Migration (1850–1924), who are by construction included in average white wealth despite having no direct claim to the wealth accumulated by earlier Americans. This paper accounts for this compositional change in the white population by documenting wealth dynamics among European immigrants and their descendants. Cash-on-arrival data show that immigrants began with substantial wealth deficits relative to the native-born. Yet by the late twentieth century, these deficits had closed, as indicated by comparisons between the descendants of later-arriving Southern and Eastern Europeans and those of longer-established Northwestern Europeans. This pattern implies rapid intraracial wealth convergence, in contrast to the slower convergence observed across racial groups. A stylized model shows that these differences can be largely accounted for by income. These findings demonstrate that large wealth disparities do not mechanically persist when groups have access to comparable economic opportunities.
If initial conditions don’t explain the wealth gap then the most likely explanation is an income and/or savings gaps. I am reminded of an earlier politically incorrect paper of the year by Nathaniel Hilger and see also my review of his book The Parent Trap.
Will future biomedical advances be low marginal cost?
Most pharmaceuticals involve high upfront costs, to discover and test the drug, and very low marginal costs. Another pill can be printed almost for free.
That cost structure favors health systems, such as that of Britain, that try to pay lower for services. They can end up getting a relatively good deal from price discrimination. After all, they can be served at low marginal cost, at least for those ttreatments.
Now imagine a biomedical future where many more treatments are based on the sequencing of your individual genome, and then the development of specific treatments personalized to you. Obviously it will depend on developments, but very likely those remedies will have relatively high marginal costs.
In that setting the British approach to health care procurement and pricing will work less well. It is the well-capitalized, “overspending” systems, such as the United States, that will have an easier time making the adjustment.
“The rising relative advantage of well-capitalized health care systems” is a neglected trend, because it makes a lot of earlier elite pronouncements about health care economics look a bit off.
My ARC talk on AI and jobs
Twelve minutes long:
“One stop shopping” for why AI will not put everyone out of work.
Azeem Azhar (and others) on the state of the AI economy
Due to travel I have not had time to read this detailed report, but it is getting very good reviews
Works in Progress: Grid Connection Auctions
The latest issue of Works in Progress is superb. Every article is interesting.
Chris Gillett points out something surprising: the US has plenty of electricity generation capacity ready to go, the problem is connecting it to the grid. Grid connection is complicated because on the grid, supply must equal demand at every moment in time. Even without speeding the process, however, we could get more power connected to the grid if we rationalized the ordering of connections.
The main flaw of the interconnection process is that it uses a first-come, first-served queue. This means that high-priority requests can spend years stuck at the back of the line behind other less important ones.
In essence, we have an airport congestion problem in which small Cessnas can bump 747s. Auctions for connection rights are the solution, as pointed out for airports by Vickrey and the classic paper by Rassenti, Smith and Bulfin. Gillett also emphasizes that some loads should be allowed to connect on a flexible basis: if a data center can disconnect or use backup power during the few peak hours each year, it should not have to wait years for firm service.
Gillett also has a very nice explanation of how market prices balance electricity from different sources:
Market prices signal to power plant developers about levels of supply and demand. In the same way, prices balance different energy sources based on the strengths and weaknesses of each. For instance, as more solar panels are built, the value (and therefore price) of power during the middle of the day, when the sun is shining most, adjusts downward. From December 2020 to September 2025, maximum solar output in ERCOT increased from 4 to 29.8 gigawatts. And from 2020 to 2025, the value of power at 1pm relative to the highest-priced hour decreased from 92.9 percent to 38.7 percent. As one technology type becomes overbuilt, prices reflect that and developers react accordingly.
The evolving daily price shape in response to the abundance of solar energy was a signal that the grid needed storage capacity, and power plant developers responded. From 2020 to October 2025, ERCOT went from having almost no battery storage to a combined battery discharge of 8.6 gigawatts. The same process has played out in California and many European markets.
New Business Formation is Surging–Again.
New business formation is surging–again.
Business formation first jumped in 2020 as the pandemic reorganized work, shopping and logistics. After the pandemic ended, business formation leveled off, but it did not return to its old path. It remained historically high. Moreover, in the past 18 months or so business formation has surged again. Registered Agents Inc tracks new Articles of Organization or Incorporation filed in the 50 states and they report:
Every month in 2026 has set a new formation record, including March, which stands as the highest single-month total in the history of the Business Formation Report. Through May, 2.9 million new businesses have been formed nationwide, the strongest five-month start on record.
Stripe Economics agrees and calls this the age of the solopreneur. Among businesses using Stripe, recent cohorts are reaching serious transaction volumes faster than earlier cohorts.
The share of businesses (not just solopreneurs) reaching $1 million in cumulative revenue within a year after going live on Stripe was roughly 30% higher for the 2025 cohort as it was for the 2023 cohort, and it was roughly 3x higher for the 2025 cohort than the 2019 cohort.
Furthermore, the trend is not just in the United States. France, where, as the story goes, they have no word for entrepreneur, has also seen business creation reach record levels, driven heavily by micro-entrepreneurs.
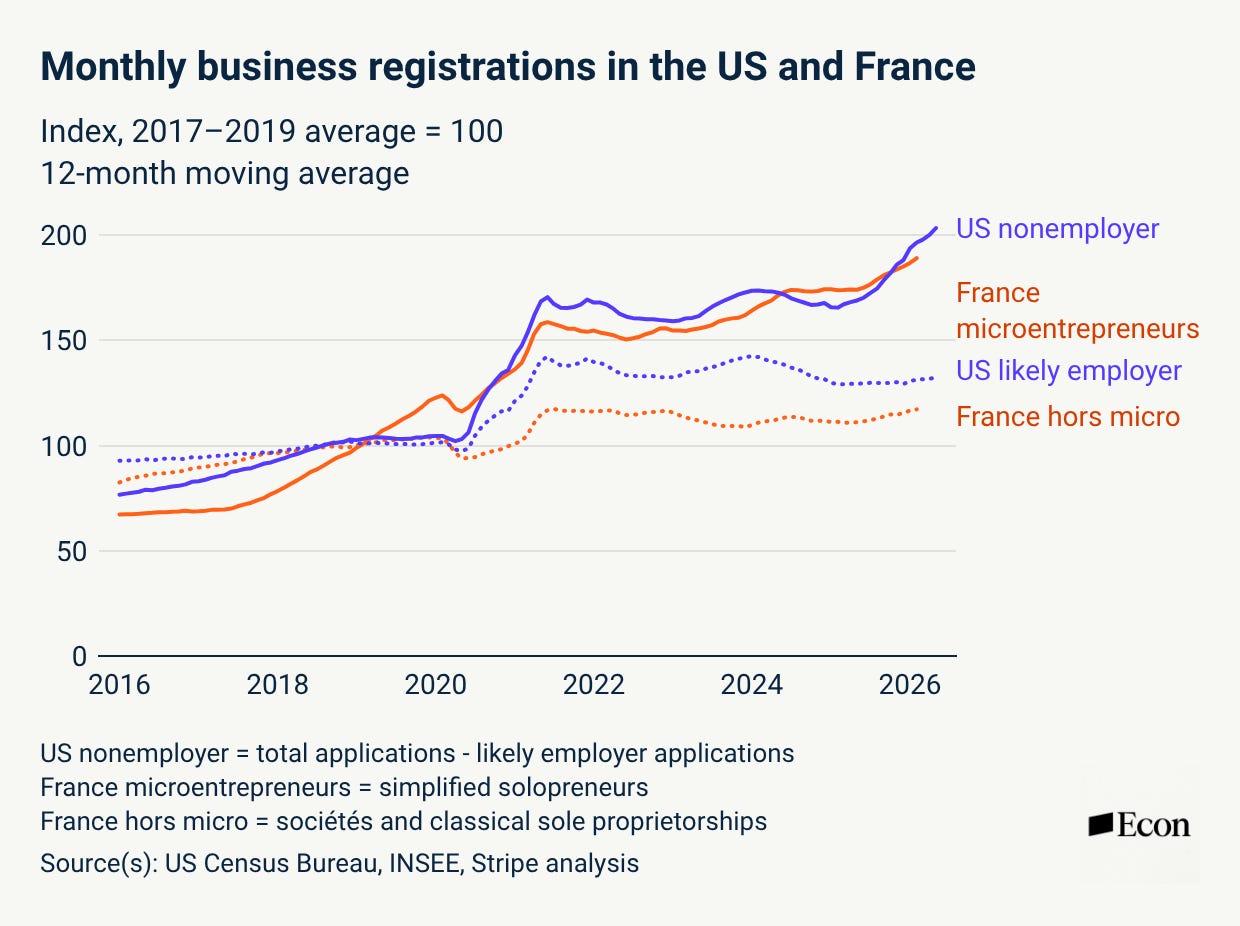
The most likely explanation is the devolution of power. A single person armed with Stripe, Shopify, cloud software, automated bookkeeping, and now AI can do what once required a small staff. Dynamism had been on a long secular decline, but we may now be seeing the early stages of an experimental economy—one in which far more people can test ideas, reach customers, and launch firms, some of which will grow very large, very fast.
I am told James Mill is buried there also
Translated from the Chinese
I think this is the Cursor moment for academia.
The Stanford REAP team has made their move, CoPaper.AI is mass-terminating the manual labor of traditional empirical papers. Link: copaper.ai/landing
If using large models to write papers before was just about polishing and compiling references for you, then this Project from Professor Ross Griebenow’s team at Stanford is like dropping a nuclear bomb in the empirical circles of social sciences and economics.
The greatest truth is the simplest; the heaviest sword has no edge. Its functions are straightforward. Feed in the raw dataset, and within 30 minutes, it can generate a complete DOCX paper complete with full Stata/R code and publication-quality charts.
It chains together EDA, variable definition, econometric model building (from OLS to advanced DID, regression discontinuity, causal forests) all using an Agent workflow.
Every chart it produces comes with 100% reproducible Stata, R, EViews source code underneath. How many low-quality paper mills and data drones’ jobs will this smash?
Data drones and paper ghostwriters are collectively facing unemployment countdown. Because from now on, for social science papers, AI handles all the entropy-increasing drudgery—humans only need to define the problem.
Here is the link. Mostly that is not true, so perhaps the Chinese are trying to demoralize us. But will it never ever be true? In two years be true? Less?
Two Roads to Fast Clinical Trials, and the US Takes Neither
The HHS (FDA, NIH, ARPA-H and related agencies) is moving to speed clinical trials in what they are calling Operation TrialBlazer (kudos on the pun). The motivator, of course, is China:
China has made biotechnology a strategic national priority, systematically expanding its clinical research infrastructure with government backing, streamlined regulatory pathways, and sustained investment. In 2021, China’s global share of Phase 1 trials surpassed the United States’ share for the first time, a milestone that would have seemed unlikely just a decade earlier. And in 2024, China surpassed the United States in the total number of clinical trials registered, with over 7,100 registered, representing 39% of global trials…. For certain cutting edge modalities, including cell and gene therapy, radioligand therapy, and stem cell therapy, China uses investigator-initiated trials to provide additional flexibility, though with some tradeoffs around oversight and quality control. This means that drugs can move into human testing if a researcher has an interest and funding. In the U.S., comparable trials might wait years to start.
I am also pleased to see that they mention Australia, another advanced democracy, as a leader in clinical trial regulation:
Australia’s Clinical Trial Notification System allows trials to begin in fewer than 70 days after a final protocol is submitted, with regulatory approval granted in as little as 21 to 28 days and sites activated within 6 to 12 weeks.
Keep those comparisons in mind. Operation TrialBlazer proposes some good reforms such as CMC clarification. CMC is Chemistry, Manufacturing, and Controls–and it deals with the basics of manufacturing a drug. The FDA, however, is very risk averse and companies know that so they have often gone overboard in CMC: for example, proving stability of a formula at 6+ months when the trial is to last only a few weeks or documenting their full commercial manufacturing process before they even know if the drug works and knowing full-well that the process will be changed many times before a drug actually gets to market. In short, a lot of cost for very little benefit. The FDA is now clarifying that this kind of thing is not necessary. Good, that is low-hanging fruit. There are other good ideas as well.
But note what they are not proposing. Despite using China and Australia as exemplars they are not going down either path. Where China is fastest is in cell therapy, gene therapy, radioligand, and stem cell work and in these areas, China lets trials proceed on an investigator-initiated basis: as the TrialBlazer document puts it, a drug can move into humans “if a researcher has an interest and funding.” China then combines this open (or lax) front end (for these products) with an all-of-government industrial policy to accelerate winners.
The US is declining to go down that path. Ok, not my call, but I get it. But they are also declining to follow Australia. In Australia there is also no government prospective regulatory evaluation of most early-phase clinical trials. Under the Clinical Trial Notification (CTN) scheme, the sponsor submits their protocol package to a Human Research Ethics Committee (HRECs)–Australia’s IRBs–and once the ethics committee approves, the sponsor notifies the regulator, the Therapeutic Goods Administration (TGA), and pays a fee. The TGA does not read and clear the package before the trial starts. The roughly 21-to-28-day “approval” and sub-70-day start figures in the document are fast precisely because the regulatory step is not an evaluation. The government regulator stays out of the front end for most clinical trials, although in direct contrast with China it does step in for the highest risk biologicals. China has decided, high-risk, high-reward.
Australia does certify the certifiers, the HRECs. Europe uses a similar system for medical device approval. It’s a system proposed by former medical officer at the FDA Henry Miller and one I have long supported for the US. China is more laissez-faire.
The US architecture in contrast rests on the “gold standard” FDA reviews and the “FDA will retain full regulatory authority and decision-making.” In short, all of the TrialBlazer reforms are about making the gatekeeper faster, cheaper to prepare for, and less uncertain. None of it is about getting rid of the gatekeeper.
Addendum: Full disclosure, I did some consulting with ARPA-H on related work. See also my previous post on the a radical deregulatory approach, Montana’s SB535 and a Potential Biotech Renaissance in America