Category: Economics
How to Make Judges and Referees Pay
A recent viral tweet, quoted by Elon Musk, points out that bartenders can be fined or even imprisoned if they serve alcohol to patrons who later kill someone while under the influence. Judges, in contrast, enjoy absolute or qualified immunity even when they repeatedly release defendants who go on to kill.
I agree that judges should face stronger incentives to make good decisions, but the obvious problem with penalizing judges who release people who later commit crimes is that judges would then have very little incentive to release anyone—and that too is a bad decision. Steven Landsburg solved this problem in his paper A Modest Proposal to Improve Judicial Incentives, published in my book Entrepreneurial Economics.
Landsburg’s solution is elegant: we must also pay judges a bounty when they release a defendant.
Whether judges would release more or fewer defendants than they do today would depend on the size of the cash bounty, which could be adjusted to reflect the wishes of the legislature. The advantage of my proposal is not its effect on the number of defendants who are granted bail but the effect on which defendants are granted bail. Whether we favor releasing 1 percent or 99 percent, we can agree that those 1 percent or 99 percent should not be chosen randomly. We want judges to focus their full attention on the potential costs of their decisions, and personal liability has a way of concentrating the mind.
One might object that a cash bounty will cost too much, but recall that the bounty is balanced by penalties when a released defendant commits a future crime. The bounties and penalties can be calibrated so that on average the program is budget-neutral. The key is to get the incentives right on the margin.
The structure of this problem is quite general. Ben Golub, for example, writes:
There should be a retrospective reputational penalty imposed on referees who vote no on a paper because the paper is too simple technically — if that paper ends up being important. It’s an almost definitional indicator of bad judgment.
Quite right, but a penalty for rejection needs to be balanced with a bonus for acceptance. Get the marginal incentive right and quality will follow!
Economists on AI and economic growth and employment
We completed the most comprehensive study of how economists and AI experts think AI will affect the U.S. economy. They predict major AI progress—but no dramatic break from economic trends: GDP growth rates similar to today’s and a moderate decline in labor force participation. However, when asked to consider what would happen in a world with extremely rapid progress in AI capabilities by 2030, they predict significant economic impacts by 2050:
• Annualized GDP growth of 3.5% (compared to 2.4% in 2025)
• A labor force participation rate of 55% (roughly 10 million fewer jobs)
• 80% of wealth held by the top 10% (highest since 1939)
That is from this very good and very detailed Twitter thread, worth reading in its entirety. Note this:
Only 5.2% of the variance is between scenarios—attributable to disagreement about AI capabilities themselves…
Here is the full paper, over 200 pages long, I will be reading through it. The list of authors is impressive, with Ezra Karger in the lead, also including Kevin Bryan, Basil Halperin, and many more. For some while this will stand as the best set of estimates we have. Here are the related forecasts of Seb Krier.
Is financial economics still economics?
That all sounded wonderful, and that core model and its offshoots dominated financial research for decades. The problem, however, was that it wasn’t true, or at least it wasn’t nearly as true as we had thought and hoped. When financial economists refined the models with more complete specifications, it turned out Beta didn’t predict stock returns much at all. Eugene Fama and Kenneth French delivered one of the final blows to earlier approaches with a 1992 paper that showed Beta didn’t have explanatory power over expected returns at all. Since Fama himself was one of the original architects of CAPM-like reasoning, and French also was a renowned finance economist, these revisions to the model were credible. For all its original promise, marginalism, and the concomitant notion of diminishing marginal utility, no longer seemed to help explain asset returns.
Under one plausible account of intellectual history, you can date the decline of marginalism to that 1992 paper. In the most rigorous, data-oriented, and highest-paying field of economics, namely finance, marginalist constructs had every chance to succeed. In fact, they ran the board for several decades. But over time they failed. In the most prestigious field of economics, marginalism has been in full retreat for over 30 years, and it shows no signs of making a comeback.
We already know that financial practice is dominated by the (non-economist) quants. But how about financial economics research, the parts that are still done by economists? What direction is that work moving in?
I was struck by a 2024 paper published in the Journal of Financial Economics, one of the two leading journals of financial economics (Journal of Finance is the other). The authors are Scott Murray, Yusen Xia, and Houping Xiao, and the title is “Charting by Machines.” The core result is pretty simple, and best expressed in the well-written abstract:
“We test the efficient market hypothesis by using machine learning to forecast stock returns from historical performance. These forecasts strongly predict the cross-section of future stock returns. The predictive power holds in most subperiods and is strong among the largest 500 stocks. The forecasting function has important nonlinearities and interactions, is remarkably stable through time, and captures effects distinct from momentum, reversal and extant technical signals. These findings question the efficient market hypothesis and indicate that technical analysis and charting have merit. We also demonstrate that machine learning models that perform well in optimization continue to perform well out-of-sample.” Murray, Xia, and Xiao (2024, p. 1). Or consider the new paper Borri, Chetverikov, Liu, and Tsyvinski (2024). They propose a new non-linear, single-factor asset pricing model. In the abstract: “Most known finance and macro factors become insignificant controlling for our single-factor.” Yet you won’t find traditional economic variables discussed in this paper, it is all about the math, in particular a representation of the Kolmogorov-Arnold representation theorem.
In other words, the successful approach to predicting returns is giving up on traditional portfolio theory and using the “theory-less” technique of machine learning. Although this is published in the Journal of Financial Economics, in some significant sense it is not economic reasoning at all. It is calculation, combined with expertise in math and computer science. The modeling is not economic modeling in a manner that has ties to marginalism or standard intuitive microeconomic theory. And the work is predicting excess returns in a pretty robust and successful way…
There is a recent working paper which is perhaps more striking yet, by Antoine Didisheim, Shikun (Barry) Ke, Bryan T. Kelly, and Semyon Malamud. They pick up from Arbitrage Pricing Theory (APT), a well-established idea from financial economics. APT typically looks for “factors” in the data which predict excess returns, and a traditional APT model might have found five or six such factors. Are “inflation” or perhaps “the term structure of interest rates” useful factors? Well, that can be debated, but if so, those results sound pretty intuitive. But those intuitions seem to be disappearing. In a paper by these authors, they apply machine learning methods to look for more factors. As we know, machine learning is very good at finding non-obvious relationships in the data. The largest model they built has 360,000 (!) factors, and it reduces pricing errors by 54.8 percent relative to the classic six-factor model from Fama and French. Bravo to the authors, but what kinds of intuitions do you think possibly can be supported by those 360,000 factors?
That is from my new The Marginal Revolution: Rise and Decline, and the Pending Revolution in AI.
The economics of dropout risk
Bryan Caplan keeps hammering this point home, it is good to see follow-up work:
In the United States, college dropout risk is sizable. We provide new empirical evidence that beliefs about the likelihood of earning a bachelor’s degree predict college enrollment, and that the distribution of these beliefs exhibits widespread optimism. We incorporate this distribution of beliefs into an overlapping generations model with college as a risky investment that can be financed via federal loans, grants, family transfers, or earnings. We then examine the welfare impact of access to federal student loans. We find that access can reduce welfare for young adults who are low-skilled, poor, and optimistic, due to their mistaken beliefs.
That is from AEJ: Macroeconomics, by Emily G. Moschini, Gajendran Raveendranathan, and Ming Xu. Via the excellent Kevin Lewis.
New issue of Econ Journal Watch
EJW Volume 23, Issue 1, March 2026
Specification Searching in the Race between Education and Technology: Joseph Francis criticizes a canonical model of the American labor market, which has been used to advocate for more funding for education to reduce inequality. He shows how the model has routinely failed to predict the evolution of the college wage premium. Ad hoc econometric adjustments have been necessary to make the model fit the data, most notably in Claudia Goldin and Lawrence F. Katz’s well-known book. (The commented-on authors are hereby invited to reply in a future issue.)
Globalization and the China Shock: A Reassessment: David Autor, David Dorn, and Gordon Hanson estimated the effect of imports of manufactured goods from China from 1990 to 2007 on employment, wages, and social welfare payments in the USA, concluding that imports from China reduced manufacturing employment and lowered wages of workers in non-manufacturing industries. Robert Kaestner argues that the authors’ focus only on Chinese imports, which are correlated with imports from other countries and likely other omitted variables, muddles the interpretation and usefulness of their results. Kaestner argues that their estimates do not measure the effect of Chinese imports on employment and wages holding all other things equal, and do not even measure the broader equilibrium effect of Chinese imports on outcomes that includes changes in imports from other countries. Overall, the evidence suggests that omitted variable bias is likely, which renders their estimates uninformative. (The commented-on authors are hereby invited to reply in a future issue.)
Learning on machine learning on the housing supply impact of land use reforms: An Urban Studies article reports relatively modest housing-stock gains from liberalization, based on a dataset of reforms identified via machine learning applied to newspaper coverage. Researchers at the American Enterprise Institute challenge the article’s methodology and conclusions, and the Urban Studies authors respond.
An Article in Science on Covid Origins Contains a Fundamental Error: An influential article claimed that Bayesian analysis of the molecular phylogeny of early SARS-CoV-2 cases indicated that the likelihood that two successful introductions to humans had occurred was greater than the likelihood that just one had occurred. After correcting a fundamental error in Bayesian reasoning, the results presented in that paper imply larger likelihood for a single introduction, reducing the plausibility of the wet-market zoonosis account of Covid’s origins. (The commented-on authors were invited to reply and the invitation remains open.)
A Critique of Synthetic Control Method Studies on Covid-19 Policy—Evidence from Sweden: Five studies employing the Synthetic Control Method (SCM) conclude that Sweden would have experienced lower mortality had it imposed a mandatory lockdown in early 2020. Dividing Sweden into four hypothetical countries based on winter holiday timing—a proxy for pre-lockdown viral seeding—Jonas Herby shows that the estimated lockdown effect varies dramatically across regions with identical policies, suggesting SCM captures variation in viral spread rather than a causal policy effect. Sweden’s low excess mortality in the end suggests that Sweden’s state epidemiologist, Anders Tegnell, was right all along. (The commented-on authors are hereby invited to reply in a future issue.)
Central Banking Research Is Increasingly Directed to Environment, Inequality, Gender, and Race: Radu Șimandan and Cristian Valeriu Păun use the Scopus database to show how environment, inequality, gender, and race have soared as topics in research outlets supposedly focused on money and banking. They discuss the hazards of subverting price stability and other traditional central bank mandates.
Power Analysis Is Essential—A Case Study in Rounded Shapes: A Journal of Consumer Research article reported an A/B test where simply rounding the corners of square buttons increased click-through rate by 55 percent, but provided no power analysis. Ron Kohavi and coauthors show that the original study was highly underpowered. They report that three high powered A/B replications, each over two thousand times larger, had estimated effects approximately two orders of magnitude smaller than initially claimed. (The commented-on authors are hereby invited to reply in a future issue.)
“Impartial spectator” in Adam Smith’s The Theory of Moral Sentiments: In the previous issue, a critique alleged that numerous scholars flatten Smith’s “impartial spectator.” Jack Weinstein responds with “Adam Smith’s Impartial Spectator Is Neither Divine Nor an Ideal Observer,” and the critics renew their case against flattening “impartial spectator.”
The Ideological Profile of France’s Economic Bestsellers: Alexis Sémanne inspects the 100 economics bestsellers for 2024, as listed by a leading French bookseller. He develops seven categories and evaluates each book for its ideological tendency. Quite few of the books offer a freedom-oriented perspective.
Green Vanities in Europe: John Constable reviews A Green Entrepreneurial State? Exploring the Pitfalls of Green Deals, edited by Magnus Henrekson, Christian Sandström, and Mikael Stenkula, a book which reveals more than the fact that green deals in Europe have been failures.
EJW thanks its referees and others who contribute to its mission.
EJW Audio:
- Michael Weissman on Lab Leak and Science
- Dan Johansson on Economics without Entrepreneurship and Institutions
- Henry Hardy on Isaiah Berlin
Sentences to ponder
This matters for the AI question, and the book leaves it unfinished. If the breakthroughs of the past required social conditions, not just cognitive capacity, then what does it mean when the next breakthroughs are produced by systems that have no social conditions at all? A neural net does not need a university chair or financial independence from the church. It does not need to reorganize its commitments. It does not, in any recognizable sense, have commitments. The machine that replaces the marginalist is not a better marginalist. It is a different kind of thing entirely.
That is from Jônadas Techio, presumably with LLMs, this review of The Marginal Revolution is interesting throughout. And this:
Maybe the book demonstrates only that Cowen personally remains good at something the field no longer needs.
Grade Caps are Not a Good Solution to Grade Inflation
It’s well known that grade inflation has “degraded” the informational content of grades at many colleges. At Harvard, two-thirds of all undergraduate grades are now A’s—up from about a quarter two decades ago. In response, a Harvard faculty committee has proposed capping A grades at 20 percent of each class (plus a cushion for small courses). That may give professors some cover to resist further inflation, but it doesn’t solve the real problem.
The real problem is not inflation per se. It’s that students are penalized for taking harder courses with stronger peers. A grade cap leaves that distortion intact—and can even amplify it. As Harvard economist Scott Kominers argues:
A grade cap systematically penalizes ambitious students for surrounding themselves with strong classmates. Perverse course-shopping incentives ensue as a result. A student who is prepared for an advanced course but concerned about landing in the bottom 80 percent may choose to drop down preemptively—seeking out a pond where they are a relatively bigger fish. As strong students move into lower-level courses, competition for A grades increases there while harder courses continue to shrink—reducing their A allocation further and driving more students away.
The underlying issue is informational. A grade tries to capture two things—student ability and course difficulty—with a single number. Gans and Kominers show that in general this is impossible: if some students take math and earn B’s while others take political science and earn A’s, there is no way, from grades alone, to tell whether the difference reflects ability or course difficulty.
There is, however, a solution in some cases. Clearly, if every student takes some math and political science courses, informative patterns can emerge. If math students tend to get B’s in math but A’s in political science, while political science students get A’s in their own field but C’s in math, you can begin to separate course difficulty from student ability.
Students don’t all overlap the same classes. But full overlap isn’t necessary—you just need a connected network. If Alice just takes math courses, Joe takes math and political science courses, and Bob just takes political science courses, then Alice and Bob can be compared through Joe. With enough of these links, the entire system can be stitched together. The more overlap, the more precise the estimates.
Valen Johnson proposed a practical method along these lines in 1997. Gans and Kominers embed the same intuition in a much more general framework, showing exactly what can and cannot be inferred, and under what conditions.
The great thing about achievement indexes based on relative comparisons is that they are robust to grade inflation and do not penalize students for taking hard classes or subjects. A political science student who chooses to take a tough math class instead of an easy-A intro to sociology course won’t be penalized because their low math grade will, in effect, by boosted by the difficulty of the course/quality of the students. That’s good for the student and also good for disciplines that have lost students over the years because they held the line on grade inflation.
One final point. Harvard’s cap proposal appears to have been developed with little engagement with researchers who have studied problems like these for decades in the mechanism and market design literature—people like Kominers, Gans, Budish, Roth, Maskin, and Sönmez, some of them at Harvard! Moreover, this isn’t a case of ignoring high-theory for practice. The high-theory of mechanism design has produced real-world systems including kidney exchanges, school choice mechanisms, physician-resident matching, even the assignment of students to courses at Harvard, as well as many other mechanisms. Mechanism design is practical.
Grade inflation is a mechanism design problem—and we know a lot about how to solve it, if we want to solve it.
Claudia Goldin and the WNBA
After Claudia Goldin became the first woman to win a solo Nobel in economics in 2023, she received hundreds of invitations and requests. She accepted just three.
One of them was advising the WNBA players union as the women prepared to negotiate a new labor deal with the league.
When Goldin replied via email to Terri Carmichael Jackson, executive director of the players union, “I remember just reading it and screaming,” Jackson said. Goldin had one requirement: She refused to be paid.
This month, the two sides reached a collective bargaining agreement that gave Women’s National Basketball Association players a nearly 400% raise. Starting this season, players’ average salary will top $580,000.
It isn’t just the biggest pay increase in U.S. league history. It is, as far as Goldin is aware, the biggest increase any union anywhere has ever negotiated.
“It’s astounding,” the 79-year-old Harvard economist said.
Mike Bass, a spokesman who represents both the National Basketball Association and the WNBA, called the deal “transformational.”
…More recently, as the pay negotiations stretched on, Goldin said she stayed focused not on the countless separate points in the typical lengthy labor deal but on one central equation: the fraction of league revenue going to players’ salary and benefits.
Goldin’s calculations had a calming effect on the players, said Jackson, the union’s executive director.
Here is more from the WSJ. Via Anecdotal.
Scott Sumner on *The Marginal Revolution*
My favorite part of Tyler’s book is where he asks a very good but non-obvious question: Why did it take so long for economics as a field to develop a coherent model or framework of analysis? Much of the book discusses how three economists simultaneously developed marginal analysis, with a focus on the work of Stanley Jevons. Here I’ll briefly provide the intuition of marginal analysis and then explain why economics is both extremely easy but also quite difficult…
Tyler does a great job explaining why Jevon’s model of marginal analysis (which underlies most of modern microeconomics) is elementary on one level, but also something that wasn’t discovered until the 1860s because it was not at all obvious. Here’s how he concludes Chapter 3:
[This is TC now] By studying the slow intellectual development of economics, and contrasting it with other fields of study, we can learn the following:
1. Some insights are very hard to grasp, even if they are apparently simple once they are understood. People need to “see around corners” in the right way to understand these insights and incorporate them into their world views.
2. Economics is one of those fields, and that is why it took intuitive economic reasoning so long to evolve, marginalism included. Those of us who are educators, or who spend time talking to policymakers, should take this point very seriously.
3. Even very, very smart people are likely unaware that these “see around the corner” insights are missing – did Euclid rue that he did not have access to proper supply and demand and tax incidence theory? Probably not.
4. Economics is not the only such field that is hard to grasp, some other examples being segments of botany, geology, and evolutionary biology.
5. Scientific revolutions come about when many complementary pieces are in place, such as financial support, intellectual independence, and networks of like-minded others to talk with.
Those conditions help people to understand that “seeing around those corners” can bring both high social and professional returns.
Are there major conceptual corners that today still no one can see around? If so, how might we discover what they are? And why are we not working harder on this? Or are we?
Here is the rest of Scott’s commentary. Here is the online book.
Shruti interviews V. Anantha Nageswaran on the Indian economy
He is currently serving as the Chief Economic Advisor to the Government of India, and also is the co-author of the books Economics of Derivatives and The Rise of Finance: Causes, Consequences and Cures. The podcast covers import substitution and strategic resilience, futures and options market, gross fixed capital formation, crypto markets, India’s growth trajectory, and much more.
Here is the audio and video on YouTube. Here is a linked transcript. Excerpt:
RAJAGOPALAN: The policy response to this has come in a couple of different ways. One has come through SEBI. It has started raising contract sizes and limiting weekly expiration,and so on. Another instrument has come through taxation. There have been STT [Securities Transactions Tax] hikes in consecutive budgets,but there is one thing about STT that I want to understand a little bit better from someone like you who has thought about this deeply.
Now, STT on futures is being levied on the notional value of the contract, which is the full traded price, whereas the STT on the options is levied on the premium, which is a small fraction of the overall underlying value of the notional exposure. The effective tax that is imposed is much more on the futures trade, manyfold more actually, than it is on the options trade, whereas the speculation is mostly happening on the options side, which is also where most of the retail investors are losing money because the futures side is much better capitalized, larger firms, and so on.
NAGESWARAN: No, also the futures side is probably used more by institutions, and therefore, they are able to put up the margin requirement, etc., better than the options trades, where the individuals are being sold almost like the₹10 sachet-type options, and the options…
RAJAGOPALAN: Exactly, sachetization options, absolutely.
NAGESWARAN: Yes. Go ahead.
RAJAGOPALAN: Now with each successive hike in the STT,we’re seeing the gap widen. It’s on the margin, making futures relatively more expensive than options just because it’s taxing each trade. It’s like a toll fee that’s paid almost on every transaction. Your book was precisely about understanding these kinds of policy instruments. Given that now we have a tax instrument which inadvertently favors the more speculative instrument. Is that a good way of thinking about it, or how would you think about this problem?
NAGESWARAN: No, I think you have given me a lot to think about on this. I probably haven’t applied my mind as much to the mechanics of the STT being levied on the premium when it comes to options, but on the notional value of the contract when it comes to futures. Actually, you have given me something to think about. As you said, it could be having the unintended consequence of reducing the hedging role of futures, which probably is playing a better role there and encouraging the speculative element. Let me think about it and also probably take back this aspect of the conversation back to my colleagues in the revenue department, in the Ministry of Finance. Thank you for that, yes.
Of great importance for the world’s most populous country.
Social Security Should Be a Forced Savings Program Not a Welfare Program
There is a growing movement to eliminate the wage cap on Social Security taxes while capping benefits. The argument, often from the center-right, is that Social Security is insolvent and that “tough” choices are needed to save it. But this moves the system in exactly the wrong direction.
One of the better features of Social Security is that it has never been purely redistributive. It has also functioned, in part, as a forced-savings program. The Social Security Administration itself emphasizes that benefits depend on earnings history: earn more, retire with more. Why do some people receive large Social Security checks? Because they paid a lot more into the system.
Eliminating the wage cap while capping benefits weakens, and in the limit destroys, that connection. It turns Social Security away from forced saving and toward retirement welfare financed by a broader tax on earnings. That is a bad idea.
The problem is not just that this creates another welfare program. It also worsens marginal incentives. A tax that buys you a claim on future benefits is not the same as a pure tax. Suppose 10 percent of your salary goes into a 401(k). That reduces current consumption, but it is not simply money lost to the state. You receive an asset in return. It is closer to a purchase than to a tax–a reason to work more not a reason to work less.
Social Security is not a personal retirement account, but it does contain that logic. There is a connection between taxes paid and benefits received. To the extent that workers understand that connection, the payroll tax is less distortionary than an ordinary tax of the same size. Part of what workers pay is offset by the expectation of future benefits.
Gut that connection, however, and the tax becomes more distortionary even if total taxes paid and total benefits received stay the same. The averages can remain unchanged while the marginal incentives deteriorate. Once additional taxes no longer generate additional benefits, the system looks much more like a straight tax on work.
A much better reform would move in the opposite direction: strengthen the link between contributions and benefits. Make Social Security more like what many people already think it is—an individual account that accumulates benefits over time. The stronger that link, the lower the effective tax wedge.
This would also improve the politics of the system. A welfare program invites zero-sum conflict: my benefit comes at your expense. A claim-based system is less divisive. It ties benefits more clearly to contributions and makes rising prosperity good for everyone. In that kind of system, we can all become richer—including low-wage immigrants—without treating retirement policy as a fight over who gets to pick whose pocket.
Addendum: James Buchanan first made these points here. John Cochrane gets the economics right, of course.
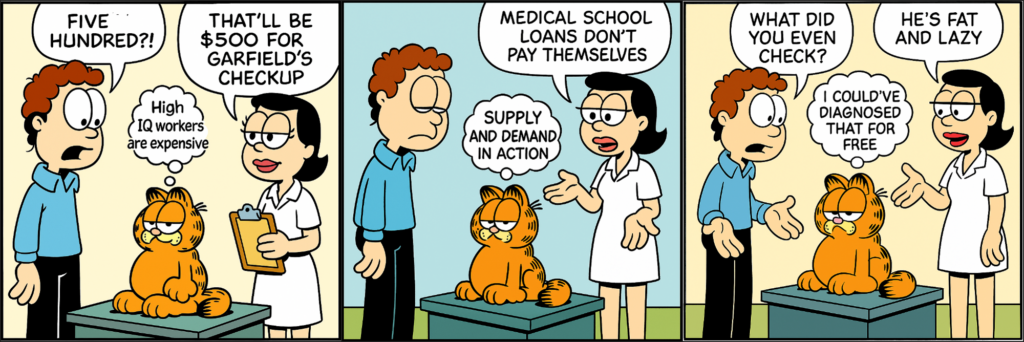
Marginal Garfield
Marginal Garfield generates an original Garfield cartoon every day based on posts from Marginal Revolution! Here is the first strip. You can guess the post. Is there now any reason to come to MR? What a world.
You can also check out Rationalist Garfield which pulls from Less Wrong.
We thank Tim Hwang.
Henry Oliver calls it a Swiftian ending
To The Marginal Revolution: Rise and Decline, and the Pending AI Revolution, here is the very close of the book:
There is however a slightly scarier version of this story yet. Maybe our intuitions about the world, including the economic world, were never so strong in the first place. Maybe we put so much value on “intuitive” results, in 20th century microeconomics, as a kind of cope and also security blanket, to make up for this deficiency. But our intuitions, even assuming them to be largely correct, always were just a small corner of understanding, swimming in a larger froth of epistemic chaos. And now the illusion has been stripped bare, and the true complexities of economic reasoning are being revealed.
As Arnold Kling would say, “Have a nice day.”
Can I say again “Have a nice day”?
What is economics these days?
From The Marginal Revolution: Rise and Decline, and the Pending AI Revolution:
The day before drafting this paragraph, I blogged a paper on confidence gaps between men and women. It was a paper written by economists, published in the prestigious American Economic Review, the profession’s number one journal. Is this actually sociology, or personality or social psychology, or part of some gender studies field? No one in the economics profession cares to discuss that anymore. It is not that there is a dogmatic attachment to what used to be called “economic imperialism,” rather the view is that if the paper is good enough … it is good enough to publish. I also recently read a paper on using cell phone data to estimate how many people actually were attending church. Freakonomics guru Steve Levitt wrote and published well-known papers on the choice of baby names and corruption in Sumo wrestling116See Exley and Nielsen (2024), and on cell phones see Pope (2024)..
The dirty little secret is that what distinguishes economics as a field, right now, is a mix of higher standards, harder work, better math, and higher IQs. That is the real (dare I say marginal?) contribution of “empirical economics today,” not marginalism per se, though of course contemporary models typically are consistent with marginalist reasoning…
One modest sign of all these changes is how many advisors, when speaking to individuals considering economics graduate school, recommend math or even computer science as a possible background undergraduate major. While most are still undergraduate economics majors, if only because that is where their interest in economics came from, no one seems to mind if they are not. These days, a background in mathematics or computer science is at least as useful for the graduate work to come. Once you get to graduate school, you will have to learn plenty of math and programming anyway, so why not start off in those fields? The prevailing attitude is that the economics you can figure out along the way, or for some topics you may not need to know much of it at all. How complicated are all those economic principles anyway? General skills of apprenticeship and plain ol’ hard work are growing in importance too, as top graduate programs increasingly want their incoming students to have done a “predoc” with an accomplished researcher somewhere along the way.
That is from the chapter on the future of economics in a world with advanced AI.
Addendum: On The Marginal Revolution book, I would most of all like to thank Jeff Holmes for the great job he did on the project, all of the actual work (other than the writing) is from him. He is also producer of CWT, I owe much to him!
*The Marginal Revolution: Rise and Decline, and the Pending AI Revolution*
I am offering a new piece of work — I do not quite call it a book — online and free. It has four chapters, is about 40,000 words, is fully written by me (not a word from the AIs), and it is attached to an AI with a dual page display, in this case Claude. Think of it as a non-fiction novella of sorts, you can access it here. You can read it on the screen, turn it into a pdf (and upload into your own AI), send it to your Kindle, or discuss it with Claude.
Here is the Table of Contents:
1. What Is Marginalism?
2. William Stanley Jevons, Builder and Destroyer of Marginalism
3. Why Did It Take So Long for the Science of Economics to Develop?
4. Why Marginalism Will Dwindle, and What Will Replace It?
Here are the first few paragraphs of the work:
How is it that ideas, and human capabilities, become lost? And how is that new insights come to pass? If eventually the insight seems obvious, why didn’t we see it before? Or maybe we did see it before, but didn’t really know we were on to something important? Why do new insights arrive suddenly, in a kind of flood? How do new worldviews replace older ones?
And what does all of that have to do with the future of science, the future of research, and the future of economics in particular? Especially when we try to understand how the ongoing artificial intelligence revolution is going to reshape human knowledge, and the all-important question of what economists should do.
Those are the motivating questions behind this work, but I will address them in what is initially an indirect fashion. I will start by considering a case study, namely the most important revolution in economics, the Marginal Revolution (to be defined shortly). The Marginal Revolution made modern economics possible. What was the Marginal Revolution? How did it start? Why did it take so very long to come to fruition? From those investigations we will get a sense of how economic ideas, and sometimes ideas more generally, develop. And that in turn will help us see where the science, art, and practice of economics is headed today.
Recommended! I will be covering it more soon.