The Travel Arbitrage Challenge
Chris, a loyal reader (natch), poses the following challenge. He is planning to travel, perhaps to Venezuela, but other countries are open. He’d like to profit from an arbitrage opportunity which could be due to official and un-official exchange rates or it could be a goods-based arbitrage. At one point, for example, you could do quite well bringing condoms to Russia but no longer. Nothing illegal especially on the import side or nothing too illegal. I get the feeling he would go for bringing in Cuban cigars if that were his best bet.
Thus, MR readers, the challenge. What country and what arbitrage?
As for me, I always eat well and get a haircut when I’m in a poor country (thanks Bela Balassa) but that arbitrage won’t pay for the trip. Can you do better?
The Implications of Behavioral Economics Are Not Obvious
Yesterday’s post, Stayaway from Layaway, elicited lots of comments but less analysis.
Some commentators suggested that people who use layaway plans have commitment problems (self-control problems) but that they are meta-rational and choose layaway programs to help them overcome. The problem is that when people are irrational at one level and rational at another it’s difficult to know which level is in control and which level is being appealed to by firms.
People who have self-control issues may think that they are being meta-rational by entering into layaway programs but perhaps, ala Dunning-Kruger, they are fooling themselves and will soon find it difficult to pay on the installment plan. According to one marketer, “up to 25% of layaway orders, on average, are cancelled.” Canceling exposes the consumer to service and cancellation fees. Moreover, I wouldn’t be surprised if some people never get around to reclaiming their payments. We know, for example, that billions of dollars on gift cards are never used.
We also need to keep in mind the incentives of the seller. Walmart, Kmart and Best Buy offer layaway programs because they increase profit. Are the higher profits a result of selling commitment to the meta-rational? Or are the higher profits the result of getting the less than perfectly rational to buy more? The ultimate commitment plan is to not buy what you can’t afford and layaway doesn’t help you with that problem. What layaway does do is encourage you to commit now to buy at Walmart. In other words, it binds you to Walmart and, fyi, it does so weeks before goods typically go on sale.
The way the programs are often advertised and discussed–layaway in case the store runs out!–is also a classic sales technique to encourage buying by eliciting feelings of (false) scarcity and potential loss.
I would like to see more data but I have not yet seen any reason to revise my belief that layaway plans are often a bad deal for consumers. I have, however, discovered one reason for layaway that does make some sense. Namely, to keep the presents hidden from snooping children.
Stayaway from Layaway
Layaway plans are immensely popular, a fact I find deeply puzzling much like the popularity of Justin Bieber, Snooki, and homeopathy makes me question the rationality of my fellow human beings.
The typical layaway plan requires a deposit of 10-15% of the price of the good, say a new TV. If the consumer pays the balance over the following 10-12 weeks (i.e. by Christmas) they can pickup the good. If the consumer doesn’t pay the balance they get a refund of payments made less a service fee.
 Walmart and Kmart advertise their layaway plans heavily. I am shocked, however, that so-called consumer advocates also have good things to say about poor people lending big corporations money:
Consumer advocates say layaway is a great way to manage a major purchase and stick to a budget, allowing consumers to spread the cost of an item over a number of payments without running up a lot of costly debt.
…”The fees, if any, are generally nominal and probably much lower than the interest you’d pay if you purchased those things with a credit card and didn’t pay off the bill for several months,” said Tod Marks, senior editor and shopping expert at Consumer Reports.
Stop the insanity! The relevant comparison is not to buying on credit but to saving. Instead of lending Walmart money, get yourself an old-fashioned piggy bank and avoid the cancellation fee and the hassle of going to the store to make the periodic payments.
Tod Marks, from Consumer Reports (!), also makes this astounding argument:
With layaway, you don’t have to worry that the store will run out of an item you want,” he said.
Are we living in the Soviet Union? Who worries about Walmart and Kmart running out of goods? Occasionally an item will be discontinued but then the replacement is usually better and/or cheaper. Similarly, layaway plans advertise that you can “lock-in” the current price. Right, and if the price goes down or you find a lower price elsewhere you are similarly locked in.
Still not convinced? In the spirit of Tabarrok’s Wager I offer Tabarrok’s Layaway Plan.
Send me $10 right away along with a message telling me what you want, when you want it and the current price. Save your money. If you save enough to buy the good at the requisite time send me a note and I will heartily congratulate you with a $10 reward. If you don’t save enough, thanks for the $10 and better luck next time. Unlike Walmart I will not guarantee the current price but Tabarrok’s Layaway Plan offers significant advantages that Walmart’s plan does not. On the day that you have saved up enough, Tabarrok’s Layaway Plan lets you buy at any store and at the lowest price that you can find! And that’s not all! Tabarrok’s Layaway Plan offers another great advantage, The Tabarrok Switch™. If you find a good that you like more than the good that you had originally planned to buy the Tabarrok Layaway Plan lets you switch to the new good!
Congratulations on choosing the Tabarrok Layaway Plan, the plan with the most options and flexibility of all layaway plans.
Saving Lives with Distributed Intelligence
One of the general features of information technology is that through coordination it makes better use of distributed resources, such as workers, automobiles or energy. An excellent case in point is being tested in Stockholm, Sweden. SMSlivräddare (in Swedish) has a large list of people who are trained in cardiopulmonary resuscitation (CPR). When an emergency call is received indicating a possible heart attack, SMSlivräddare finds the mobile phone user(s) closest to the potential victim and alerts them with a text message. The message also contains a map to the victim’s location.
Survival rates for heart attack outside a hospital in Sweden are low, only about 5-10% but every minute shaved off the time it takes to begin CPR increases the survival rate by 10%. When notified, SMS responders arrive faster than ambulances about 50% of the time so the potential for saving lives is quite large (final data on the research project are not yet in).
Could such a system work in the United States? Maybe, a similar but more passive app is available in a few locations. Legal issues are a threat. Good Samaritan laws offer some protection although they often apply only to medical professionals. The threat, however, is not really to the responder but to the service. It’s interesting to watch Shark Tank, anytime a medical entrepreneur makes an appearance the sharks run away for fear of liability. Still, if the service were attached to a hospital and integrated with ambulances services, it ought to be possible to be insulated but this will require significant political entrepreneurship.
Hat tip: Connor Tabarrok.
Hard Social Science Fiction: Neptune’s Brood
Hard science-fiction is science fiction that respects the findings and constraints of contemporary science. By analogy, I deem hard social science fiction* to be science fiction that respects the findings and constraints of contemporary social science especially economics but also politics, sociology and other fields. Absent specific technology device such as a worm-hole, hard science fiction rejects faster than light travel as little more than fantasy. I consider Eden-like future communist societies similarly fantastical. Nothing wrong with fantasy as entertainment, of course, just so long as you don’t try to implement it here on earth.
Charles Stross is one of my favorite hard social science fiction authors. Stross writes both hard science-fiction and hard social-science fiction, sometimes in the same book and sometimes not. The Merchant Prince series, for example is hard social-science fiction drawing on development economics with a fantasy walk-between-the-worlds element while Halting State is hard-hard science-fiction set in the near future (n.b. HS memorably begins with a bank robbery from Hayek associates).
Stross’s latest, Neptune’s Brood, is hard-hard science-fiction set far in the future and perhaps best illustrated with this telling quote:
It is a truth universally acknowledged, that every interstellar colony in search of good fortune must be in need of a banker.
Although set far in the future, Neptune’s Brood contains plenty of commentary on recent events if one reads it carefully for hidden meaning, i.e. a Strossian reading. It is no accident, for example, that it opens with a quote from David Graeber’s Debt and finishes with altruist squids.
Neptune’s Brood is Stross’s attempt to understand money by thinking about what money and banking would look like given interstellar travel and relativity. Not surprisingly, Stross draws upon Paul Krugman’s Theory of Interstellar Trade and also (perhaps less explicitly) on the new monetary economics of Fama, Black, Hall, Cowen and Krozner. One plot point turns on what might happen should the velocity of money increase dramatically! I was also pleased that privateers make an appearance.
Hard social-science fiction is not just about economics. NB also contains interesting commentary on technology, religion, social organization, reproduction and their mutual influences. I wouldn’t put NB at the top of my list of Stross favorites but I enjoyed Neptune’s Brood and you need not let the commentary interfere with the story itself which in Stross fashion moves along at a rapid clip with plenty of enjoyable action and mystery. Recommended.
* yes, it should probably be hard social-science science-fiction but that is too much of a mouthful.
Bubonic Plague
BBC: Madagascar faces a bubonic plague epidemic unless it slows the spread of the disease, experts have warned. The Red Cross and Pasteur Institute say inmates in the island’s rat-infested jails are particularly at risk.
…Madagascar had 256 plague cases and 60 deaths last year, the world’s highest recorded number.
Bubonic plague, known as the Black Death when it killed an estimated 25 million people in Europe during the Middle Ages, is now rare.
“If the plague gets into prisons there could be a sort of atomic explosion of plague within the town. The prison walls will never prevent the plague from getting out and invading the rest of the town,” said the institute’s Christophe Rogier.
Have a nice day.
Renovations
Commenting may be off for a few hours later today as we do some renovations to improve performance.
Thanks.
The Management
Banksy Comments on the Nobel Prize?
Mashable: Street artist Banksy set up a stall in New York’s Central Park Saturday, selling his original pieces — worth tens of thousands of dollars each — for $60.
The event was documented on video and posted on Banksy’s website. It took several hours for the first artwork to be sold, to a lady who managed to negotiate a 50% discount for two small canvases. There were only two more buyers, and by 6 p.m. the stall was closed with total earnings of $420.
For comparison, in 2007 Banksy’s work “Space Girl & Bird” was purchased for $578,000, and in 2008 his canvas “Keep it Spotless” was sold for $1,870,000.
What would Fama, Shiller and Hansen say about these asset prices?
Maximizing revenue for non-reproducible art is a matching process, the artist must find the handful of buyers in the world willing to pay the most (see An Economic Theory of Avant-Garde and Popular Art) so perhaps one can explain this as a failure of marketing.
An alternative explanation is that modern art is a bubble, people buy only because they expect to sell to others–take away this expectation and the art doesn’t sell. (Fashions and fads can help the latter explanation a long but there still needs to be an expectation of a future sucker buyer.)
Or perhaps Banksy is commenting on an earlier Nobel winner.
Lars Peter Hansen Nobelist
Hansen’s work is the most technical and most difficult to explain to a layperson. The brief version is that in 1982 Hansen developed the Generalized Method of Moments a new and elegant way to estimate many economic models that requires fewer assumptions and is often more powerful than other methods.
Here is the basic idea in a nutshell. The method of moments is an old and intuitive technique for estimating the parameters of a data generating process. A moment is an expectation of the form E(X^r), where r can be an integer. For example if r=1 then the first moment, E(X), is just the mean (you may also know that together the first and second moments, E(X^2), define the variance). If the true mean in the data generating process is M then we can write a moment condition, E(X)-M=0. Now the method of moments says to estimate M we should solve that condition by replacing, E(X), with the sample mean. In other words, a good estimator for the unknown population mean is the sample mean, i.e. the mean in the data that you have. Pretty obvious so far.
Now let’s start to generalize. First, there are many moments other than the mean and variance. Indeed economic theory often provides moment conditions that may be written E(f(X,M))=0 where M now stands for a moment not necessarily the mean and f can be a non-linear function. For example, rational expectation models often provide conditions that E(f(X))-M=0, i.e. that forecasts should equal true values, or macro models imply that various differences, such as in consumption levels should not be correlated and so forth. Indeed, finance and macroeconomic theory provided a surplus of moment conditions and many of these different conditions imply something about the same parameter. Now, and this is key, when we have more moment conditions than parameters we can’t choose the parameters to make all the moment conditions true, i.e. we can’t make all those moment conditions equal to zero. So what to do?
What Hansen did with the generalized method of moments is show that when we have more moment conditions than parameters we can best estimate those parameters by giving more weight to the conditions that we have better information about. In other words, if we have two conditions and we can’t force both of them to zero by a choice of parameter then choose the parameter such that the moment condition we know the most about (least variance) is closer to zero than the one we know less about. Again, the idea is intuitive, but Hansen showed how to make these choices and then he proved that when the parameters are chosen in this way they have good statistical properties such as consistency (they get closer to the true values as the sample size increases). Importantly, estimating a model using these moment conditions does not require untenable assumptions on the entire distribution of returns. Hansen then also showed, such as with Hansen and Hodrick (1980) and Hansen and Singleton (1982, 1983) how these methods could be applied to a large class of macro models and finance models including asset pricing, the latter of which links Hansen with the work of Fama and Shiller as does the important bound discovered by Hansen and Jaganatthan (1991).
Robert Shiller Nobelist
Robert Shiller is best known for warning about the internet stock market bubble and later the housing bubble. What is most impressive to me, however, is that most people who think that markets can be inefficient are anti-market. Shiller’s solution to market problems, however, is more markets! The housing market, for example, has traditionally had two problems. Since each house is unique there has been no market index of housing prices so that people couldn’t easily see bubbles and if they could see them on the ground there was no easy way to short the market (to try to profit from the bubble in a way that would moderate the bubble). Moreover, because there haven’t been good housing indexes a very large amount of each average person’s wealth has been tied up with an asset that can fluctuate substantially in price. Most house buyers, in other words, are putting all their eggs in one basket and crossing their fingers that the basket doesn’t go bust. In recent years, that has been a very unfortunate bet.
Shiller’s solution to the problems in the housing market has been to make the market better—he created with Case and Weiss–the Case-Shiller Index. For the first time, it’s possible to see in real time housing prices and compare with averages over time and it possible to buy options and futures on the index which will help for forecasting. Moreover, it’s possible that in the future insurance products can be built based on local versions of the index–thus you could insure yourself against big declines in the price of housing in your neighborhood.
Shiller’s housing index is also a window into how macro markets could also be used to create livelihood insurance, a type of private unemployment insurance. Moral hazard and adverse selection make it difficult to protect any single individual from unemployment but indexes in the unemployment rate of dentists or construction workers could be used to provide some insurance for workers in these fields when conditions in their entire industry are poor.
I featured one of Shiller’s biggest ideas in Entrepreneurial Economics, markets in GDP. A GDP market would allow shares of GDP to be bought and sold, add to this Hansonian prediction markets and you are long way towards an ideal way to evaluate the effect of major policies. Moreover, a GDP market would allow the creation of many insurance products. We are all less diversified than is ideal. It would be optimal to trade some shares in US GDP for shares in World GDP which is more stable. We can do this if we create Shiller GDP markets throughout the world.
Shiller’s book Macro Markets is truly visionary and I hope the Nobel brings a lot of attention to these ideas.
Eugene Fama Nobelist
As an undergraduate Fama worked for a stock forecasting service and he was tasked with coming up with rules to make money in the market. Time and time again he would find profitable rules only to find that they didn’t work in new data or out of sample. In graduate school he started talking to Merton Miller, Lester Telser, and Benoît Mandelbrot and finally hit on the idea that in an efficient market price changes would not be forecastable. The rest is history.
Fama’s dissertation and famous 1970 review article, Efficient Capital Markets: A Review of Theory and Empirical Work made efficient markets a touchstone for modern economists and finance theorists but practitioners hated and still hate the idea. Nevertheless, test after test showed that very few mutual fund managers beat the market and those that beat the market this year are not more likely to beat the market the next year. Chance and perhaps a few, very rare, geniuses explain the data. Eventually, hundreds of billions of dollars began to flow into index funds and today index funds manage over $7 trillion dollars worth of assets worldwide, making Fama the 7 trillion dollar man. Fama’s ideas have made an enormous contribution to how people invest, saving them billions in fees which generated beautiful homes for fortunate mutual fund managers but less than nothing for their customers.
The no free lunch principle is the most robust of the findings of the early Fama/efficient markets school. Other early findings such as non-forecastability of returns have been revised. The initial finding was that returns were not forecastable and that is true for short durations but it is now clear that returns can be forecastable over longer horizons! In particular, variables such as the dividend/price ratio can predict stock return variation years in advance! (Robert Shiller pioneered many of these kinds of studies as did Campbell and Cochrane). Fama, however, contrary to how he is sometimes represented did not reject these findings. Indeed, the less well known part of the story is that Fama working with French (e.g. Fama and French (1988a,1988b, 1993) has been among the pioneers in documenting and explaining these findings. What Fama’s later work has shown is that many of the anomalies such as time varying returns and the higher return to so-called value firms are real but they are not anomalies they are better explained as variations in risk premia tied to changes in the business cycle.
The CAPM (for which Markowtiz and Sharpe won the Nobel) suggested that the only source of true (priced) risk was risk that varied with the market return. That is one important source of risk but it’s not the only one, other types of macro risk which appear to vary with the business cycle are also priced and they are correlated with markers like the dividend/price ratio and the prospects for value and small-cap stocks. Thus, Fama showed that many of the seemingly anomalies (not all, however!) of the early efficient market tests can be better explained by a market model that incorporates more sources of risk. All of this work has really been a tour de force. It’s not often that the same person creates the theory and then participates in the first revolution overturning (some of) that theory.
Fama also pioneered the first event study! Fama, Fisher, Jensen, and Roll (1969) studied something a bit prosaic, stock splits, but the methodology, looking at how the stock market reacts to unexpected events, has seen been used to study what happens when Senators die unexpectedly (firms they support fall), what happens in close elections, which part was responsible for the Challenger space shuttle crash and many other events.
Online Education and the Tivo Revolution
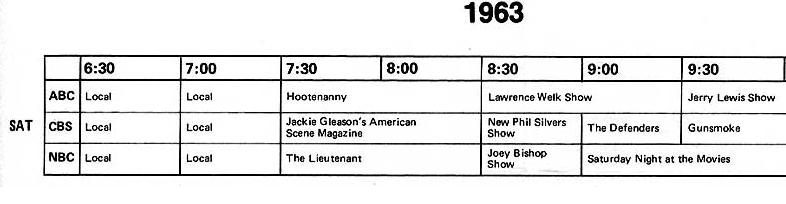
Here’s a TV schedule from 1963. If you wanted to watch Hootenanny you needed to be in front of the television on Saturday night between 7:30 and 8:30 pm. Have something else to do that night? Too bad. No pause or rewind either.
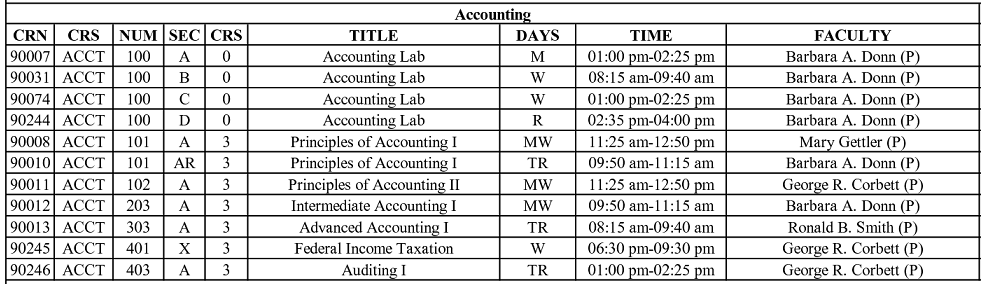
Here’s a college class schedule from 2010 If you want to learn Accounting with Ms. Gettler you need to be in class on Mondays and Wednesdays between 11:25 am and 12:50 pm (bring your lunch). If you need another class that’s scheduled at the same time, too bad. No pause or rewind either.
A TV Guide looks quaint. Tivo has liberated us from the dictates of the networks. Today we can get entertainment on demand. Next up, education on demand.
Nobel Offices
Here is a panoramic peek inside the offices of a number of Nobel prize winners, including Al Roth for economics. More interesting than it sounds with lots of Easter eggs.
Hat tip: Justin Wolfers.
The Adult Skill Gap
From the NYTimes reporting on the OECD Skills Outlook 2013, a study of adult skills.
The study, perhaps the most detailed of its kind, shows that the well-documented pattern of several other countries surging past the United States in students’ test scores and young people’s college graduation rates corresponds to a skills gap, extending far beyond school. In the United States, young adults in particular fare poorly compared with their international competitors of the same ages — not just in math and technology, but also in literacy.
More surprisingly, even middle-aged Americans — who, on paper, are among the best-educated people of their generation anywhere in the world — are barely better than middle of the pack in skills.

Trade, Development and Genetic Distance
Trade increases development but the main driver appears not to be comparative advantage and the standard microeconomic “gains from trade” but rather factors emphasized by Adam Smith and Paul Romer such as the increasing returns to scale that drives innovation and investment in R&D and also the ways in which trade increases exposure to and adoption of foreign ideas.
It’s much easier, however, to trade goods than ideas. The price of wheat shows strong convergence around the world by the 19th century but even simple ideas like hand-washing transmit much more slowly. Complex ideas like the rights of women, the rule of law or the corporate form transmit even more slowly. Thus, one of the barriers to development is barriers to the transmission of ideas.
Enrico Spolaore and Romain Wacziarg have done pioneering work uncovering some of the deep factors of development by using genetic distance as a measure of the difficulty of communicating ideas. Spolaore and Wacziarg have a short paper in Vox summarizing their methods and findings.
[G]enetic distance is like a molecular clock – it measures average separation times between populations. Therefore, genetic distance can be used as a summary statistic for divergence in all the traits that are transmitted with variation from one generation to the next over the long run, including divergence in cultural traits.
Our hypothesis is that, at a later stage, when populations enter into contact with each other, differences in those traits create barriers to exchange, communication, and imitation.
…Our barriers model implies that different development patterns across societies should depend not so much on the absolute genetic distance between them, but more on their relative genetic distance from the world’s technological frontier. For example, when studying the spread of the Industrial Revolution in Europe in the 19th century, what matters is not so much the absolute distance between the Greeks and the Italians, but rather how much closer Italians were to the English than the Greeks were. Indeed, we show that the magnitude of the effect of genetic distance relative to the technological frontier is about three times as large as that of absolute genetic distance. When including both measures in the regression, genetic distance relative to the frontier remains significant while absolute genetic distance becomes insignificantly different from zero. The effects are large in magnitude – a one-standard-deviation increase in genetic distance relative to the technological frontier (the US in the 20th century) is associated with an increase in the absolute difference in log income per capita of almost 29% of that variable’s standard deviation.
Our model implies that after a major innovation, such as the Industrial Revolution, the effect of genealogical distance should be pronounced, but that it should decline as more and more societies adopt the innovations of the technological frontier (which, in the 19th century, was the UK). These predictions are supported by the historical evidence. The figure below shows the standardised effects of genetic distance relative to the frontier for a common sample of 41 countries, for which data are available at all dates. The figure is consistent with our barriers model. As predicted, the effect of genetic distance – which is initially modest in 1820 – rises by around 75% to reach a peak in 1913, and declines thereafter.
Figure 1. Standardised effect of genetic distance over time, 1820-2005
