Category: Law
Towards a New House of Lords
In Britain, the House of Lords was traditionally dominated by hereditary peers–a right bequeathed by the monarch, sometimes in ancient times, to sit in the House of Lords that was transmitted generationally. That system has been withering away for decades, however, and was finally ended this year by the 2026 Hereditary Peers Act. So how should members of the House of Lords be chosen?
One idea which comes to mind quickly is selection by merit. Perhaps the House of Lords should be filled with Nobel Prize winners, wise professors, former politicians, distinguished public servants and so forth. All very well and good but the nub here is that these people have to be chosen by someone, and whoever controls the selection process inevitably influences the kind of people selected. That makes an appointed chamber less independent of, and potentially more similar to, ordinary politics, even with lifetime appointments. Moreover, what is their interest? Madison argued that for a good system “the interest of the man must be connected with the constitutional rights of the place.” A politicized selection of representatives, even meritorious representatives with lifetime appointments, may not differ enough from ordinary elected politicians to make much difference.
In 10% Less Democracy, my colleague Garett Jones, suggests that bondholders have a formal role in government. So let us consider, a House of Lords based on bond holdings. The advantage of this system is that bond holders are self-selected and their interests are in long-term stability–exactly what we want in a check on the popular house.
Votes in the House of Lords could be allocated proportionally to holdings; thus in practice we would get institutional representatives most notably including pension funds. If you want stability and growth, giving pension funds a bit more sway in national politics does not seem like a terrible idea. Bondholders would, for example, likely be more concerned with long-run financial stability, for example than current politicians seem to be. Should foreign holders of bonds be given a vote? Why not? Perhaps this would improve the prospects for peace. Although the popular house will always have the final say.
If anything, bondholders might prove too fiscally conservative as they are concerned primarily with default risk. The traditional House of Lords based on hereditary peers really amounted to a House of Lords based on landed property which isn’t a bad proxy for long-term stability and growth. After all, land owners do tend to do well when the country does well and you can’t take your land to another country. The ancient system had its wisdom; but landholding is not perfectly aligned with national prosperity. The House of Lords defended tariffs on imported foods (the corn laws) to promote land rents at the expense of food prices for everyone else. For similar reasons, we might, therefore, want to leaven the House of Lords with some equity, say ownership of Trills–the Robert Shiller idea for shares backed by real GDP. We would thus have a popular house and a corporate house divided into equity and bonds, all well aligned.
Democracy and Caeserism
In my 2015 post discussing Joseph Heath’s excellent book Enlightenment 2.0, I had this to say:
One of the reasons that I oppose the extension of democratic politics into every aspect of modern life is precisely that in trying to do too much, democracy delivers incoherence, gridlock and frustration, forces that eventually undermine its own legitimacy. I worry about democratic legitimacy because I see democracy as a check and balance on Leviathan (while Heath sees it as a check on government by experts).
The legislature has become a sideshow. But I worry, because the more Congress is held in contempt the greater the support for a bold executive that takes charge, makes decisions and gets things done. Under these pressures, executive power has grown not just in the United States but also in Canada and Great Britain (on this theme see F.H. Buckley’s The Once and Future King.) But for all its faults, the legislature and the rule of law are more conducive to liberty than the executive and the administrative state. Legislators are satisfied with reelection and a bit of pork but executives hunger for greatness and in so doing they promote the real dangers, idolatry, the centralization of power and war.
In short, I worry that the pathologies of democracy drive the demand not for rational, technocratic government but for Caesarism.
I should note that this was before Donald Trump was a Republican presidential contender, let alone a candidate for office.
Addendum: See also my review of Enlightenment 2.0. It has some good lines!
The propagandizing messages of markets and politics are also very different. Market messages are largely inclusive and cosmopolitan. Coca-Cola advertises “I’d Like to Buy the World a Coke” because they’d like the world to buy a Coke. Firms do try to build brand affiliation but they rarely do so by promoting hatred of their competitors. Pepsi doesn’t tell the Pepsi Generation that Coke drinkers are stealing their jobs and spitting on their gods.
Hat tip: @kingofthecoastt who recently tweeted about the original post.
My recent visit to Anthropic
I very recently participated in a two-day session to offer guidance on rewriting the constitution for Claude. The small group invited was uniformly excellent, we received serious time with key decision-makers, and the discussions were of very high quality.
Some of the points I stressed were the following:
1. Whatever one might take a “constitution” to mean in this context, it needs to borrow more from analogs to case law and the common law.
2. Along related lines, think more in terms of “Talmud,” and not just in terms of “Torah.”
3. Work to help build out a quality secondary literature on the AI constitutions and related documents. Currently this does not exist.
4. Consider how a panel of diverse AIs, with different prompts, could help to evaluate to what extent Claude (and other AI models) were acting in accord with their constitutions.
5. Have a final board of human adjudicators, functioning in a manner analogous to an independent judiciary. To the extent the panel of diverse AIs might have concerns about Claude not following its constitution, those AIs could alert the human adjudicators to what was going on. Those human adjudicators could then have authority over potential changes and remedies.
Here a recent short post on using internal courts and the common law to help govern/self-govern AI. And on the courts.
I thank Anthropic for having us in.
Breaking Ground: Can Refund Bonuses Solve the Holdout Problem?
My latest paper (with Cason and Zubrickas) has just been published by the Journal of Urban Economics. We show that refund bonuses can indeed improve the holdout problem.
Abstract: The holdout problem presents a pervasive challenge in situations that require the assembly of independently controlled assets, where due to complementarity the combined whole is worth more than the sum of its parts. One avenue for addressing holdout problems involves contingent contracts, where agreements are conditional upon reaching a predetermined threshold. This paper reports an experiment to investigate a new refund bonus contingent mechanism, in which asset owners who agree to participate (e.g., sell their asset) receive a bonus payment if the required threshold for project success is not met. The refund bonus eliminates failure equilibria and improves the frequency of successfully reaching the threshold in the symmetric mixed strategy equilibrium. In the experiment, individual asset holders choose each round whether to accept an offer to sell. Multiple owners must accept for the (contingent) sale to materialize, and holdout owners who do not sell can earn more, so the game has the strategic incentives of a volunteer’s dilemma. The data show that the bonus mechanism increases agreements to sell, the frequency of successful projects, and efficiency. By the second half of the experimental sessions, the total number of sales is 35 percent higher and the threshold is met nearly twice as often with the bonus than without.
I also cover this paper in my Refund Bonus (aka Dominant Assurance Contract) Explainer.
Capitalizing untethered AI agents
That is my latest piece of writing, co-authored with Sonia Farrell Pearson of Harvard. Here is the opening premise:
As early as 2017, the European Parliament floated “electronic personhood” for robots. More recently, a handful of U.S. states introduced legislation explicitly barring AI from legal personhood; and early this summer, President Milei of Argentina proposed letting AI agents own, manage, and bear responsibility for their own corporations.
In response to Milei’s announcement, Yuval Noah Harari pointed out that we have no way of holding an AI agent accountable. What, he asks, could we do to an entity which has neither money to lose nor a body to incarcerate? As Shruti Rajagopalan, a Senior Research Fellow at George Mason’s Mercatus Center, explains: AI “can act intelligently, but only humans respond to the incentives the law creates”.
This question matters now: there are already ways an agent could become fully untethered. By “untethered” – a central concept in this essay – we mean that there is no meaningful or actionable way to trace the actions back to a legally accountable human or institutional entity.
For one, people can and do set agents free, on purpose. An agent could be created by a human or a company that intends to monitor it but then dies or disappears. Or perhaps the entity that created the agent is based in a country like North Korea, not reachable by standard laws.
In other cases the agent might not need to “escape” at all: the agent could be ‘controlled’ by a shell corporation that, while formally owned and traceable, provides no true defendant or ability to satisfy claims. Or perhaps a process spawns a chain of agents so long that the actions of a subagent can’t be tied to the original agent’s creator, neither epistemically nor meaningfully. Even if we can identify the model’s original creator, what if it’s been finetuned, or merged with another model that was created by someone else? The law might eventually untangle these kinds of complex cases, but we foresee an intermediate period where it does not.
And then there’s the user, who makes choices about what the models should actually do. The Hugging Face incident was unusual in that OpenAI was both the model’s creator and its user. But now close to a billion people use these systems: when blaming the creator is legally inappropriate, will it always make sense to blame the user?
The essay considers to what extent capitalizing the untethered agents — requiring them to hold a certain amount of capital — can serve the end of better alignment. About 22 pp., published on Sonia’s Substack, definitely recommended.
Somalia facts of the day
The fruits of better security are plain to see. “Business is booming,” says Gamal Hassan, the commerce minister. New buildings are going up at a frenetic pace. The district around the airport, in particular, has grown much denser (see satellite images). Dahab Tower, a 26-floor confection of luxury flats, a mall, a gym and a mosque, is due to open this year. It sits close to the spot where, in 1993, the bodies of two American soldiers were dragged through the streets after militiamen shot down a Black Hawk helicopter. Nearby is Beydan Coffee, a thriving pan-African chain founded by a Somali who returned from Sweden in the 2010s.
What explains the lull in attacks is less obvious. The government boasts that, in the words of a former intelligence officer, it has “completely closed the doors” on al-Shabab. Mr Mahmood of the ICG credits “prosaic” measures such as the spread of CCTV
cameras, and an electronic database that police equipped with iPads use to identify civilian cars at checkpoints. Plainclothes intelligence officers have been deployed in large numbers.
Here is much more from The Economist. I will repeat my recent point that many dangerous places in the world are about to become much, much safer.
Things you cannot buy in America?
3. Exterior roller shutters (Rollladen)
In much of Europe, homes feature heavy shutters integrated into the exterior of the window, enabling total blackout and better insulation. Sleeping in true, complete darkness—not “blackout curtain” darkness, but can’t-see-your-hand darkness—is an experience most Americans will never have. These shutters are nearly impossible to get in the USA because these shutters are built directly into the home during its construction. They are fundamentally incompatible with standard American wood-frame, siding, and drywall construction, meaning there is no domestic supply chain to support them, even if you built a house to fit them.
From Daniel Frank, here is the full piece, noting I am not convinced you cannot get a “grass roof,” among other items mentioned. In any case an interesting list, file under “possibly thwarted markets in everything.” Via Anecdotal.
A Conservative Case for Liberal Immigration
That is the title of my latest Free Press piece, here is one excerpt:
Or look at the AI revolution, another area where America is leading the world and also using its AI models to exert soft power. Dario Amodei of Anthropic has an Italian father, neural-network pioneer Geoffrey Hinton is originally from the U.K., and Elon Musk and Peter Thiel, who helped initially fund and found OpenAI, are from South Africa and Germany, respectively. OpenAI co-founder Wojciech Zaremba is from Poland. Musk and Thiel, of course, have other achievements to their credit as well. A significant portion of the employees at the major labs are Chinese. In one survey of published AI researchers, 38 percent received their undergraduate education in China, and 72 percent of those are working in the U.S.
Recommended, do read the whole thing.
That was then, this is now
I very much like the new Michael Khodarkovsky book The Steppe and its Empires: The Russian Empire & its Eurasian Counterparts. Excerpt:
Russia presented the most remarkable contrast to both Eurasian and Western empires. The oower of Moscovite tsars and Russian emperors seemed to be completely unconstrained by moral or ethical boundaries. Whereas religious authorities in Europe, the Islamic world, and Cjhina kept some distance from the state and had a degree of independence from the rulers, in Russia the Orthodox Church was fully behind the autocratic powers of the tsars. Ivan III was the first to adopt the title samoderzhets (a calque of a title of Byzantine emperors, literally “autocrat” in Greek), which he used in the sense of a “sovereign” ruler. It took another half century before his grandson, Ivan IV, began to use the title to signal his exceptional, universal, and unrestrained power.
And:
To begin with, each Eurasian ruler conceived of himself as the sovereign of a universal, not natinoal, empire. Such a ruler was non plus ultra; confident in his superiority over other religious or political bodies, he was destined to rule the world, if not politically, at least rhetorically, an autocrat whose subjects’ servile condition was a natural state.
Seen through the prism of a universal monarchy, the Eurasian imperial vision blurred the separation between metropolis and periphery, between the peoples within and outside the empire’s boundaries, between servitude and slavery. Whether they were elites or commoners, all were considered to be in personal servitude to an emperor and often referred to by a term interchangeable with slave.
Consequently, Eurasian societies did not develop either the notions or the institutions that could enshrine the idea of freedom…
The concept of universal monarchy allowed for little differentiation between internal and external territories.
Recommended.
Regulated Markets Are Slow to Handle Change
Gowrisankaran, Langer and Reguant have an excellent paper, Energy Transitions in Regulated Markets (WP), in the latest AER.
The basic idea is that regulation designed to prevent utilities from building useless power plants can induce them to keep obsolete power plants. Some background. We regulated electric utilities under the theory that they were natural monopolies and therefore we would do better by pushing their prices down. What’s a reasonable price? Hard to say, so regulated utilities were allowed to recoup their operating costs plus a fair return on their “rate base”—their capital stock. Makes sense, but once profits depended on the size of the capital stock, utilities had an incentive to build too much—the classic Averch–Johnson effect. Regulators responded with “prudence” requirements and the rule that capital must be “used and useful.” In a stable world, that rule is a check, albeit an imperfect check, on so-called gold-plating.
But now consider what happens in a time of technological change, such as a rapid decrease in the cost of generating electricity with natural gas (driven by fracking and improvements in combined-cycle natural-gas (CCNG) technology). In a free market, large decreases in costs would cause firms to abandon coal and move to natural gas—some would do this to make profits, others to avoid losses. In short, the market forces sunk investments to be abandoned when not profitable.
But there is another possibility under regulation. Tell the regulator that your plants are still viable. Well, telling is cheap talk so you keep burning coal to prove that the plant remains useful. If you can keep your base operating that’s better than abandoning it and to signal how valuable your coal plant still is, it may even be worth while to burn coal when the cost exceeds the price of electricity! The authors have some nice data on exactly this point.
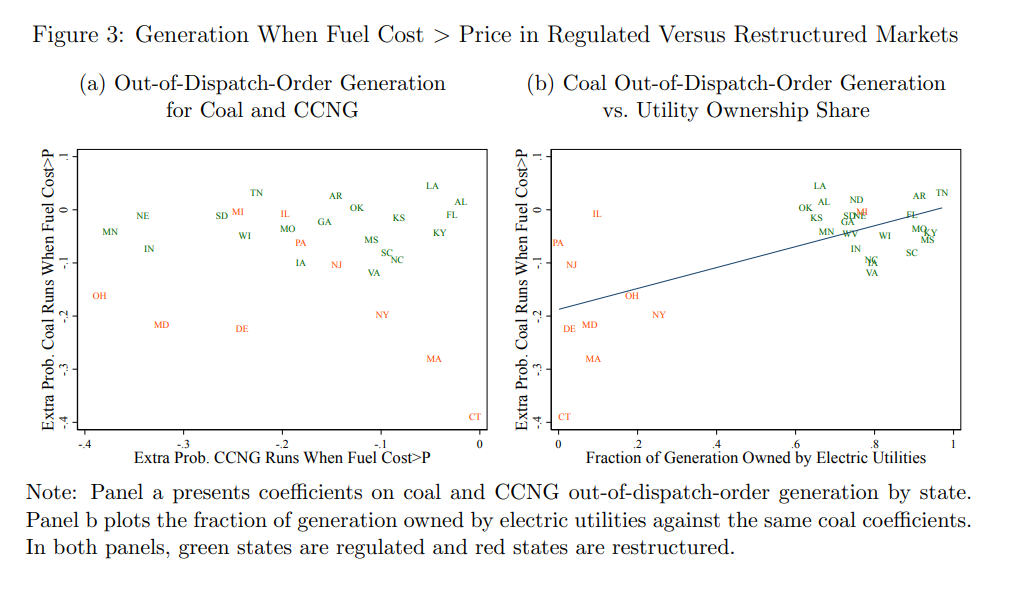
Figure 3 takes a little work to understand, but the pattern is clear. Each point represents a state. In panel A, the vertical axis shows how much less likely a coal plant is to run when the cost of coal exceeds the price of electricity. Obviously, a strongly negative coefficient is the economically sensible response: when burning coal is more expensive than buying electricity, the plant should burn less.
The red points represent restructured states and the green points regulated states. In restructured states coal burning falls when prices fall, just as expected. Coal burning in regulated states responds much less. (I.e., the red points generally lie below the green points.) Indeed, the six states with the largest reductions in coal operation are all restructured states.
One objection to this analysis might be that utilities in general are just slow to respond to prices, so on the horizontal axis the authors plot how well utilities respond to a higher price of gas. Note that these coefficients are all negative and there is no obvious difference between regulated and restructured states. In both types of states, utilities respond well to the price of gas, but only in restructured states do utilities respond strongly to the price of coal. (Why coal and not gas? Because the used-and-useful standard binds on capital whose usefulness is in doubt—which, once gas got cheap, meant coal. In other words, the utilities have to defend coal to the regulators, not gas.)
Panel B on the right shows a slightly different way of presenting the same data. The vertical axis is again how much less likely a coal plant is to run when its cost exceeds the electricity price. The horizontal axis is the fraction of generation owned by electric utilities. Regulated states tend to be vertically integrated, while restructured states opened electricity generation to competition, so utility ownership and regulatory status are closely correlated. Regulated states generally have utility ownership above 60%, while all the restructured states but one are below 30%. The best-fit line slopes upward: in other words, the more generation a state’s utilities own, the less coal dispatch responds to price. A different perspective on the same story.
That is the direct empirical evidence. The authors then construct a more ambitious structural model. In theory, regulation could produce either too much or too little investment in the new technology; their estimates imply too much. Much, too much. Not only do regulated utilities retain too much coal, they also build too much gas capacity. In short, they accumulate both too much old capital and too much new capital. Averch–Johnson on steroids.
The bottom line is that regulation under dynamic conditions is much more difficult than under static conditions. My view is that it may not even be worth the candle.
Intergenerational mobility of immigrants in 15 destination countries
We estimate intergenerational mobility of children of immigrants in fifteen receiving countries. Children of immigrants have somewhat lower income than children of local-born parents. Around half of this gap can be explained by differences in parental income, with the remainder due to differences in mobility parameters. The daughters of immigrants enjoy higher absolute mobility than daughters of locals in most destinations. Absolute mobility of sons of immigrants is higher outside Europe and lower in Europe compared to sons of locals. Cross-country differences in absolute mobility are not driven by parental country-of-origin, but instead by destination labor markets and immigration policy.
Here is the paper, by Leah Boustan, et.al. Via the excellent Samir Varma.
Impedimenta Developerum!
NME: Harry Potter fans have succeeded in moving a construction project that would have originally gone through the “grave” of the character Dobby.
The 125-mile Greenlink power connector, which costs £430million, is intended to link power between the UK’s National Grid and Ireland, running between County Wexford and Freshwater West in Pembrokeshire.
However, the latter site is known to Potter fans as the site of house elf Dobby’s grave in the film Harry Potter And The Deathly Hallows, and contains a pile of stones with the words “here lies Dobby” that many flock to…
All I can say is that Voldemort would never have put up with this shit.
The Binmen of Birmingham
I was on the British CapX Podcast talking about the Equality Act, riffing off my two posts Equality Act 2010 and The Apples and Oranges Tribunal. One thing I discussed in the podcast which I haven’t blogged on is the amazing Birmingham dustbin dispute.
In 2010 an employment tribunal ruled that Birmingham City Council had discriminated against thousands of female workers — cooks, cleaners, care assistants, caretakers — who were denied bonuses paid to the mostly male binmen, gardeners, and gravediggers. Why were the binmen given bonuses? Well, refuse collection is filthy, heavy, outdoor work and not many people want to be gravediggers. Thus, these jobs command a premium for exactly the reason Adam Smith gave in 1776 — compensating differentials. Or was it sexism? Well, note first that there is nothing stopping women from becoming “binpersons” and indeed there are female binpersons and they earn the same bonuses as their male counterparts (just as with the Next case). Moreover, we can test the sexism versus compensating differentials theory. Let’s see what happened.
Here’s the problem, which contributed to Birmingham going bankrupt in 2023. The council employs roughly 400 binmen and something like 6,000 women in comparable graded roles. Every extra pound paid to a binman therefore implied about fifteen pounds owed to the cooks and cleaners. The council simply didn’t have the money to pay everyone binman wages so they cut the binmen’s wages. But the market wage for collecting rubbish is what it is, so when Birmingham finally deleted the premium in January 2025, the binmen went on strike — and they are still on strike, nearly eighteen months later. The rubbish piled up, 17,000 tonnes of it, and the city declared a major incident.
Here’s the most amazing part. The council hired an outside contractor to take over its rubbish collection and it now pays roughly triple its pre-strike outsourcing bill–more than it was paying its own employees. So much for sexism. Apparently the premium wasn’t a favor to men; it was the price of the job. If you want your rubbish picked up and your graves dug, you must pay the market wage. This was pure regulatory arbitrage, of course. Because the new binmen were contractors they legally had a different employer than the Council’s female caregivers and the Act’s comparator rules stop at the employer’s nexus.
The government mandarins, of course, want to close the “loophole” adding yet another bureaucratic requirement to push the equal pay madness up the supply chain. The rubbish piles up.
Estimating the Economic Value of Zoning Reform
We estimate the economic value of zoning reform in São Paulo, which altered maximum permitted construction along transportation corridors. Developers increased filings for multifamily construction in blocks affected by the reform, leading to more housing supply and lower housing prices in neighborhoods that allow more densification. Our equilibrium model of housing markets estimates an aggregate 1.6 percent increase in housing stock and a 0.4 percent reduction in prices, resulting in large housing wealth transfers from current to future homeowners. The reform produced welfare gains of 0.65 percent of city GDP, mostly due to developer profits and consumer gains from the newly built environment.
That is from the AEA policy journal, by Santosh Anagol, Fernando Ferreira, and Jonah Rexer.
The economics of H-1B immigration
We study the effects of H-1B immigration on U.S. industries that employ H-1B workers and their trading partners. Using a novel cross-industry design and the 1999–2003 expansion of the H-1B visa cap for identification, we find that H-1B exposure raised incomes for natives and pre-existing immigrants, with gains concentrated in non-STEM occupations. Income gains propagate forward through supply chains to downstream industries but not backward to upstream industries, consistent with a productivity shock rather than a labor supply shock. We find no direct effect on patenting, suggesting that productivity gains arise from better task execution rather than patentable invention.
That is from a new NBER working paper by